
Day 79: Self Storage Seller Financing: When It Actually Works and How to Structure It
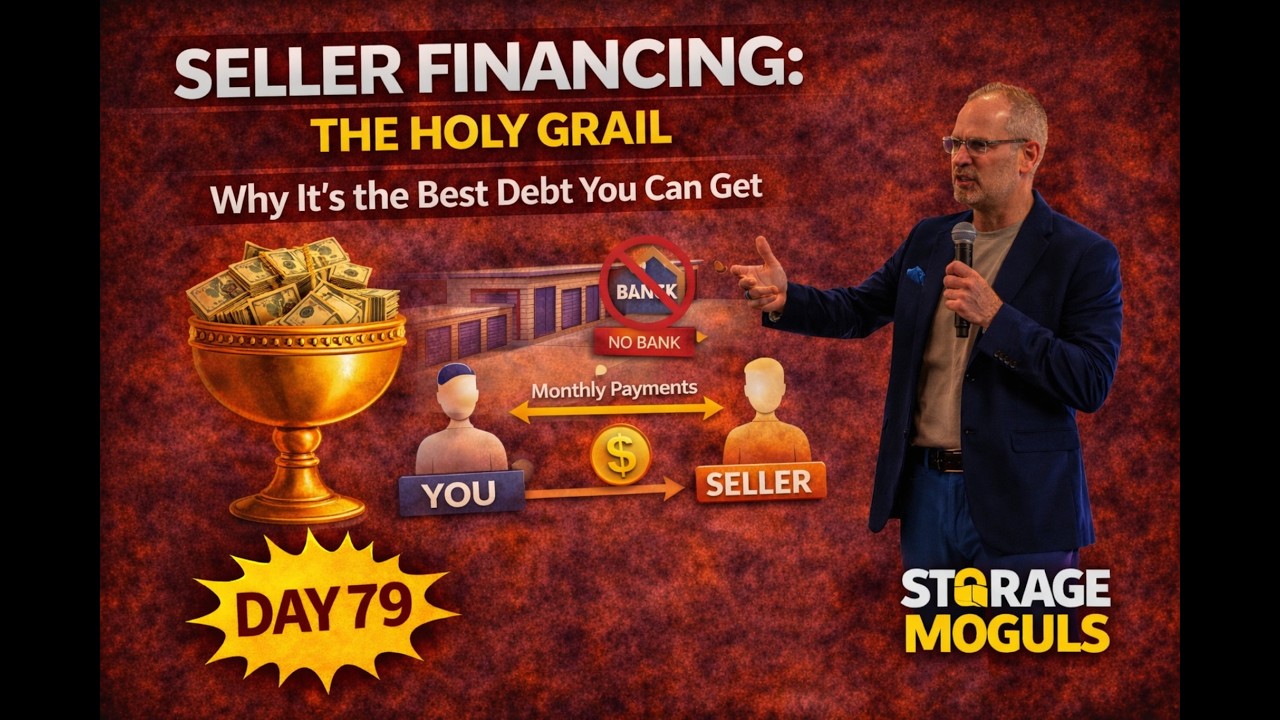
Joe Downs explains seller financing for self-storage deals: the seller acts as lender, buyers get 10-20% down with 4-6% interest over 25-40 years, and sellers defer capital gains tax across payments. Watch for due-on-sale clauses and foreclosure risk.
Chapters
All right. Welcome folks. Day 79 of the Storage 100 series. I am of course Joe Downs with the Storage Moguls Mastermind. We talked about seller financing back in section 3, but today we're going to go deeper. When does it actually work? When is it a pipe dream? If you want more conversations like this, by the way, with real operators, join our Storage Moguls community for free at storage moguls.ai. Storage moguls.ai. Why.ai? Because it's an AI-native platform with GPT tools, multimodal learning, and content spanning every storage vertical. Start for free, advance at your own pace. But in the meantime, today we're talking about one of the most powerful tools for buying self-storage, in my opinion, and that's seller financing. This is not just another way to get a loan, folks. It's the holy grail of real estate debt. It fundamentally changes the game by cutting out the institutional middleman. When you get seller financing, you're likely getting the best possible terms you could get. It allows you to control the deal structure and the closing timeline. This is how you scale faster without being bottlenecked by traditional banks. So in this episode, we're going to break down exactly what it is and why both buyers and sellers love it. So what is it? It's simple. The seller acts as the bank. So instead of you going to Wells Fargo for a loan, The person selling the property gives you the loan by just creating a note or a loan for the amount you would've had to borrow from the bank to buy the property. Get it? There's no money that changes hands other than deposits, right? And down payments and that. But they're not lending you money. I mean, you could look at it that way. They're lending you money and you're giving it back to them, but you get it. That's how it works. So you make your monthly payments directly to the seller. And not to a bank because the seller just became the bank. So this means you're negotiating the interest rate, the term, and the down payment directly with the owner. There's no loan committee, no underwriters, no bureaucratic red tape, and very few covenants. This direct relationship is the key to getting deals done faster and on your terms. Why would a seller agree to do this though? What's in it for them? Well, let's cover that next. The pitch you need to make to the seller. The first and most powerful reason a seller should be interested in seller financing is that they continue to receive a monthly income. They get the cash flow, the income stream without the headaches of managing the facility. Second, the tax deferral. Very compelling tax incentive for them. They can use an installment sale to spread their capital gains tax over many years. This avoids a huge tax bill. And the year of sale, which is a major win for them. And finally, you can offer them a higher purchase price because you're getting better terms. That's the trade-off. They get their asking price and you get the best financing available. So that's the seller's side outlook and benefits. What about the buyer's side? Why would we do it? Guess what? The benefits for us are even better. First, you need a much lower down payment than traditional bank, so you can often get away with 10%, maybe 20% down. So keeping more of your capital liquid. Second, you eliminate all the junk fees that the banks charge. You have the option to save thousands— option, I say— to save thousands on appraisals. You don't need one. Lender requires one. You won't need one. Environmental reports, loan origination fees. I'm going to put a little caveat here. Joe Downs speaking and Bellrose Group, what we do, I would still get an appraisal. I would do an environmental if it— if I'm not even sure, you know, if it's a close call, I'm doing it and survey, appraisal and survey no matter what. I'll give you a whole bunch of reasons. In fact, we talk about them in the Storage Muggles community. Third, terms are completely flexible because you're negotiating directly with the owner. You control the interest rate, the amortization, and the balloon payment schedule. Assuming you don't get the seller to agree to interest only. All of ours to this point have been interest only. And finally, you can close in weeks, not months, because there's no loan committee to wait for. So what are the specific terms you should be targeting then in your negotiations? You might be wondering. Well, the interest rate is, of course, one of them. Cost of borrowing. Since there's no bank, you actually can negotiate that pretty hard. In fact, that's one of the ways we talk about it. It's like there's different dials and levers you can play with. Interest rate's one of them. Down payment's another. Term is another. So you want to aim for an interest rate between 4% and 6%. Anything higher starts to eat into your returns. Then you got the amortization schedule, which determines your monthly payment size, the amount. So the longer you spread it out for, the lower the payment. So target a long one, 25, 30 years. You go 40 years. I mean, at that point you might as well go interest only, but the whole point is to keep your monthly payments low like interest only does. The balloon payment, whether you have amortized or interest only, is when the full remaining balance is due. So you want to give yourself some time, at least 5 years. A lot of sellers don't realize that 5 years is more of a commercial timeline. Go 10 or 5 with an option for 5 because you need that time to execute your business plan and either refinance or sell the property. And then finally, keep your down payment low. So you can get away with 10%, maybe up to 20%. That's going to— the seller's going to— well, we'll get into it in a second, but that's going to maximize your cash-on-cash return for sure. These 4 terms are the levers you make or the levers you pull to make the deal work for you. All right, so let's take a look at the installment sale tax benefit for the seller. And then in a couple slides, I want to come back to something I just said. Sure. show you how it works. Because this is usually one of the key selling points for the seller, or one of the— and they might not realize it, but it's one of the ways you can get them to agree to carry the note. So, so at this stage here, traditional cash sale creates a tax time bomb for them. The seller gets hit with a huge tax bill in that year of sale because the entire gain is realized immediately. And What they don't realize, and this is not tax advice, that's what we're going to do the whole, you know, everyone should both buy or sell, get tax advice from a professional. But what sellers don't usually realize is they think, oh, I'm paying 20% on the gain. Yeah, but also you're going to recapture all the depreciation you took too. So it's a big tax bill. So this often pushes them into the highest tax bracket in that year and they lose a huge chunk of their profit to the IRS right away. With an installment sale, They only pay tax on the principal payments they receive each year. So if it's an amortized loan, they're going to receive in year 1 the down payment and then the amount of principal you pay each year. If it's interest only, they're not receiving principal every year. So this is tax deferral though. It's not tax avoidance, but it keeps their money working for them longer. Pitch is simple. Why give 20% plus all of your recapture Or more to the IRS when you can keep that money invested and earning interest for years, right? Because you're paying the interest to them. Benefit's huge, but you can't just ask for it directly. You need a strategy. And this is what I want to cover next and come back to what I said before, because sure, we know the tax benefit is the hook. It's the hook that's off the hook, but you can't just blurt it out. Will you carry the paper? That sounds aggressive. It makes you look Like a desperate buyer who can't get bank financing. They don't even know you, right? The strategy is to solve their problem, not ask them to solve yours. So you start by asking a simple open-ended question. It could go something along the lines of, hey, what do you plan to do with the proceeds from the sale? You know, you're moving to Florida or you're buying an RV. What are you doing? They get talking. This usually will help you find out their true motivation, what they need the money for. So you listen for pain points. Like they might say something like, I don't know, I'm a little worried about the tax hit, or I don't know, I'm going to have to find something to invest in because I'm going to have to give up that monthly income from storage that I was relying on. Those are key things to listen to because once you identify their problem, now you're offering them a solution and you want to frame it as a benefit to them. You can say, well, I might be able to help you defer some of those taxes if we were to structure something like this. I mean, I can go to the bank and get the loan, Or I could work— I could help you and keep your monthly income stream flowing too while we do that. This approach shifts the conversation from you asking for a favor to you offering a valuable service to them. And when I was referring to the levers before, we'll come back to this in a second. When I was referring to the levers and dials before, a lot of times what we do is back into it. So they might need more of a monthly payment. So maybe I have to increase the down payment or the interest rate, but reduce the down payment or reduce the sales price. Sometimes it's vanity. They want to be able to tell their neighbor they sold it for this. Well, okay, if that's the sale price you need, I might need to bring down the interest rate to make the payment work, to make the deal work for me. So there's different levers and dials you can play with. All right. While seller financing is powerful, it's not without risk, though. You need to be aware of 2 major dangers. The first is the due-on-sale clause. Which is in almost every commercial mortgage. So if they have an existing mortgage, sometimes this doesn't work because transferring the title to you can trigger the bank to call the entire loan due. And in this case, we'd be using like a wraparound mortgage or something. If you can't pay off the loan instantly, meaning, you know, if they have $100 grand left and you're putting $300 grand down, it's probably not a problem. But if they can't pay it off, if you can't pay it off, the loan instantly uses the property and the seller's in default, right? Your attorney would never let it go here, but that's on paper how it would work. The second risk is seller foreclosure if you default on your payments to them. Don't default on your payments to them. But in many states, you know, seller can take that property back pretty fast, faster than the bank could even. So you don't want to just willy-nilly do this. You want to make sure that you're buying yourself a good deal and that makes sense and the cash is going to flow. So, and you need— folks, bottom line is have an attorney. Review the documents and ensure you're protected against all these scenarios. And I highly recommend not just any attorney. Use a great storage-specific real estate attorney to draft the docs for you so you know you're protected. There are attorneys like this are used to seeing these deals and have probably structured these before. So understanding these risks are critical, but they shouldn't stop you from pursuing the strategy because if you can get seller financing, you should always take it. It's the single best way to acquire property because it offers Better returns, faster closing, more flexibility than any bank. I didn't even talk about the covenants really, and I don't want to on this. We'll talk about it in our community though. It's the ultimate win-win. The seller gets a tax benefit and a reliable income stream. You get the property on your terms. So never pass up the opportunity to use the seller's motivation to your advantage. All right. I hope you found how to structure a deal using seller financing as awesome as it is in actual reality. Because it is awesome. If so, please like this video because it helps us reach more people who want to learn about self-storage investing. Subscribe to the channel so you don't miss any of the daily Storage 100 lessons, daily drops, lives like we had the other night, and share this video please with your network. Do it for you because out there in your network somewhere, someone looking for the first deal, they will thank you later and you will thank me later. If you actually like, subscribe, and share all these videos you watch, because everyone in your network will know you're in self-storage, and you're going to thank me later when you find out just how valuable that was. And remember, seller financing works when the seller's motivation aligns with your structure. Period. It's not magic. It's negotiation and timing. If you want to workshop your seller financing pitch with other investors who've done it, it's exactly what happens inside Guess Where? Storage Moguls community. So join for free. There's a seat waiting for you. StorageMoguls.ai. See you tomorrow.
More from Joe





The tenant only paid for the first month! #selfstorage #horrorstory #realestateinvesting

What happens when a storage tenant stops paying? #selfstorage #realestateinvesting #storagemoguls



