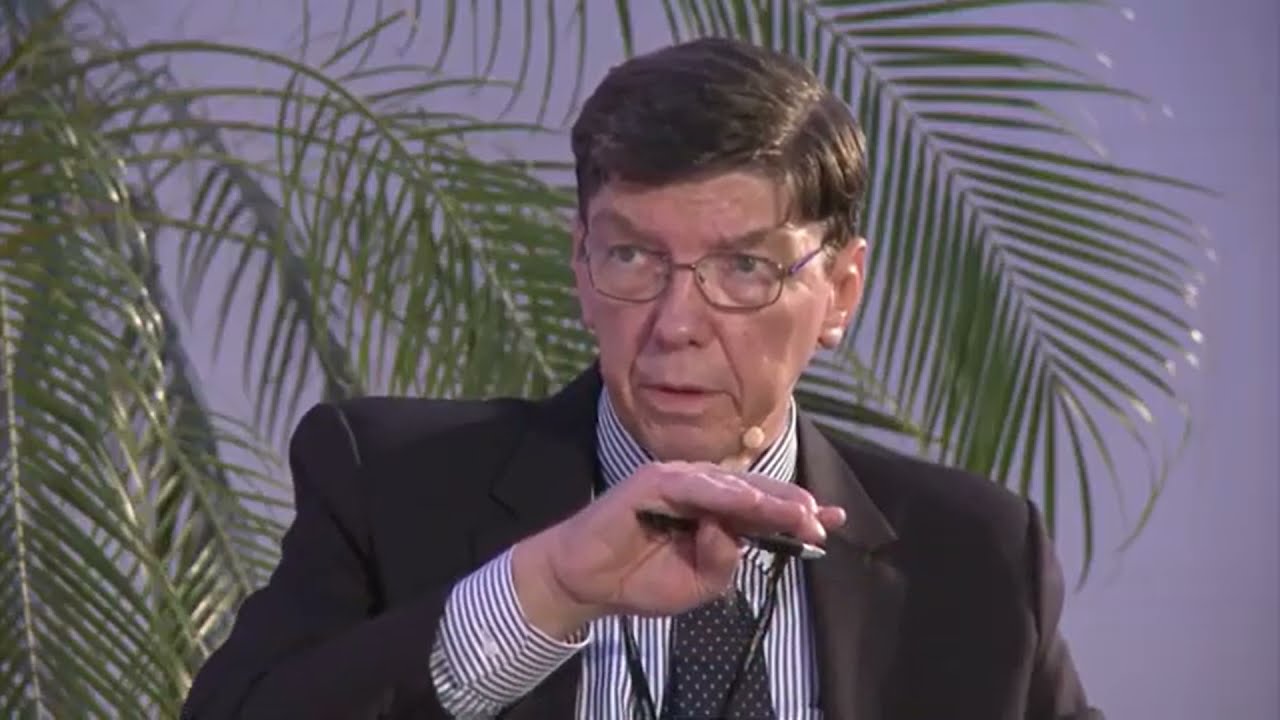
In a Drucker Forum panel, Clayton Christensen and other speakers critique the American public capital markets, arguing they have shifted from a source of economic strength to a competitive handicap. Christensen describes a privately managed fund that invests exclusively in disruptive companies, which has delivered a 36% compounded annual return over 11 years despite two recessions, illustrating the power of applying proven management theories. He laments that most entrepreneurs and venture capitalists ignore this research, limiting their success odds. The discussion then turns to a question from Milena, a Drucker Challenge finalist, about which metrics early‑stage founders should track when they have only data access versus when they can engage customers directly. Christensen is prompted to advise on practical, theory‑grounded metrics to avoid cash burn and gauge scalability. The segment underscores the tension between data‑driven decision‑making and causal management theory, and highlights the need for founders to adopt evidence‑based metrics rather than rely solely on raw data.
Chapters
Successfully in the core business.
So it's interesting. I mean, what you're saying is actually connecting to what you were saying earlier, is that capital markets can be a liberator or a prisoner.
Yeah, and they become more a prisoner than a liberator, right? I mean, I think the public capital Markets are— the American public capital markets now are a detriment to American competitiveness and success, full stop. I think we've just gotten— we've gotten to the crossover point where they're a net negative. Something that's been a huge advantage for America economically, having sort of the biggest, richest capital markets in the world, has become a negative. And I think we're going to go to an era where there's going to be the— we're going to look back on this era 20 or 30 years from now, we're going to look back on the era, the second half of the 20th century, and say, what the hell were we thinking? Why did we think widely held publicly traded corporations were the ultimate economic form? What were we thinking? We were so nuts. That's crazy. It was terrible. That's what we'll be thinking in 20 years.
Sarah?
Okay, so then we have to move to the audience. Yeah.
Just to build on that, we set up a fund in which the fund would only invest in companies that were disruptive, in our language. And we had a criteria, which is if it did what the theory says they should do, they'll be successful. And that fund has been operating now for 11 years, and the compounded annual rate of return on that fund in publicly traded companies has offered a 36% compounded annual rate of return, even with 2 big recessions in the middle of that. And what's interesting, Roger, is that this fund is the only fund that pursues that strategy. The market won't allow people to do what, you know, they should do. And it's very interesting to me. The probability that you'll be successful if you follow theories of management that emerge from this group The probability of success is well over 80%, but entrepreneurs or venture capitalists don't study any of our research, and therefore they can't invest in, in doing what we know is proven to be valid. So I'm— anyway, I, I, I'm grateful that there are opportunities to succeed, but I I don't have much confidence that the current structure can do it.
The current structure, yeah. I'm going to suggest that we move to some audience questions because I'm worried about that. But we are going to kick that off with a question or a comment from one of our Drucker Challenge finalists, Milena. Is Milena here?
Oh, there's a hand up there. That might be her.
Maybe.
Thank you for the wonderful opportunity to address the giants of management. My question is about 3 young people who started a company, and for them entrepreneurship at the moment is not a backup plan. One of them is marketing person, one of them chief technology officer, and one is business development guy. And let's imagine they are on a remote island and they just have access to data. And what metrics you will advise them to use so that they know they are not burning money? that basically their company's gonna scale? And in second scenario, what metrics you would allow— would you advise them to use in case they actually go and speak to their potential customers, both online and offline? Thank you.
Someone wanna grab that? Go, Clay.
I have an opinion on your question. And that is, it turns out that data was never created by God. Data is a representation of the phenomena, but data is not the phenomena. And when we try to create, use— and so every piece of data is created by a person, and that person had to take Some elements of the phenomena and include it in the data, but they have to represent— they have to take other elements of the phenomena and exclude it from the data. And as a consequence of that, data is always— the best they can be is half correct. And therefore, when you're making important decisions of the sort that you're talking to, and you try to build your decision in any way by looking at what does the data say, it is partially true. It only relates to the past. And therefore, you're just, you are desperate to have a theory that allows you what causality is at work there. And you need to make your decisions based upon theories of causality in management, not by data. And I have a— I haven't died yet, and so I don't know what it's really going to be like, but I'm just imagining that when I die, if they let me in, I'm going to look around and there won't be any data in heaven anywhere. And so I'm going to ask them, When they're taking me on my tour, my guide, I'm going to say, how come there's no data in heaven? And they're going to answer to me, well, because data lies all the time, and— or tells half the truth. And so when data tries to be admitted into heaven, we always send data to hell. And that's kind of nice for me because when people ask me, show me the data, I just have to say, go to hell. So I'm going to be