How I lost $500M and still won, lessons from a VC and CEO
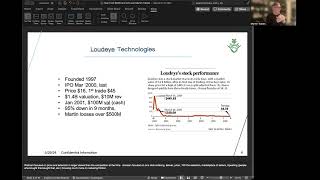
Martin G. Tobias lost roughly $500M in net worth across two CEO roles: Loudai went public at $16 in 2000 and crashed 95% in nine months; Upgrade Labs hit $6M revenue before COVID wiped it out. He shares what those failures taught him about cycle timing, burn rate, and why starting companies today is easier than ever.
Questions this video answers
March 17, 2000
$5 million raised on a $10 million pre-money valuation (1997 Series A)
IPO price $16; first trade $45
About $10 million in revenue
Just over 40% ownership at IPO
Chapters
It. Sam. Hi, Martin. We, we can't hear you. Oh, hello.
No one, no one can hear you.
Oh, hello. Sorry about that. Oh my God. Hi everybody. That was the problem when I let me mute. Mute every. Let me go back to the beginning then and start over. I'm Martin. Hi. Technical difficulties here. This is part of an ongoing series we're doing for venture capitalists and founders talking about how to invest in early stage and how to start early stage companies. And what I thought I'd talk about today was my experience as a CEO and what it's taught me to hopefully be a little bit of a better venture partner venture capitalist. And part of that is, you know, having started companies that ended up, know, being worth a lot of money and then all of a sudden not worth a lot of money. I'll give two examples of that as a CEO. I just wanted to give a little more background on me as a venture capitalist. I've been a 20 year pre seed investor. Turns out this slide is not correct. I haven't done 72 investments. I've done 74 investments and six of them were unicorns. I have a syndicate on angel list with about 3,000 LPs. I had a prior fund of about $2.5 billion and I started venture capital as a venture partner at Ignition Partners, which are a bunch of ex Microsoft guys. About 4 billion under management and I'm an LP in 17 funds. As a CEO, I was a 3 times venture backed CEO with 2 IPOs. I raised over $500 million for my companies and I was at Microsoft and Accenture back in the day. Some of the companies I invested in recently are companies like Deal and jeeves that were B2B or B2C software companies that I invested very early when they were three guys and a dog. And now they're worth quite a bit of money. And I think some of the things I learned by making mistakes as a CEO helped me identify really breakout companies early. So let's get to the exciting part that everybody came here to, which is how did Martin lose a giant pile of money and what did he learn from it? I have two examples as a CEO. The first one was Laudai Technologies, which was the first company I started as a CEO. When I left college, I went to Accenture. I was there for five years and I was at Microsoft for six years. I left Microsoft in 97 and started Laudai. Laudai was the first service provider to start streaming media services. It was at the beginning of the of streaming media and basically all the media I mean, Microsoft had just launched its Windows media player. RealNetworks was on version 1.0. You still had to buy a video card and audio card separate on your PC. But what I saw was this giant library of media on tapes and CDs and stuff like that that needed to get converted into digital media formats in order to be accessible on computers and mobile devices. Hadn't even been out there yet. So I said, I'm going to start a company writing software and scaling up, scaling up infrastructure to do that. We raised our first round $5 million on a $10 million pre money valuation. That was a series A in 1997. And basically three years later, we went public in March of 2000. That's incredibly quick. That's from zero to 350 employees, $10 million of revenue in three years. And we were in fact, we went public on March 17th of 2000. It was in fact the last company to go public in the dot com boom because the peak of The NASDAQ was March 21st. And the initial price of the IPO was $16. But the first trade was at $45 because we had a crapload of retail demand, about 20 times over subscribed book in retail. So you know, at the end of the IPO day, I was CEO of a company with a $1.4 billion valuation and only $10 million of revenue. That was the beauty of back then, the dot com boom. But as you can see on the stock price here, basically seven months later, the stock had gone down to under $4 a share and it was worth about $100 million. So it had lost 95 in nine months. At the IPO, I owned just over 40% of the company. So that's the first time I lost $500 million. The second thing as a CEO where I lost some money was in a company called Upgrade Labs. So I was basically retired in 2015 and 16. But a friend of mine was running a company called Bulletproof Media. And he's a longevity guy, Dave Ashbray. And he had this idea for a next generation health and fitness facility that he wanted to spin out. And he said, hey Martin, you're not doing anything. Would you like to come and help me spin this out? And I said, sure, sounds like fun. I like health and fitness. So we started the company in 2017, raised a little bit of money, raised two rounds. In fact, I got the company up to $6 million in revenue. In 2019, we passed on an offer for $100 million to buy the company, basically three months later, in March of 2020, Covid came and we were running physical retail facilities and we had a conference which was a 2,500 person conference in Beverly Hills. They canceled that conference and closed our retail facilities. So we went from 6, $700,000 a month of revenue to zero in two days. So as a CEO, I basically had to lay off 95% of the employees, including myself and Turtle, the company, get a PPP loan, try to keep it going. My equity in that company was basically wiped out and I lost another $20 million in that company. The company was restarted in 2022. It's growing well and it's profitable. And I'll explain in what I learned some of the things that I did different in Upgrade Labs, reset versus the other one. So what did I learn in, you know, taking big losses like that As a CEO? The first lesson was if you're in a bubble, it's better to be in it than out of it. The fact that we were the last company to go public in the dot com boom turned out to be lucky and have very good timing. You know, if we had been literally four days later, the company likely would not have gone public. But the company was able to go public, raise $100 million and had money to withstand and last until it was eventually sold in 2006. So it had plenty of money. What I tell people now is, you know, know where you are in the cycle. You know, if you're building a AI company or if you were building a crypto company five years ago you were at the top of the cycle, now you're at the bottom of the cycle. If you're building an AI company, it can feel like everything's up and to the right, but you're basically at the beginning of a hype cycle in AI. So where whenever you start your company, know where you are in the cycle and hopeful and know that the cycles are going to end and hopefully you can get in and out at the right time in the cycle. A second major lesson from losing that amount of money is that your balance sheet is not your income statement. I had a friend whose company went public in the dot com boom. It was a E commerce company in New York City. He had a hundred million dollar position in this newly public company and he immediately went to Miami, took out a $20 million mortgage loan against his stock and bought a mansion and started spending like a drunken sailor. His stock did a similar thing like mine, went down 95%, he got a margin call and he lost everything. When I Had that amount of balance sheet on my income, on my balance sheet. I didn't change my life. I didn't buy a new house, I didn't buy a new car. I didn't do anything. And when you're the CEO of a public company, you also have restrictions on trading windows and stuff like that. So one of the mistakes I see a lot of entrepreneurs think is make is believing that the value of their company, either as valued in the private markets or even in the public markets, is in fact cash that you can spend. It's. It's not. The third major lesson is to diversify a concentrated position as soon as you can. One of the most valuable things I did in the Laudai IPO is that they had these things called exchange traded funds. And as a CEO, I was unable to sell my shares, but I could donate them to a fund. So I gave $3 million of shares to a fund and lots of other CEOs did. And we basically exchanged that for a basket of all of the other CEO shares and senior manager shares. And so they help. The company held that basket for seven years, sold what was left. And it turns out that that basket of shares decreased in value much less than my individual stock. So I got diversification without having to sell my shares. The other thing where I learned that lesson is when I left Microsoft and before I start. When I started, after I started Loudi, when it went public, I still had a pretty significant share of Microsoft stock. And one of my friends said, hey, you should probably sell that Microsoft stock just because now you have this huge piece of Loudi stock and you need to start diversifying these large positions. I ended up selling all of my Microsoft stock at what turned out to be the highest point on Microsoft and diversifying that. So I'm a big fan if you have a concentrated position of diversifying as soon as you can. Another lesson was when the macros fall apart, turtle as fast as you can. One of the mistakes we made at Laudai is that we had just gone public and then the stock market went to shit and we saw the stock starting to fall apart. Every stock around us was. Every Internet Stock was down 90, 95% within nine months. That had nothing to do with the quality of our business, which was actually pretty good. And frankly, unfortunately in that company, because we had $120 million on our balance sheet, we kept our burn rate quite high and kept trying to grow into what was a incredibly tough and hard market. We should have pulled back the reins on expenses much faster. And I learned that at loud I. So when it happened to Upgrade Labs, we had a decent cash balance and basically within a week of being closed by Covid, I made the hard decision to fire 95% of our people and just go on to maintenance only mode because we had no idea how long the pandemic was going to last. It turned out to be a year and a half before they could reopen. And at the time, some people were thinking it was a month, but nobody knew. So if you have a macroeconomic thing that hits you in the face and you have some cash in the bank, don't try to grow through it or pivot or whatever, conserve your cash until you know that things have turned around. And that's why Upgrade Labs was able to survive the pandemic, restart the company, and is now a profitable and growing company. So that lesson was learned on Laudai and applied at Upgrade Labs. The other lesson I learned is you only lose if you stop playing. It could have been very easy for me after Laudai to just say, oh, well, you know, that didn't work. I actually ended up with enough money to not have to work, so I could have just stopped and retired. But the reality is I got really bored playing golf. And, you know, the real loss would have been if I didn't try to start anything else or didn't try to work with other startups. The only way to lose a game, in my opinion, is to not play the game anymore. Another good lesson for me was to take more risks early in your career. When I started Laudai, I was in my 30s and in your 30s, if you swing hard for the fences and you miss, you still have plenty of time to get a job at Big Tech or go do something else. That's the time when you should take risk, and you should should take big risks because you still probably don't have responsibilities of a family and things like that. So I encourage young people to take more risks than they think. A lot of young. I have a daughter who's going in the fall to Georgetown Medical, and I'm excited. She's smarter than me, so I'm happy with that. But I am encouraging her. Rather than going straight into a corporate medical job or go into a standard, you know, big hospital practice, maybe take a stint for two years at a biotech company that could potentially go public and make you a lot of money, you can do that right out of medical school early in your career before you've invested a long time in trying to build a private practice. It's a lot Harder to do that 20 years later. The other lesson I had is it's better to be too early than too late and don't try to copy other people's business model. Another company that I started, which I didn't talk about, I started a company called Tipper, which was a white label version of Groupon. That company didn't work out because I was basically copying Groupon and selling it as a white label service. Laudai did work out because I was the first company doing that and the biggest company in the space. Upgrade Labs was the first and only company doing that. The kind of retail that it was doing. It's much better to be innovative, even if people think your idea is crazy than it is try to copy what somebody else has done with better economics. And the last lesson, what I learned in those things is focus on what's in your control. I had no control at LAI over the fact that the macroeconomic environment, that the dot com bubble burst and that people went from risk on to risk off very quickly and basically lost interest in all of the Internet stocks. That had nothing to do with the years of work I had put into building Laudai. Same thing about Upgrade Labs. We had built a good business. And then Covid comes along. It's something that's out of your control. Rather than complaining about the macro environment, things outside your control, doing something which affects you, just do what you is under your control. So for example, at Upgrade Labs, you know, I made the hard decision to fire the employees and fire myself and preserve the cash so that it could make it through the process. So those are some things I learned from making mistakes as CEO. But I'd like to talk for just like five minutes about things I think that are more positive, you know, why starting a company today is great and why I'm still more optimistic today than ever. Just a couple slides. This one is Moore's Law, which I'm sure you've all heard about. Moore's. You know, when I was running Laudai in the late 90s and early 2000, Moore's Law was going along. And since then it's continued to go along. If you're building something in software which is dependent on, you know, Moore's Law, you know, that's going to keep going and you might be too early. In fact, when I started Laudai Technologies, one of the things we had to do is buy a lot of hard disk storage to store the masters of these digital files. And we were paying when I started Laudai, $100,000 a terabyte and. But the reason I was willing to pay that is that I knew that Moore's Law was going to lower that cost over time. Now, we didn't last this long, but if we were starting Lai today, you're paying basically $100 a terabyte. It would be a lot better to have built Laudai today because the cost of your infrastructure has been declining based on Moore's Law. But the Moore's Law, I think is going to keep going. And you know, there are many business models that get better over time, so it's better to start them now, even if they're slightly not economic today. Because if Moore's Law is going to improve your economics over time. The second thing is that, you know, the historical cost of memory and storage. So it's not just CPU power that Moore's Law applies to, but this is what I'm talking about. The cost of terabytes, basically the cost of all the infrastructure to start a tech company, is going down over time and has continued to go down pretty dramatically. But it's. Even if you're not building a software company, it's not just software technologies that are going down. If you look in other categories, the cost of building a wind turbine, the cost of photovoltaics, the cost of aluminum, basically the cost of all raw materials that you might want to use, need to start any company has been going down over the last 20 or 30 years, meaning lots of businesses that might not have been economic even a couple years ago are more economic today. The other thing that's happening is that technology adoption rates are accelerating. So, you know, one of the graphs I look at a lot is this is the time to 100 million users for different major technologies that have come through. It took basically sort of, you know, 900. I don't know what that is, whether that's days or weeks or months or something, but a long time to get to, you know, for telephones to get adopted. It took chat GPT two months to get to 100 million users. What we've seen is every five years, it's the time to get to scale has become compressed, which is great if you have any idea for a company that you would want to start like today, because you can get to people faster. The other thing is if you take all those trends and put them into a macro number, the cost to start any kind of Internet company has gone down quite significantly. When I started, the cost in 2000 to start any kind of Internet company was approximately $5 million. I raised $5 million my first round in 97 to start Loudeye Technologies, that same company today or well in 2015 would have been $5,000. Today it might be a thousand dollars. So you know the. And all of these trends have come together in, in this graph which shows you, you know how many unicorns that have been created over time. And if you look back, this only goes to 2011, there were only a few unicorns every year started and starting in 2014, the pace accelerated. In 2015, it got denser. And if this slide went into 2022, it would have been just jam packed in 21 and 22. I think there were over a thousand unicorns created in 21 and 22. And what you see when you look across time like that is that there are more very valuable companies being created faster and at a higher rate per year than ever before. And I don't think that trend is going to change. It's only going to get better. Which is why I'm super excited to support entrepreneurs today who are starting today because I think it's a great time to start a company. So to summarize how I think losing can be winning, the three most important things I learned were even if you strike out, you can't hit a ball that you don't swing at. So people talk about being in the arena, you've got to try to hit that fastball. The other thing is lessons compound over time. I think as I mentioned, some of the things I learned that went wrong at Laudai, I applied at Upgrade Labs and had a better outcome. So know that that'll happen and you know, you can be really helpful to the next generation if you've survived like I'm hopefully helping to be. So that's all I had in terms of presentation. If you're an entrepreneur, I think the time is now. Just do it. If anybody has any questions, that's probably enough of me talking. Let's take some questions. So let's see in chat. Oh, sorry, I hear all this. No audio. You can either put a question in the chat or you can raise your hand. But if anybody has any questions about the entrepreneurial journey or something, I'd love to hear.
Yes.
Hey, Clement.
Hey, Martin. Hope you're doing well, man. Appreciate all the. What advice do you give? Not technical. Can you hear me still?
Yeah. You broke up for just a second there.
Perfect. My question was, what advice do you give non technical founders? People looking to solve problems. But you know, cost of engineering is pretty expensive. So you know, what are the best avenues? What advice do you give in regards to that?
Well, you know I think the best startup is a combination of two people. Sometimes it's two different people, sometimes the same person. One person needs to really understand the business problem and the customer. So I don't know what you know if you're non technical, hopefully if you're non technical you really understand the business problem. You know the customers, you know the pain point, you've lived the problem. You, you know, you know you're in a customer associations where you can find your initial customers. That's like 50% of the startup is what's the customer problem? Who are the customers? How do I reach them? And then the second part is technical and there's been studies done frankly by other bigger venture capital firms as to whether the CEO founder is technical or whether they're business. And there's frankly no difference in success rate and unicorn potential between a business founder or a technical founder. I know it's kind of a meme in Silicon Valley that you got to be this tech nerd like a, you know, both wear both hats, superman like Elon Musk. That's not my experience. I think you can be either a really good business founder or a technical founder or if you know the unicorn, the, the, the super rare thing is a person that can do both like Elon Musk or you know, Bezos or somebody like that. But if you're a non technical founder, say try to understand whatever the business problem is really, really deeply. And then there are places you can go to meet technical founders if you have to build something. YC has a matching community, there are online communities you can go to local meetups, hackathons and just pitch your, you know, business problem to other technical people and see. But in order to start a company, if, if it's going to be a technology company, you do have to have a technical co founder. I have found it to not be very successful. If a business person without a technical founder tries to start a software company using outsourced developers or something, that's not a very successful way to start it. So I would say if you're a business non technical founder, understand the customer and the business problem super, super deeply and then try to attract a technical founder.
Terrific. One follow up question isn't, isn't, isn't followed up on the prior question. But in terms of breaking into VC pre seed early stage founders, if you haven't had the type of experience you have, what advice would you give to someone looking to, to do that?
I would say you should Go apply to, you know, different accelerators, techstars and all of that stuff. There is a thread on my Twitter feed where I list like five different forms of different VCs or you know, like OpenVC and some other ones where you can apply to precede funding and you'll get some interviews with some VCs. I would say just pitch your idea to some VCs and start to get feedback. I don't know that you would get investment right away, but the first thing you need to do is get feedback on your idea. And that just means you need to pitch your idea to anyone who will listen.
Just to clarify, I apologize, Martin. As an investor looking to do pre seed investments, if you don't, the best.
Way to start that I would say would be to join AngelList and start investing in syndicates on AngelList. Because then you could go to a VC later and say, look as an angel and you don't have to write big checks. The minimum check on angelist is like $1,000. If you wrote, you know, $25,000 checks, but you showed that you had good selection and picking criteria and you created decent return even though it's a small amount of money, people be like, oh, that guy has a decent screening, right? And you would get a giant amount of deal flow on Angellist. Just join some syndicates. Join my syndicate. Angellist has thousands of syndicates. You'll get more companies than you know what to invest in. On Angellist, I would start as an angel investor writing small checks, even thousand dollars checks.
Thank you.
All right, thank you. Hey, Brian.
Hey, Martin. Martin. I spent a good chunk of the day today talking to a founder of a company I'm invested in, have worked with in a while, and he is agonizing over the reality that he is facing a down round.
Okay.
And you know, he's, he's concerned about the reactions of some of the investors he's got. My message to him was that it's a tough environment and he needs the infusion of capital to get through the next big hurdle for his organization. But I'm wondering from your perspective and your experience, what type of things you consider when you're thinking about companies that you're involved with facing down rounds or companies that you've been a part of.
Well, what I have seen be the biggest problem there. A down round is typically, is usually something that is outside the company's control. Right. Like you might have raised in 2021 at a high valuation. You think that that's the thing worth. But listen valuations are down 50, 80% since then. You're in a different market. The macro environment has changed around you. And so what gets a lot of CEOs tilted is they're like, yeah, but my business is better and I've been working really hard and I should be worth more. But the reality is the macro environment changed. It's like when Laudai went public, you know, the public market said, hey, your company with $10 million in revenue is worth $1.4 billion. I knew that was stupid, but you know, it felt good. But I mean, I knew that wasn't the right valuation. You know What I tell CEOs in, in that case? So he's, he's having a mental, you know, problem with the fact that the macro environment changed around him, yet he still worked hard. I, I see that in my portfolio a lot. And what I tell CEOs in that case is, is like, listen, you have only one job as CEO. One job. Don't run out of money. That's your job. In that job you have only three tools. Sell something, cut expenses or raise capital. If you are facing, if you are three months, six months from running out of money, you know, you only have those three tools and that's all you have. And you may not like that. They may be hard cutting people. Firing 95% of my staff at Upgrade Labs was hard, but I had no choice because I could have continued to burn the capital that was in the bank, but that would have been a short term thing too, right? I couldn't sell anything because my facilities were closed. So in his case, I think you just need to say, I don't know how much Runway they have, but the longer he puts off that decision, it just makes it harder. I understand the cognitive conflict, but your number one job is to keep the company alive. That's if investors are telling you they need to reprice it because of the macro environment. You know, my number one, one of my number one investments is a company called Catalyst Fitness. I met the CEO about eight years ago and he was raising. It's an at home fitness product. It's electromuscular stimulation suit. Kind of like Peloton but for strength training. Anyway, he's like, I'm building this suit and I'm going to build retail outlets and I'm going to do a studio concept. I'm going to compete with Orange Theory. It's going to be the new studio fitness thing. And I'm like, the studio business, can you sell this to consumers? I don't like retail I don't want to do it. He goes, no, no, no. Investors like it, blah, blah, blah. They're throwing money at me. I'm like, oh, fine, go do that. He raised $32 million. He got shut down by Covid. All his facilities got closed. And so he comes back to me and he says, oh, well, whoops, that didn't work out. And I go, okay, we have to recap the company. I don't want to recap it. My investors, blah, blah, blah, blah, blah. I'm like, okay, well then you're dead in like six months because you have no money. And it took him a few weeks, but he's like, I'd rather live. And I'm like, okay, I will lead your recapitalization of the company with a million dollar check at a $10 million valuation. He didn't like it, but his option was death. Yeah, so with CEOs like that, I usually just encourage them to decide, do you want to live or do you want to die? Yeah, yeah.
He's sleeping on it tonight, so I, I, I'll be talking to him first thing in the morning. So let's, I appreciate your thoughts on that.
Okay. It is a tough situation that a lot more people are going to have to have. And frankly, the, the more successful companies in my portfolio are the ones who, whose CEOs were smart enough to take the medicine early. Every CEO who has put that decision off and tried to market their way out of it or spend, you know, grow revenue or maybe a new investor, you know, has not ended well. The ones that have taken the medicine, taken more dilution. Okay. But bought the company, you know, 12 or 18 months, are the ones that are doing the best. In my experience, taking the medicine early, as painful as it is, is the right thing to do.
That's great.
Perfect.
Thanks very much.
All right, thank you. Brian. Hi, John. Hi.
I just.
Oh, cool. Can you hear me?
I can, yeah.
Oh, excellent. I'm, my name is John Penniman. I'm with the Opera House. We're a new company that just started up and I'm in Eugene, Oregon. I'm in a small town. We don't have any, any sort of connections here, but we do know that we need to get connections really, to get into the game, talking precede. Yeah, Eugene.
Oh, I know.
Okay.
Yeah, yeah. There are VCs in Portland or in Bend. You should talk to Robert Peace at Cascade Fund.
Okay. That, that's kind of what the question really comes from, is from the first person who asked the question too was just when, when we're just starting out, we're not in the game. It's one of those things that we know. It's easy when you know people. It's kind of like that, that saying the easiest way to make a million dollars is to have a million dollars.
Yeah.
And you know, we're trying to reaching out to a lot of like the hustle funds and venture capitalists and stuff. Just trying to get even a little bit of a communication going. What do you recommend?
There's lots of people online you can do, but the first thing you should do is to go to Portland or bend to one of those angel groups. You know, look up who runs the angel group, try to, you know, go to one of their meetings and, and meet some of the local VCs, because even hustle Fund or me, I would be like. Like, that's the first thing I ask you. Did you talk to Robert Peace and Ben? Okay, if you haven't talked to Robert Peace and you're in Eugene, I'll be like, what's wrong with you? Right.
Get my butt over there. Okay, I got it.
Why are you talking to me before you talk to the local people? So find the. I don't know if There are any VCs in Eugene, but I'm sure there's an angel group in Eugene that meets and you should figure out who runs it and talk to them and see what their process is and try to pitch them. And then, you know, figure out the two or three other VCs in Oregon and you should talk to all the Oregon guys first. They should be pretty easy to get to.
Okay, very good. Thank you. I will do that. I appreciate it.
Take care. Hi, am I in?
It's Eamon. Hey, how you doing?
Sorry.
All good, all good, all good. Can you hear me clearly?
I can. Awesome.
Hey, a few questions. I've been following you on Twitter for a while. Agree with some stuff, you post some stuff. I don't, but that's okay.
I don't expect you to agree with all of it.
Awesome. What I wanted to know is like in today, I know you had like a chart right now of like what it's like significantly less than what we were raising in the early 2000s. What do you kind of see these AI SaaS, startups one should be raising today? Like, again, this is not like deep tech type stuff, but you know, you had an average about 5 million today. Are you seeing about like in the pre seed raising about like a million, million and a half?
Yeah. So I I did a post on my blog which might be worth reading. Like how I define the different stages, the angel versus the Pre seed versus the seed versus the A. You know, when I raised my first round in 97, I raised 5 on 10, which was an A. When I wrote the first check into DocuSign as an investor, we gave them 4 on 7, which was an A. But I mean right now the A is like a $20 million round later, like we've got these three other rounds before. And so, you know, occasionally in the media you'll see people raising big seed rounds, but those are typically second, third time founders, you know, with a great team around them and they raise 10 or $20 million, you know, at a $50 million valuation. But the typical thing where first or second time founders, you know, without a bunch of pedigree and stuff, is that you would raise maybe 4 or $500,000 in an angel round to friends and family round to get your MVP done. And I'm just talking about B2B software and I think most AI application companies are B2B software, even if they call themselves AI. And then the pre seed, you would raise between 1 to 2 million dollars to basically go from, you know, 20, $30,000 ARR to $500,000 of ARR. I'm not seeing seed type companies with $100 million or more funds getting interested in seed rounds until $500,000 of ARR. And the seed rounds that I'm seeing are sort of 4 to 7 million dollars, you know, at a 20ish valuation. And what the seed guys are trying to do is get you to $2 million of ARR, which is where the Series A's are happening today. If you asked me that, you know, a year and a half ago, I would have cut all those numbers in half in terms of traction. But you used to be able to get an A done if you had a million dollars ARR. Today it's 1 million, it's 2 million. You used to be able to get a Series B done if you had $5 million ARR, now it's $10 million of ARR. So what's happened in this risk off environment is that the later stage guys have raised their traction metrics, which means you have to raise a little more early. But precede when some people say, some people define pre seed as not having an mvp, just having an idea. I personally consider the idea phase prior to pre seed because the way I define pre seed is you've got an MVP in the marketplace for at least Three months, you got a little bit of customer traction and the reason it's okay to raise a little bit more is that you've got some customer feedback and you understand what you have to really build and how to attract more customers. When you're building that mvp, you can build whatever you want, but until you've got customers on it for two or three months, you don't know what else you have to build. So you don't know how big your pre seed has to be. Right. And if you can't build an MVP for under $500,000 with today's tools, you know you should be shot. So or, or you're building something that's really deep tech that requires it, right?
So let me ask you this, in that case, how many customers, like if you were going to tell a founder today like hey, you're going to start now talking to VCs for a pre seed round, how much in MRR ARR should somebody be having before starting to engage that it's worthwhile for both parties?
So I just did that. I actually just, even though I say I'm precede and I don't write angel rounds, I just gave a really, really smart two person team with an idea some angel money to get their MVP done. And here's what I told them. I said you need to get in the next three months these three things done. You need to complete your MVP. You need to have five to 10 signed POCs, proof of concepts with people. And those proof of concepts you have to run for at least three months so you've got some, some time with those customers and then out of that customer and you have to, as you're doing those POCs, you have to build a pipeline, a wait list of another 20 or 30 customers and don't let them on yet because you're running your POCs. If and, and those POCs should be paid and they should generate approximately five or ten thousand dollars a month of revenue of POC revenue. If you have that, you can raise a million and a half dollar pre seed because you've got enough of a pipeline POC engagement and you know, a 30, 40% product to do a demo on. That's when you should talk to professional pre seed investors like me.
Sounds good.
All right man, I'll see you on Twitter.
All right, thank you. Hi. Hi Martin. Hey Matthew, how are you? How's Jim? I'm doing well, very well. How are you? I'm good, thank you.
Great, great.
Thank you for doing this. Very informative. Just a Quick question. What advice would you give to founders about understanding or what signals should they be looking out for, aside from running out of cash, to determine whether to keep pushing ahead or to pull the plug? I'm a big fan of the, of the superhuman guys 40% customer can't live without it Product market fit survey. I'm not a big fan of Net Promoter Score. Net Promoter Score is just, you know, asking customers, you know, would you refer it to a friend? But if you Googled, you know, the Superhuman Guys product market Fit survey, he asked a question to his customers, you know, in cohorts, like weekly cohorts or two weekly batches, and he says, would, how would you be really upset if you couldn't use my product? Would you be a little bit upset, a lot upset, or would it not matter to you? And what he's looking for is 40% of his customers to say they would be really upset. It would like really blow their mind if they couldn't use the product anymore. Now you want to start measuring that. And if you are at, you know, 5%, say they couldn't live without it, you don't have product market fit. And the question of should you keep going? Like, if you, if the things that you're building, the extra features and things that you're doing are not moving that number up and to the right, if it's not going from 5 to 7 to 10 to 12, if you're not progressing closer to product market Fit in in a way where you understand and have a good customer feedback loop that you think you can iteratively get to 40%, then I think you should consider whether you need to pivot into something else that can get to 40%. Right. I think the time to decide to stop or to pivot is when you don't know the next thing to do to get the number to keep going up. If you flatline, you know, at 15% of your customers love your product and everybody else thinks it's meh. You do not have product market fit and you're never going to get there. That's very helpful. Thank you. Okay, there are a couple of questions in the chat here. What advice do you give founders raising pre seed in this market? Should they focus more on fundraising more and gaining customers? My advice is that, well, first of all, you know, as a CEO, like I mentioned the last guy, you have one job, don't run out of money. So, you know, if you're about to run out of money, you know, you have to do fundraising. The problem is that the bar for every type of investor angels pre seed seed investors is higher than ever. So it's not just getting gaining more customers, it's getting, you know, the metrics correct. Like the show showing progression towards product market fit or if you're later like in the seed round. I just posted something on Twitter from David Sachs which is talking about burn multiple. And the reason you want to track burn multiple, a great burn multiple is one or less which means you add more ARR period per year than you burnt in the year early. You're going to be burning a lot more money than you're adding in revenue. But what you want to show is that over time those ratios are getting better. If you tracked your burn multiple every month on a 12 month trailing basis and it was getting better every month, what you've got to have is a story. If you're going to raise money, you have to have a story to investors as to why you're on a path towards a profitable product market fit. You know, product that customers love and you know, showing things like burn multiple compressing over time, product market fit score going up. Those are the things that are going to convince investors to invest in you. If it's just an idea with no validation, no traction metrics going in the right direction, it's really hard to raise money right now. Professional investors like me are looking for traction metrics of any sort going in the right direction. And it's not just revenue. We're going to ask you things like your retention and your daily active users and your churn rate. You know, I have, I had one company that had, you know, was adding customers very quickly, very effectively with a good return return on ad spend but they had a 10% monthly churn rate. What that means is every 10 months they had to reboot their 100% of their customer base. This is bad. So what I'd say is build enough of a product and an engine that's going in the right direction that you attract investors. And oh, here's another guy. Max, why don't you ask a question?
Yeah. Awesome. Yeah, big fan. Been following on Twitter for a while. Thank you. So yeah, you're welcome. We raised our first money like we came venture back to about a year ago and we're doing our next round August, September. As we're getting closer to that, I've just been like thinking about the round more we've been raising to hit our seed metrics and then have 18 months of Runway and some people have been telling me to put more of a Buffer in with the current market. Like get to like 24 months of Runway. I want to just hear your take on the investor side of what you're looking for for extra room on those rounds. Just with all the current market conditions.
The number one, we basically switched about a year and a half ago from a risk on to a risk off environment. You know, a year and a half ago I was happy investing in a pre seed round that gave 12 months of Runway because you could reliably raise every six months. I'm not doing that today. I'm investing in pre seed rounds that are 18 to 24 months of Runway. I think that seed rounds should be at least 18, preferably 24, maybe even, you know, like what's the next one? 30. Because the average. If you look at Carta data, you can follow Peter what's his name on Twitter. He posts a lot of this data showing time between rounds and what's happened is the time between the precede and the seed and between the seed and the A has basically been going up every quarter for the last six quarters and I think it'll continue to go up for the next couple quarters. So I don't know what your ARR traction rates are, but the number one risk in any financing today is follow on financing risk. And the numbers that I just gave you are, you know, true today. You know, you can get a seed done at around $500,000 of ARR and an A done around $2,000,000 ARR. What I would say is that I would want you to have at least, you know, 50% more money than you think you need to meet your next milestone. Let's say you're at $500,000 ARR and you think you need, you know, $4 million to get to $2 million of ARR. Rather than raising a 4 million dollar seed, I would raise a 6 million dollar seed because you have 50% buffer. Right?
Yeah. No, that totally makes sense. I think like one of the things that we're looking at besides just the buffer is like some of the larger strategic things. We're in the prop tech space and like some of the bigger funds with access to all the properties are usually later stage or larger checks. So it's like I don't want to take on too much money now for some of that. Like I would, I want to leave decent room for them. But I also want to make sure that, you know, we're able to survive any, any unexpected bumps.
So yeah, I mean the, the one of the mistakes you can make in this environment is being pennywise and pound foolish. When I hear CEO saying I'm optimizing for dilution in my seed round or my pre seed round, I get really concerned because you should optimize for survival in today's environment.
Yeah, no, that totally makes sense. I think, like, I'm not as worried about dilution, just more like strategics. Like our first round was a lot of great tech investors like, like Eric Reese and like some other like big people like that, but like just customer. Especially in the the real estate space. Our sales cycle's been slower than I would like. So trying to bring on more people with like direct access to property ownership.
Yeah, I think that's really good. And you know, I think you should bring those guys. Are you saying that they would want to wait for a larger round or are you saying you could bring them in as angels?
Yeah, like I want to bring some of them in earlier. Just like one of them. It's Camber Creek, they're out of New York. I think we have a good chance to bring them in now. They're like, we're looking to come in a little earlier. Like usually they don't invest until 2 million ARR, which we're not at. Right. So I'm trying to figure out how to navigate some of that.
Hey, if, if, if a series A guy wants to invest in your seed, even at a small check, I would say let them in because then you're at the front door. You know, when the A does come around, find a way to let them in. Even if I appreciate it more dilution than you would like.
Yeah, sounds good.
Thank you.
I appreciate it.
All right, well, I think we're coming to the end. I appreciate everybody spending time with me. Hopefully it's been helpful. I'll post a summary on my blog and keep going and building amazing things. If you're building something in B2B software, I would love to, to hear from you and hopefully I can help you build whatever it is you're building. Take care everybody and I'll see you on Twitter.
More from Martin

Product and User Experience, how to make a cure and not a vitamin with Greg Raiz