What is Jaguar doing? - Episode 083
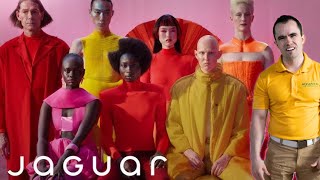
Mike and Lee break down Jaguar's chaotic rebrand that racked up 31 million views and sparked backlash for abandoning the 102-year-old brand's heritage. They also cover why small businesses should skip equity grants until they hit around $10M revenue, focusing on profit-sharing instead to avoid dilution and legal headaches.
Chapters
I've never said this anywhere else, so.
I know.
Welcome back. Another episode the C Suite Unfiltered with Mike Andes. How are we doing today, sir?
Good, man. How you doing?
I'm doing great. We just talked for 30 minutes and now we're, now we're starting the pod, but we are going to start hot and heavy. All right. And I just sent you a link to your phone. If you can watch it. I will put this up on the screen. As of time of recording Yesterday, this is November 19th, Jaguar deleted all of their tweets, all of their social media posts, and now have a new direction for the brand. And it is copy nothing. Would you please watch the video and then we'll talk.
This is Jaguar, like the car company.
This is the car company.
Oh, brother. Wow. Have they got a lot of backlash over this? I hope so.
So this is. I sent you the Twitter post because that's where I get most of my news. I, I like X, I like Twitter. The number one reply was from @ Elon Musk and it was, are you a car company? Question mark. So they are getting roasted online especially, you know, Jaguar is a British brand and there are a lot of purist motor heads over there in England, the United Kingdom, and they are getting a ton of backlash. Like, this is a historic. It's a. I just Google it to verify it's 102 year old British brand. It's 102 years old. And they're like, you're just throwing out all the heritage, everything that made Jaguar, Jaguar with whatever this is. So what are your initial thoughts when you see a legacy brand like Jaguar, delete all their social media and then post this.
Video. Like, well, we're talking about it. So again, they are getting some publicity, you know, Elon Musk talking about they had 31 million views on that video. So someone's getting paid.
Now in terms of the brand. Like, also keep in mind, like, I don't know, because Jaguar is a piece of a larger company, so they could be very well bleeding so much cash. They're like, hey, either we shut this thing down or we completely reset it and go a completely different direction. So that might be the strategy. Like, I always keep in mind, like, people in these, in these rooms are really pretty smart people like this. They didn't just happen to become the CEO and the executives of these companies, right? And so they usually have a strategy. Whether it's the right one is, is, you know, debatable, but I think it's a matter of, like, if they are losing cash. If their brand is becoming obsolete, if their sales declining year over year, there's a very good chance like we are resetting and we know we're getting massive backlash, but we're going to be able to target this demographic that is underserved. So if everyone else is going to go after trucks and like the, the, the brawn of the car industry, we're going to go a different direction. It could work if you're making money. Hey, like, look, I don't agree with your ad or like how you portray things, but there's a niche that they might be trying to serve and the, the last ditch effort to save the brand is going a completely different direction. Just, just as, just as a devil's.
Advocate. Yeah, totally. So I did look it up because that's obviously what you want to see. You know, you don't want to make broad strokes assumptions. So Jaguar is a subsidiary brand of Tata Motors, which is an Indian based multinational automotive company. They also own Land Rover and then the Daewoo, which is more of an Asian market brand. And of course, you know, people were like, look at their stock price. Yes, their stock price has gone down since this video released. A direct correlation? Probably not. But you know, everybody online likes to say that it is. I didn't see any like drastic data showing huge negative trends for Jaguar or Tata Motors in terms of sales and things of that nature. It just came across as shocking is what a lot of people were responding to, at least on Twitter on X. They were very confused. They were like, this is a legacy brand. Why would you do this? You're throwing everything away. You know, you have the comments, you go woke, go broke and I'm like, I don't really get woke from that. I get artistic pseudo. Apple had. That doesn't make sense for a legacy brand like Jaguar. When I think Jaguar as a consumer, I think elegance, class, you know, hottie toddy British people and their fancy drop tops. So it threw me off as a.
Consumer. Yeah, like if you look at their stock price over the past six months, technically it's come down like 40% in the past three to four months.
So like their, their PE ratio is only 6, 6.85 so it can almost guarantee that they aren't growing.
So it's just a matter of like, are they trying to completely refresh everything and are they putting Jaguar as the martyr?
So if they're like, hey, let's try with one of our smaller brands that's dying already makes up a few percentage of our points of our revenue. Let's take in a completely different direction, see what happens. This is a marketing expense.
And they get, they're getting publicity over.
It.
There's. There's a subset of people that agree with that.
Ad. So, yeah, yeah, I'm just, I'm scrolling through the replies right now, just to give you a couple. Someone, you know, someone else said, are you guys the car company or something else? Their response from the Jaguar account, soon you'll see things our way. Someone said, this is surely a joke. And Jaguar replied, a pivotal moment. And then someone said, awful, awful ad. Jaguar said, quite the opposite. This is a renaissance. So they're clearly, like, leaning into it excessively to see what, what's going to come of.
It. Yeah, it was interesting. We'll.
See. So I, I just thought to throw it out there. But I am, I am a firm believer there's no such thing as bad publicity. Right? We are talking about it. Other people are talking about it. Elon Musk, like you said, is talking about it. I, I really, this thing, the idea that there's no bad publicity really set in. Go down Lee's rabbit trail. Here is in college, there was one kid that I went to college with that everybody knew his name. Why? Because randomly he would just wear a T. Our school mascot was not the Tigers. Everyone's probably wear a tiger suit. Just. That was, that was just his thing. Everyone knew his name. I was like, no such thing as bad publicity. Everybody knows my guy Joshua, and that, that.
Is. Yeah. But there's not, there's nothing bad about a tiger suit. That's the thing. This, this is very.
Divisive. So, yeah, what would you say to, like, the purists of Jaguar that are, like, see it as this legacy, heritage, you know, brand? What would you say to them? They're like, I'm jumping ship, or like major shareholders or whatever. What would you say to them if you were kind of team, I like this ad. This is the direction we have to move.
In. Vote with your feet.
Dude.
Yeah. Go buy another.
Car. Yeah, yeah, fair enough. What would you say, like, what are your general thoughts kind of zooming out on, like, these harsh kind of rebrands? When companies have to do them, is it strictly because they have hit a wall, they have lost sales, they need to turn the business around? Obviously you've done that with business turnarounds. Small business is different. Right. Most small businesses aren't known enough in their market to do massive rebrands. But what are your general thoughts when businesses come to these pivotal moments and do these large.
Rebrands. Yeah, like, I think it's just a matter of, like you, when you have 102 year old brand, you have legacy as a trademark of the brand and a huge asset. Like if you were to sell Jaguar, large of it, large amount of their value would come from the brand awareness. And so if you're going to tweak that, you're, you are playing with the, the fundamental building blocks of the company. So it's not like they're coming out and changing the design of their cars. Even though that might happen. They could have, they could have done this, done change the cars without doing what they're doing right now and not much would have changed. Like, no one would be talking about it. Like the actual products changing is not what's happening, it's the branding. And I think you got to be careful of in this case is people have bought the brand for so long and they own Jaguars. And so if the value of those Jaguars is massively drops over the course of the next two to three years because of this, well, now you've tarnished the brand because a lot of these legacy.
Carmakers, like, their brand is you buy this car, it's a collectible, it goes up in value over the course of time. You show it off to people and everyone loves them. And so if you tarnish that, no one wants to keep them, the value of them goes down, the collectibles immediately go down in value. And yeah, you're playing, you're playing with the fundamental building blocks, but you're not changing the product, you are changing the brand. And that only matters in a company that's been around for a long time that has a legacy brand. Like, if you have a company that's like four or five years old and like we're changing our brands, like, okay, cool, what to do? What's your product doing? In this case, we haven't even seen any changes to their product. They might not do a single thing differently, but it's the brand and that perception built around it that changing that on a legacy brand is like very, very dangerous. Which means that's why it leads me to think that they are in, like they're losing money, they're losing market share. They know the only way to be able to revamp any sort of demand for their products is to completely change everything, which is very risky. So we'll see what.
Happens. Yeah, and I, like, I was thinking about this and I don't know if this is verified or not. You know, I saw it on the Internet. So who knows. But it's like Ferrari, right? If they, if Ferrari sells you a Ferrari and you do something weird with it or you paint it lime green, you are blacklisted. I believe that's true. I've seen it on the Internet. Right. And that's because it's their brand. Like you buy a Ferrari because it's class, it's elegance. You don't get to. The Ferrari is cool. You don't need to make it cooler, you don't need a custom paint job, you don't need to butcher it, you don't need to put whatever kind of tires on it. It's the Ferrari. It is perfection, it is beauty. And, and Jaguar obviously is not at the same level. Ferrari, I'm not comparing them, they're apples and oranges. But they're having this pivotal shift and I feel like it kind of reminds me of the conversation last week on Red Lobster. I wonder if Jaguar's main consumers are old and dying off and so now they need this shift, this rebrand to the millennial, to the Gen Z, because Jaguar is this kind of old legacy kind of brand that they need a new market to tap into. So they have to.
Shift. I think if, I think they're like three years late. If they would have done this three years ago, it probably been like such a.
Hit.
Yeah, fair enough. Well, anyways, I saw it blew up on X. I was like, I gotta show this to Mike. I. The branding made zero sense to me. Obviously there's tons of research that is done into this. I, I am a nobody when it comes to marketing cars across multiple countries. But it was interesting and I thought we'd talk about it. Alrighty. Now I'm going to jump to a question from the audience here. Make sure I pull it up and read it verbatim. So this is from Adam Burkett and he commented on one of our recent videos. Has Mike or will he ever give equity in long tenured employees and in what situations would it make sense to give in employees.
Equity? Yeah, so we are doing that. And so up until now I've, I'm the only one that has and it's vesting over a long period of time and so in cases of doing that, is he asking for myself, myself personally or like, for like.
Business? Yeah, it was, it was a two part question. I feel like it is kind of a. Have you ever done it? And then what situations would make sense to give it away? So I think it's kind of a two.
Pronged. Yeah. It's mostly talent acquisition and talent retention. So talent acquisition of like people that can make gobs of money. If you don't have the money you can potentially use in your comp plan.
Equity or profit sharing. And then when it comes to retention to people, it's like, well, could the company survive or would it do as well without this person? If not, what's that value worth? And then realizing that as the company grows, demands in terms of equity are important because of capital raises. Or if you take the company public, like you've got to have equity there, otherwise you're going to dilute everyone. And so, you know, whether it's dilutable or not is also super important. And so I'm very, very frugal when I give it out because I'm doing it non dilutive, which means I'm the only person that will give up equity ever. And so that's a bit of a risk in terms of like if we need capital in the future. But yeah, I'm doing it at a very small level but then giving insight to everyone to be able to know like what's the value of that.
Etc. So when would, and I don't know Adam's situation from the comments. When would you give it away? I'm assuming he's probably a small business owner, lawn care business owner, potentially listening to the pod. When would someone. Because obviously your businesses are at a little bit of a different level in terms of total revenue and the ability to give away equity. Someone would say, let's say sub 5 million annual revenue. They have a great long tenured employee. That employee kind of needs a little bit more upside. What does that look like in this.
Case? Yeah, I don't recommend giving any equity in that case. I rarely, like, you know, it's been 10 years, I have never given equity away, so. And I bought out anyone else that owned equity this year. So I think for most people profit sharing is a better way. Mostly because you don't have a liquidity event and secondly you don't have any valuation mechanism that's solid. So you know, it's only now this business of size where we can get like outside.
You know, valuations and then say, what is this actually worth? So I can actually use it as a bargaining chip when I'm trying to bring in engineers or executives. And so I don't think the small business owner should be thinking about this. I think they should be doing profit sharing. It gets, it gets messy. It gets like legally, this is a huge process. I've been setting up this year to make sure it's, it's, it's transparent to everyone. It's very clear. It's all legally up above, above board. And then like what happens when we do go public and how these all event, how they vest? What happens if our liquidity events happen sooner? What happens if we take on debt? What happens? Is it dilutive? Like, is it class B shares? Is this class A shares? Like there's so many different layers to this. And so I do not recommend the small business owner do it. I would only do it if you're going to raise money, if you're going to go do an IPO or have a very clear path to an exit in terms of a sale, whether it be venture capital or you're actually going to go to a strategic buyer. I think that most people's time is spent better retaining talent using profit sharing. Just get simpler.
Yeah. Now what about the business owner because this has come up inside of Augusta as well. Going to throw another curveball at you that is looking to expand and add additional entities to their existing business. Right. So they have location one, they're going to start location two or they have lawn care business one and they're going to open pressure washing business one. What do you feel about that? Like hey, retain all the equity is what you're saying for your original business. What about when you open business number two, you have a long 10 year employee kind of same story. Would you give equity in that case? What does that look.
Like?
Eventually that business relationship will end. Not it's a matter, not a matter of if, it's a matter of when. And so at that point in time, whether it's done gracefully will come down to whether or not you planned well. And so it's not like a relationship to death do us part. There's very, very few business relations anyway and very few businesses in general that will last your entire lifetime. So it's a matter of like, hey, within the next 10 to 20 years we will eventually sell this, it'll go under, we will let it, we will let it fizzle out because we have bigger things that are happening. So like very clearly defining what happens when that happens, if, but when. So like what happens if someone gets divorced? What happens if someone wants out of the business? Who does the valuation? What is that valuation? Can we determine what the valuation is going to be based upon something like revenue or profitability and have a metric in place so we know what we can buy each other out at? So the other person wants out. It's like great, here's the valuation currently based upon the metrics we've already outlaid and then also realizing that if you're going to grow the business, it probably will need capital. And so who's going to dilute it? Is it going to come out of both people equally? Is it going to come out of the person that's only providing capital? It's going to come out of the person that's providing sweat equity. Are you both working 20 hours a week on this or one person working 41, working, working 10? How's that going to split? Is profit sharing because profit sharing is different than equity. Are we doing it based upon P and L? We doing it based on distributions? Like there's so many layers to this. And so I think that for the vast majority of small businesses they should focus on offense to the customer instead of these back end distractions at a smaller size scale. And this is why like we are well above, you know, 10 million before we start thinking about this because it costs a lot of money to figure this stuff out and put it in legal and put different entities and now holding companies, etc. And then like even the software just for every, for the team to be able to see what they, what their, what their options are, etc. And then down the road to be able to have like, you know, equity for the, for the team members to be able to have like a stock program where they can buy it at a discounted rate and then it goes on into the IPO, etc. There's a ton of layers to it. So I don't think people should think about it. I think your time is better spent building a bigger business. And so for that reason I think most people should retain the equity and give out massive amounts of profit sharing so that people are held accountable, knowing that those people, if they were super entrepreneurial and wanted to be in a business for 10 or 15 or 20 years, would probably have already done it. And so thinking that your general manager is going to suddenly want to be in this 20 year relationship with you when they have worked at your position, at that position for one or two or three years and they have a track record of hopping every two to three years is, is laughable. And it's, it's not, it's not even a matter of being unwise as much as.
Like you're going to sacrifice the relationship. And so most of the time people get, do this because like I like them, I, they're awesome. I really want to work with them and Realize that, like, that is going to come to an end. And so if you're going to do equity, I just say the same way that you prepare for the downside of an employee leaving, you got to prepare for the downside of a partner leaving. And it's not that anyone wants to. There's life events, there's sicknesses. There's stuff that happens in people's personal life. And so defining all of that is very, very complicated and can lead to some very uncomfortable conversations. And I think that most people would be better served just focusing on the business instead of all of.
That. So the one sentence summation would be, don't worry about it till you're past 10 million in annual revenue, because it costs more than you realize, and so much can change while building a $10 million business, or if you have.
A very clear path of how you're going to get there. Right. Like, there are definitely people inside of Augusta have partnered up and do very, very well together, but I think they've defined well their roles, who's spending on what. Each location has a, you own this amount of this location. I own this much of this location. It's very, very clear. And then if there's. There's back doors consistently, it's like, so if you want out, here's the valuation. You can buy me out. Okay. We're doing based on distributable cash. What happens if there's a bunch of cash at this location? Does it go in this next one? Well, this next one, I only own 40%. You own 60%. Like, so as long as it's defined, I'm okay with it. I think that when people start thinking about that stuff, though, they spend more time on that than just growing the business. So I wouldn't say necessarily, like, it has to be above 10 million. I would say it's like, you'd probably be over 2. You should probably be thinking about how to get to 10 at least before you start really making. Splitting it a whole bunch of different ways, especially if you're not just doing a partnership. Like, I want to be clear, I'm talking about, like, splitting tiny pieces of the company and giving it to a whole bunch of people. Like I am is different than, like, I'm gonna go partner with someone and they're gonna get 40% or 50%. Like, I'm not talking about that. I'm talking, like, splintering the company, and it's only worth it if we make the big exit. And so you're basically trying to get the long Term investment of the team the same way you have equity. And then you got to ask yourself too, like if people are getting, are getting equity, do they have to contribute when there's a loss? Right. Because there has to become owner's investment in back in the same way as owners distributions or shareholder distributions. Like who funds the losses of a company. So like for me, like I'm not giving, I'm not going to make people pay into the company as we're growing. And so like that makes the equity they're holding, like more valuable but also like highly risky. Risky because it's not worth anything until we go public. So there's a lot, I've been thinking about this a.
Lot. So yeah, it was kind of a perfectly timed questions and I like it like everybody knows I don't prep you before the pod. You don't know what's coming at you. And I know this is something that you are currently going through. And this was a comment someone made a couple weeks ago. So I've been sitting on it for a while and I wanted to ask. So I know you have a lot of thoughts about this, considering you're going through it now. What about, let's talk about startups. So whether you're starting your first business or you're starting your second location or another business or tertiary business, whatever it is, what are your thoughts on letting someone be maybe an angel investor or kind of an active investor? So to give, you know, story time with Lee, I asked to invest in P4P. I asked to invest in the franchise. You told me no both times. So I didn't even ask to invest in Copilot because I knew the answer was no. But you told me no both times. That's fine. We've obviously talked about it before and your reasoning behind that, but what are your thoughts? I wanted to not be an angel investor. I want to be like, hey, I plan on working for you for a long time. Obviously, you know, when I was trying to invest in these things, our relationship was still pretty, pretty young, like P4P. You know, we'd only known each other for two years. You're probably like, I don't know if this guy's going to stick around for a while. What are your thoughts on those type of investments or.
Partnerships? Like, personally, I get a lot. I get stressed out when I have, like when we're losing money. I think I would compound my stress exponentially if other people's money was being lost. And so that's why I've never taken on Money, I want to avoid that stress because I think, I don't think I'd operate as well and I don't think I could be able to operate in the team's best interest as much.
That being said, there is a finite amount of money I have, so there's a chance that we have to raise money.
And you know, when you're growing really quickly, you know, grow sucks. Cash I talk about all the time, but like, it does for me too. And so if you're not going to require team members that you're giving equity away to, to contribute that percentage into the business, it's got to come from somewhere. And so, yeah, long story short, I try to avoid it for a really long time. Two things. One is giving equity and two is raising money. Usually those happen the same time. Like you give equity and you take funds in exchange for that. So I've done the first part. Like we're working on the program as you know, over the next few months. But like over the next few months the equity part will be done. And it's like again, it's a small sliver of the company. It's non dilutive. No one has to contribute money in as we're losing still. And there's, there's plenty of room there though. If I needed to, I could go raise money. I want to avoid that at all cost. Like, that is like my North Star. Like if we can just avoid that if we can grow fast enough. So this, this next six months is super important for the company. I've never said this anywhere else.
So I.
Know.
The next six months are really important. Like we really do need to. Yeah, we're burning a lot. And so I got to really watch it the next six months. And so I'm staying focused on conference. But then like after that, people will seem like really switching to sales mode because I got to make spring rush count, like big time. Because it'll really, it'll really determine whether or not we need to raise money or not in 2025. Yeah.
Yeah. This is, this is all breaking news. I know I didn't prep you for this, but yeah, I guess, I guess that's news to a lot of people that you are giving away phantom stock, if you will, or equity or shares, if you will, in the business. Technically, you know, I'm happy to share. I don't know what I should or should not share it. Technically it means nothing, right? Technically it means nothing. It's all just paper. It's all just a docusign. But it could mean something for, you know, the employees that you're giving it to. And obviously, you know, to be kind of off the record here, like, obviously, I'm thankful for that. I appreciate the opportunity to be kind of rewarded, I guess, for loyalty and, you know, having been told I can't invest twice.
It'S. It's at least a good opportunity. And hey, if we have to raise money, just know I will be the first one in line and you can't say no to me at that.
Point. So, yeah, it would definitely be like we. I'd probably only go for one or two people and people that would add a lot of value to the company in terms of, like, investors. But I really hope we don't have to go there because see, the difference is when I. When I give phantom stock away, people are thankful when. When I. When they give me money for stock. Now they have.
Expectations.
Yes. And so that's a very different relationship. And so I don't want to navigate that if at all possible. I want to avoid.
That. Yeah, fair enough. Gotcha. All right, well, maybe a shorter episode today. That's all I got. I know. I want to respect your time as well. I don't think I have anything else. So we can wrap it up right there with a little not financial advice. Do you have.
Any? Okay, so I had a whole bunch of non financial advice earlier this week. Totally forgot what it was. I remember, like, dude, you need to write this down. This is gonna be really good. But I will. What I will do instead is I'll recap. I'll come back to.
What we talked about here. One second. See if I can do this. Oh, dude, we're.
Gonna. Basically the same. Not financial advice. I think I know where you're.
Going. Oh, really? I'm gonna come back to what I talked about last week, which is. Oh, Michael, you can't even open up your camera app. Okay, there you go. Can I connect this? Oh, I can't. On streamyard. One second. Give me a second. Give me a second. You're good. I know. I can't. Okay.
One second, one second. Hold. Hold it. Okay. All right, all right, all right, let's go. Okay. Did I switch cameras? We did. Let's.
Go. New.
Angle. So now this is. This is the situation. Let's see here. See if we can't figure this out. Okay, so that's the situation we got going.
On.
Yeah. Yeah. So I can't really see the whole thing, but you get the picture. And then. Oh, you can't see this one Obviously here what I'll do is I'll switch over. The new layout has been. It's been crashing. So this is. Then this is the laptop situation.
So yeah, it's been working well. It's been working well. Very good for the workshop prep. Have this separate device. They airplay great. So like, I can like what I'm doing now. I have this one down here. I can move it up. It's really great. But I turn that off and then it's like focus mode. Because this computer only. Only does Chrome. It's great. And so it's like literally canva my Google Doc. Like that's it. So it's been really good for workshop prep. I'm like ahead on workshop prep in part because of focus with this the past week. So I'm stoked. It was a good move. It was a good twelve hundred dollars.
Spent. There it is. Is that. Is that a new.
MacBook? Hey, hey, hey.
Hey.
Yeah. Yeah.
Dude. Yeah.
Dude. We're upgrading. All right. I have.
Permission. I'm gonna buy a new.
MacBook. Dude. It's pretty good. Yeah, Yeah. I was able to give mine away to someone else that needed it. And this one does airplay with this one a little bit better. But also this one's a little bigger. It's 15.
Inches. But dude.
It'S. I got for 11, $10,099, 16 gigs RAM. They have an 18% off right now on Amazon. It's literally way more cheaper on Amazon than it is on Apple. So there's my nonfinity 9 device. If you're gonna buy Apple products, buy them on Amazon, not the actual Apple site. Yeah, that's my non financial advice for the.
Day. That's great. I love it. All right, well, I need to go buy a new MacBook. So let's see. My not financial advice is actually a quote from you. I thought we were going in a different direction with you saying referencing last week. So we had. We had a conversation. You gave me some feedback, and this is a new quote that I'm living by, if you will. It's just let little fires.
Burn.
Well, that's technically from Alex.
But. Yes, technically from Alex, but you surmised it very, very well. For me, Mike shared a video from Alex Harmonizi about prioritization. And I was kind of struggling. I think I was just tripping over myself. And just the piece of advice of like, let little fires burn. Like, that doesn't mean like we're gonna ignore them. We're just gonna let them burn because they're not gonna burn down the town yet. Focus on the big fire that's about to burn down the town. And then, yeah, maybe that little fire got a little bit bigger. But you can take care of it very quickly. Don't focus on a little fire. Focus on the big fire. So that is my non financial advice for some, some of us out there that are overthinkers. I sometimes overthink things. And that is let the little fires burn. You can get to them. Focus on the big.
Fire. Let's go. Yeah. Well, you took your, you took the feedback very.
Well. Thank you, sir. Appreciate.
It.
Alrighty. I think that's all we got. Like and subscribe.






