Why Compounding Bitcoin Returns Are Insane
2 Dec 2025 · 1 min
0:31
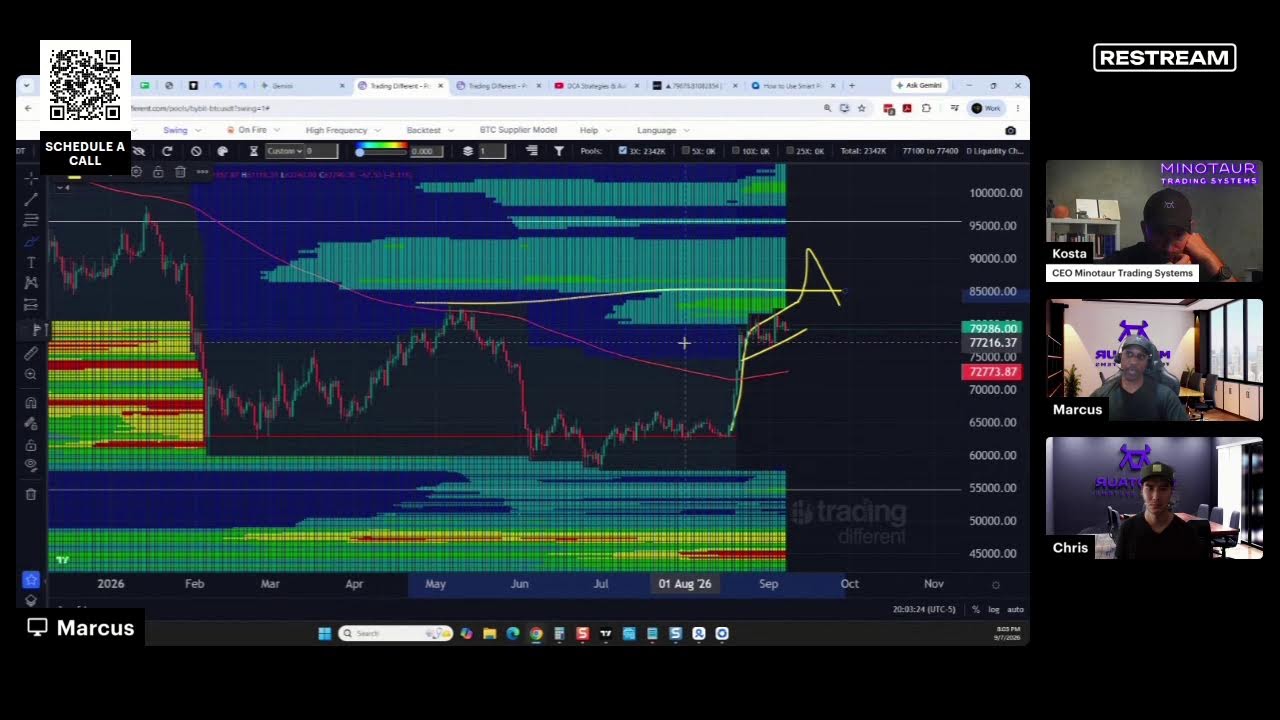
Kosta Ouzas explains how Monte Carlo simulations model Bitcoin returns differently depending on whether you use total historical statistics or local ones. When local mean estimates spike into the 20s or 40s, the simulated returns shift and become asymmetric instead of symmetric.