In this candid interview, Sequoia partner Alfred Lin discusses the transformative nature of AI, arguing that the current wave differs from past tech cycles because it moves the focus from pure automation to creativity and new customer experiences. He stresses the importance of building companies with a decade‑plus horizon, emphasizing long‑term stability over short‑term hype. Lin shares practical frameworks—such as focusing on inputs rather than outputs, measuring throughput, and iterating quickly—and illustrates them with portfolio examples like Tenea (automating medical revenue‑cycle notes), Clay (AI‑driven lead enrichment), and Zappos. He advises founders to hold opposing ideas in mind (short‑term execution vs. long‑term vision), to constantly zoom in and out, and to seek contrarian yet deep insights that create defensible moats. Lin also outlines Sequoia’s role as a first‑call partner, the value of founder circles, and how to assess product quality, retention, and sustainable revenue. The conversation blends strategic foresight, operational tactics, and philosophical reflections on entrepreneurship.
Chapters
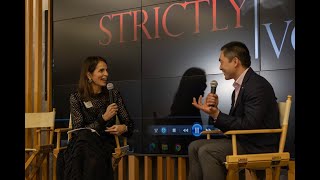
Hey, Derek.
Alfred, for being here, welcome back.
Thank you.
It's been about 10 years since we did our last conversation.
We trying to show me the video of me the younger self.
We looked a little bit younger, I will say, but we're both way better dressed now, I think, than back then.
Yeah, well, I get made fun of my dress, so I've had to up my game from some of my partners
would love to just dive in and kind of talk about what everyone's talking about. I know you're spending a lot of time on it, which is AI would love to first understand what is the difference between. Feels like in tech we just go in these cycles and whatever's kind of the new thing, we talk a lot about it. But how do you see AI being different from some of these other trends we've seen around mobile or consumer web or web three or maybe even the advent of the Internet?
Yeah, I think maybe it's good to have a broader perspective and zoom out. One of the things that has happened in my career as working in technology is that we see these megatrends, we identify them, and everybody's just running in circles trying to understand that megatrend. And I think everybody here is trying to understand AI. I'm trying to understand AI. You're trying to understand AI. But just popping out a little bit is that if you're here to build an enduring company, you have to look at things that are not three months out, you're not even three years out. You want to look for a decade out, two decades out, and you have to build something that's stable over time. So was there lots of things that are changing during the PC industry? Yes, but the companies that lasted built companies for the long run. Was that true for Internet? The same was true in the Internet. The same was true for mobile, the same was true for cloud. And it's going to be true for AI. And yes, your job is to understand what's going on today. But remember what we're talking about on AI today, we didn't talk about three months ago, which means whatever we're talking about now, we will not talk about three months from now. And you cannot build an enduring company focused on things that just keeps changing. We are in the world of accelerating change and your job as a founder is to understand that, but pivot from that and not run in circles. Run ahead in a direction that you think will help you build the long term. And I think one of the things that you're seeing right now is that we have gone from research and things that may be useful to things that models that are really productive. And everybody is now focused on automation. You hear companies saying that they can automate 10 to 20 to 80% of X, whether it's customer service calls, writing code. You just heard Satya this morning saying that 20 to 30% of the code written at Microsoft is written by AI. All of this is around automation. When automation happens, what's going to come next? It's really going to be about creativity. Now that you've automated a bunch of things, have you really improved the customer experience? What does that customer experience look like? So yeah, you can now cut the cost of answering a customer's call. But what then, what can you do to change the experience? The ultimate experience? And I think everybody's puzzling through that. And I would say that we've gone from automation to creativity and we're going to go from productivity to using your imagination to think what's possible. And AI is going to be magical when we sort of bring that all to bear. And I think there's not enough thought in creating new experiences than just automating things.
It's a really good insight and we've probably all experienced this using the different forms of AI that we're using today
where
something that used to take you eight hours to research or days to research, now you're doing it in minutes or in a few hours. And that enables you and frees you up to do hopefully much more interesting things than just scour the web for research.
And I'll give you examples from our own portfolio. To your point Derek, which is if you look at Tenea Kamir started out with just trying to automate RCM revenue cycle management. So they take the notes from doctors and they try to code things up so that they can automate those kind of things. They're listening in the background now to automate taking the notes. But when you automate taking the notes, what can you also do? You can reinvent the customer experience. All the follow up notes that are sent to the patient is, is sent automatically. Follow up appointments can be done automatically. All of those things that look like automation is now a new customer experience that the patient feels much more cared for. The doctor doesn't have to spend time writing up the notes, coding the insurance claim. They can spend time with the patient and explain everything much more thoroughly. These are the things that get created and done at Kareem at Clay, he built something that was supposed to bring programming to the masses and he used it for his own go to market purposes. So he's created a creative tool to allow you to grow your business. What does it do? It automates lead scoring and automates ingestion of data to enrich those leads and the information. And then the sales people in the sales team are now looking at that and, and coming up with creative ways to go speak to the customer in much more creative ways so they can grow their business. Now they have an enriched set of data and an enriched set of leads. Now the job is like, how do I get to them faster than my competition? Because everybody can also use clay to do the same thing. And we're going to end up having to be a lot more creative and reinvent the experience that people have across the board. It's going to be from writing code to finance to customer service to sales to marketing.
You talk about sort of thinking two or three steps ahead with your product into this area and everything's changing every few months. How are the best leaders that you're seeing staying ahead or what do you recommend? A start founder who's trying to get to product market fit and things are shifting so quickly. How do I make sure that I'm ahead of where things are going and skate to where the puck is headed?
I think that's a great question. Everybody asks that question every single day. Whether you're a founder of a startup with your co founders and the idea all the way to a public company. Because it is not like you just finished finding product market fit for a product in that end, I mean as a startup, you start with product market fit, you get there, then you go to, you figure out go to market, then you go to market and you expand, et cetera. And then at some point you get customer feedback, the product is not as good as you like and then you go back and you want to improve the product. And that's what's happening every single day. It's just happening faster because of AI. But just think about the past. If AWS stopped at providing compute and storage, it wouldn't be AWS today. If Apple had stopped at just computers, none of us would have the smartphones that we have today. If Jensen just stopped at GPUs processing graphics, it would not be the processing power for all of AI today. And so you're going to constantly keeping, you're going to be constantly listening to the customer and improving your product and continuing to find product market fit all the way along the journey that you have. And if you do that and you're staying close to the customer I think you'll have a much better shot at winning. This is a repeat game in many sense, in many, many ways. And I implore you to find people around you that will help you debate these things. Whether it's a founder circle, when you raise money, think about raising money and using that as an ability to recruit a partner to your inner circle where they can help you zoom in and zoom out. And that's what we try to do at Sequoia. We like to start as early as possible and we stay later. And this is where I can give you examples where we are the seed investor in Airbnb and we're still on the board 16 years later. We were early investors in DoorDash, and 10 years later, we're still on the board and we're still talking about how to constantly improve the customer experience. And if you do that, you have a winning shot. And by the way, your product on day one will not be your product when you're an overnight success a decade from now. The other thing I would implore you to think about is many of the founders that have built these companies. None of these milestones are reasons to feel like you're done. They celebrate those milestones. But we work in such a fun and dynamic world where you and your co founders with an idea can start today and in a decade your company can be worth 1 to 10 billion. Billion. We know plenty of companies like that. Within a decade, it's worth 1 to 10 billion. In two decades it can be worth 10 to 100 billion. Just like Airbnb and DoorDash are worth. They're about two decades old, they're less than two decades old, they're about $80 billion. In three decades, you have companies that are worth a trillion dollars, such as Nvidia and Nvidia and Facebook or Apple, Google. These companies in three decades being a trillion dollars. Now, if you let those trillion dollar companies compound for another decade, take $3 trillion like Microsoft and let it compound another decade, we're gonna. In your lifetime in your career, you're gonna see 10 trillion dollar companies and so raise your scale of your ambition and shoot for what has never been done before.
When it's just a few people in a garage or in a small office or over zoom virtually and you're trying to find your first few customers and get some wedge into a market and start to be known, it's hard to think that way. But because you're just trying to get from 0 to 1 or some other analogy, how do I hold those two things at the same time of just get out there and make a small dent, but also at the same time keep this thing in the back of my mind that hey, I want to build a big enduring company for the long term.
Yeah, I think the toughest job of a founder is holding two opposite ideas in your head. And this is not a concept that I came up with, but I'm fascinated by this concept. So F. Scott Fitzgerald said that the sign of a first rate intelligence is to be able to hold two opposites in your head and still function. And I very much think that is the the job of a founder. It's job of the management team. In fact, I started writing this blog called Outlier's Path for that reason. Most of the frameworks that I ask founders to think about are holding two opposite ideas. Intention. And so I don't have a perfect answer for that question, but that is your job. You've got to make progress on the short term and still have the vision for the long term. And often I have this quote about I enjoy my job because I get to listen to founders pitch me on ideas that I may or may not agree with. But they see a problem that is broken in the world, they want to go fix it. They want to put a dent in the universe because of that. But they are also grounded in the realities of today. And the job is to take those two different planets that connect the dots along the way. And if you can connect the dots along the way, then you can explain it to others, then people will follow you. And another quote that I really love is from Richard Feynman. He was very nervous about going to meet Albert Einstein. And when he came out of that meeting and that interview in that seminar, he said that Albert Einstein is a giant. And the reason is because he has his head in the clouds, but his feet on the ground. And that's also the job of a founder. You have to have your head in the cloud, but you have to be grounded in the realities of your today. The one thing that you can do if you are like that is you can zoom in and zoom out across all different levels and see things in different perspectives. You guys have probably all seen the YouTube video where you're lying on planet Earth called Distance Zero. And then they go up in scale like 10ft, 100ft, 1,000ft, all the way out into the universe. And the perspectives are just very, very different. And then you go back down, and then you go down to micro, micro levels. And the perspectives are all very, very different. The reason you want to have your head in the cloud and your feet on the ground is to be able to zoom in and zoom out. The problem looks very, very different when you do that. And sometimes it's getting that perspective that allows you to solve the problem in a different way than everybody else who's looking at the problem at the same level. And I think the best part about finding, having a founder circle, finding partners who sit around the board with you, is their ability to help you zoom in and zoom out. And that's my favorite part of the job when I work with founders. And at Sequoia, we kind of think about our jobs not as just investors. Of course. We invest money on behalf of our LPs, but we really measure our success if we're the founder's first call. Because if you're puzzling through a problem, we want to be your first call. So we can help you think through that and help you zoom in, zoom out and try to understand the problem in different perspectives.
Do you have a special bat phone that founders have access to? Or are there hours of operation or
is it hours of operation 24 7, 465.
Always available.
Always available. Yeah.
I think Sequoia has that reputation that if there's a need or if their meeting needs to happen, we're going to make it happen whenever that is. What's changed with company building in the last couple of years from what we saw, maybe in the few years before that?
Yeah, that's an interesting question. And people ask that at every single megatrend. And there's always this like, oh, I have to be, you know, AI native right now. Well, or back, back when mobile was coming out, you'd be mobile native. Or when cloud was coming out, you want to be cloud native. And I think there is an element of that because you need to run fast and you need to get some engineers that are AI native today. But just think about it from this from a different perspective. Do you want to serve AI Native people or do you want to serve all people on the planet? Are you building for AI natives? Are you building for everyone on the planet? If you sort of zoom out, you'll notice that you want the AI Native people to help you get an edge or a head start on AI development. But really, really, you want to serve all people. And this debate happened in every single generation of technology. Oh, we should just build our product for digital natives. Maybe as a start and maybe today you want to build for AI Native companies and customers. But just understand, for the long run, if you're building an enduring company, you want to serve every single person on the planet, if you can.
How do you think about success in a company at the early stage and then zoom out and how you think about it in the later stage?
Yeah, I think the metrics and the things that you look at are different. I also separate this thing, which I learned from Amazon. What are the inputs and what are the outputs? Most boards, most management teams focus on outputs. They don't want to get into the details of breaking the outputs and understand the inputs. But if you sort of think about, you know, your business is. Your company is a black box. You put certain things in that are inputs and what do you get as outputs? Both are important, but I think it's much more important to focus on the inputs and how quickly you can produce outputs. The black box that you have, you should also think about it as throughput. How quickly do you have inputs into this box and how quickly do you get through it? So as an example, you hire a bunch of engineers, how quickly did they generate code, how quickly does the code generates into a product, how quickly does the product get sold? Because the output is going to be revenue at some point. And yeah, if you're the very early stages, you're not even thinking about revenue right now. You're thinking about how quickly do you hire engineers, how quickly do you write code, how quickly do you have a product, how quickly can you serve customers, how quickly are the experiments when you get it in front of customers, suggest improvements in your product, how quickly do you get to product market fit? And you know, this is the thing, in the early days, the founders have enormous, enormous impact. And when you, when the company gets larger, you still have enormous impact because you have the moral authority to set culture, to set direction and all those things, but you're going to be one of many instead of when you're small, you are. Your founding team is often doing a lot of the work. And so that's why in our seed spec, we look for outlier teams, starting with the founders. Why are you outliers? Why are you going to build something special? We look for novel and compelling insights. It's those insights that sort of bring to bear something that's going to be unique and different and you're going to build something and solve the problem differently than everybody else. And we're looking for people who are daring. So you have a founding team, they have a unique insight. If they don't dare to start or to build, it's just not going to happen. And so we're looking for those three elements that come together so that we build a product, then we're looking for the go to market and eventually we're going to look for business quality. So growth investors usually look for the quality of your business. Certainly public investors think about the quality of a business over other things. And so it's a complicated answer to your question. But the thing that is true along the way is that the best companies, the founders, never stop. And back to my point, if Apple had stopped with computers, we wouldn't have the smartphone. If Jensen had stopped with just graphics, we wouldn't have the AI computing power that we have today. And if DoorDash had just stopped at restaurants, it wouldn't be the surface area that it has today. And so there are just so many examples of founders that constantly reinvent themselves, constantly reinvent the company and they're constantly raising the scale of their ambition so they can build for the next chapter of the company. And they think about their journey as a never ending quest.
When you say people care about the quality of a business, what does that mean?
Quality of the business? In the early days, maybe the thing that you're thinking about is engagement of the product. Then you want retention, then you want monetization. You want monetization that doesn't churn, you want monetization, that's repeatable. I have this, you know, I have this case study and I just showed the financials of these two different companies. One of them is Visa and one is JP Morgan. And you'd be surprised that Visa and JP Morgan are of their market caps. On this particular day that I sent it out, they had the same exact market cap. But JP Morgan's net profit was larger than the revenue of Visa. And the reason is Visa's business has network effects. It doesn't have to risk capital, Banking requires you to risk capital. And so predictability of your revenue, predictability of, of your customers, resiliency of the business and the business model is important to investors. And so if you have very volatile revenue, it doesn't get the same multiple as very consistent revenue, consistent growth. It's seen as a higher quality business. Companies that have network effects are seen as higher quality businesses. Companies that have moats and, and defensibility are seen as higher quality businesses. But I also just want to rewind and go back. No startup is defensible on day one, so defensibility is important. But on day one your job is to build something that the world has never seen before and then run as Fast as possible in the right direction.
So what stage do you want to see a company become start to create a defensible moat? Does that come very, very late or does it.
I think it depends on the business. I think, you know, it just, it really depends on the business. I think for AI companies, I think a lot of that right now is just building a business that is that, that allows people to do things that they haven't been able to do before. And then around that, then you start building a customer base. The larger the customer base, the larger the customer base, the more defensible the business is. If you, if you think about it from a long term, if it's. If you're just a wrapper around the models, that's not defensible. Even if you have revenue growth. That's why people are talking about vibe revenue. Is it really going to be revenue that sticks around? So think of. You don't need to think about it on day one, but you will want to think about it at the series B, for example.
Yeah, Viber revenue is a really nice way to say churn.
Yeah. I think in the early days when you have revenue growth, but there's high churn, you don't actually see it because the growth rate masks the churn. When your growth rate comes down, the churn becomes a more and more important element.
Yes. When you see these companies coming in at the early stage and you've invested in some of the biggest recent companies that have come out of the Valley and you've invested them at the earliest stage, how can you, how do you differentiate? And as people are, you know, everyone here is not going to be able to know pitch you but how do you, how do you see that difference between. Boy, they really have a key insight here that could be market changing versus you know, it's nice but this is maybe a wrapper on something. This may be. It's not really a strong enough insight. How do you. Is there some, is there, are there indicators there that you hear or you look for that I could look at my own product and say maybe, maybe I'm not there yet.
That's a great question. I think maybe just pop up a level. One of the things I love sometimes is just think about the world in opposites. And one of them is if someone else's feature is another person's bug and vice versa. And so if you go back to Instagram, the crappy phone was a bug, but it's a feature because all we have to do is put on some filters and make the grainy photos look a little bit more grainy and it looks better. Well, that's pretty creative. So the bug of being a grainy photo was to the Instagram founders kind of a feature, because they made it even grainier. And I don't think most people would have thought of that. They were like, oh, we have to improve the camera quality. We need to make the lenses better, we need to make the software better so that it looks more real life. And that's completely different than what you would have expected. And then Airbnb is my favorite example, because when my father was, he was running an international bank and he was opening up branches for the bank, he traveled a lot. And travel, when my father was running around the world was very volatile. And today you have plane cancellations and delays and all that. He had more of that because there are fewer flights going on. And so the one thing he did not want to have anything be different was his hotel room. He checked in at the same brand hotel, got the same size room anywhere. He went around the world down to that. He knew exactly where the hairdryer was and he never used a hairdryer. And he mentioned that to me and was like, dad, you don't use the hairdryer. Why do you care? It's like, when I travel, I want there to be no variability at the hotel I'm staying in because there's so much variability around my travels. And to Brian Chesky, that's like, that's a bug, that's not a feature. It's like, that's crazy. It's like, wow, this is like staying in a prison cell. It's the same thing over and over again. And he wanted to create something that is completely different than what existed then. He wanted something that was much richer in connectivity to local travel. So there was these lines before belong anywhere about travel, like a local, never be a stranger. And a better way to travel. And he just felt like that was a better way to travel. And that is sometimes a litmus test, like, how deeply do you think about things? And are you just improving the functionality by 10% or 20%? Are you rethinking the problem? If you're rethinking the problem, most people are not. So one form of defensibility is the fact that you rethink the problem that everybody is trying to solve. You're doing it differently, and you're going to solve the problem in a completely different way for a period of time. Nobody's going to do that. They think that's Crazy. I'll give you an example that is very, very pertinent to my career at Zappos. To me, if you had to ask me, on the original investment into Zappos, where Tony Hsieh and I invested as seed investors, it was the fact that there was a unique insight into the business. Nick Swimmer had left a voicemail on the phone saying that he couldn't find the shoes that he wanted on the Internet. And the shoe business is a large business, and you're like, nobody's going to buy shoes online. And he went down to the path of like, the shoe business is a $40 billion industry. 5% or 2 billion was already being done by mail order, which means that's big enough of a market size. And the only thing you have to believe is the Internet was going to be bigger than mail order. And so you didn't actually have to believe people were going to buy on the Internet any more than the fact that they would buy on mail order. So the depth of your thinking is really important. And then, by the way, the thing that we had to solve was that people didn't think that people would buy on the Internet. Well, if we solve returns and we brought the store to your home, then more people would buy. And because people thought it was crazy, for the first five years of Zappos, there was basically no competition. You have to ask me why some companies win. It's because they have an insight that nobody wants to copy. And yet it's the right insight. If you actually think through the logic, that insight is very crisp, clear, and right. It's just that nobody else believes it yet. So, you know, I'll leave you with this framework of, you know, consensus and contrarian. Right or wrong, you want to be right. But the place where a lot of money is made by both founders and investors is to be right and contrarian. But don't just be contrarian, because if you're contrarian and wrong, it's not so great.
Not good.
Not good.
Alfred, thank you so much.
Thank you so much.
More from Alfred
Sequoia’s Alfred Lin explains why your startup should focus on being different rather than “better”
Alfred Lin from Sequoia Capital | Advice for founders, future of consumer social, and more