Building Zappos & Investing at Sequoia with Alfred Lin
In a live speaker event, Alfred Lin, partner at Sequoia Capital and former COO/chairman of Zappos, shares the arc of his career—from early decisions to join a startup instead of completing a PhD, through operating at LinkExchange and Zappos, to becoming a venture investor. He explains how he manages risk using pre‑mortems and pre‑parades, the importance of founder‑market fit, and the role of differentiation (service, selection, culture) in Zappos’s success. Lin discusses how his operating intuition translates to investing, emphasizing partnership with founders, outlier teams, and market tailwinds rather than checklist compliance. He offers practical seed‑round advice, urging founders to interview investors and view the cap table as a long‑term relationship. The conversation moves to macro considerations, the impact of higher interest rates, and the AI wave, where Lin highlights large language models, their potential applications, and the need for defensibility through continuous product improvement. Audience questions explore rebuilding Zappos with LLMs, AI defensibility, competition, founder‑specific fit (e.g., DoorDash, Zipline), venture fund origins, relationships with portfolio companies, and advice for founders chasing technology trends. Lin concludes with contact information and an invitation to engage with Sequoia’s seed, venture, and growth funds.
Chapters
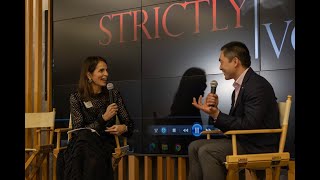
We're delighted to welcome Alfred Lin from Sequoia Capital to join us here for our next speaker event. In the Negative one To now series, Alfred began his career as an operator at companies like Link Exchange, Tell me Zappos, where he was chairman and COO for several years through their acquisition by Amazon. He then joined Sequoia Capital as a partner, where he's been an early investor in companies like Airbnb, Doordash, Instacart, Fair, and many more. We're really delighted to learn about his experiences operating, investing in some of the world's best companies from the earliest days. And even more excited to do it in front of a packed house because I think last time we had Alfred here, we were all at home doing it over Zoom.
All on Zoom last time.
Yeah. Excited to have you here in person. Let's give a warm welcome to Alfred.
Thank you for having me here. It's really fun.
Yeah, we're delighted. So we'll start kind of at the beginning of your career. SPC is all about the negative 1 to 0. So we're going to go all the way back to the start to begin in the negative 1 to 0. We talk a lot about a big part of the journey is getting comfortable, taking risk and deciding when to kind of take the leap. So the first question I want to ask you is at the beginning of your career, when you're thinking about joining your first startup, forgoing your PhD and kind of going down this path of taking this risk, how did you get comfortable with that risk? And what was your mindset like at that point in time?
I think the thing that is hardest about taking risk is you're concerned what may happen in failure and it turns out that it's not that bad. And the thing about it is you can't worry about failure. Failure. You're not going to succeed unless you think about success. And so one of the things that we do at Sequoia now is to write out our investment thesis before we make an investment. But we also write about the pre parade and the pre mortem. So if everything goes right, what does this company become? If things go wrong, what will have happened? And then if you read those two sections, you realize, yeah, things can go wrong. But this beautiful thing called the pre parade, what the company can look like when it is really successful is so powerful that you want to either join it, start it, or invest in it and partner with it for the long run. And so I didn't realize that back then, but I had lots of friends who Sort of encouraged me along the way. And I would just say I was living my mom's life. She wanted me to get a PhD in statistics or in anything. I happened to be in a PhD program in statistics because I was good at math, but she wanted me to be a PhD in anything so I could be a professor and contribute to the world's knowledge. And that's very noble for her. And when I was younger I was always interested in business and so at some point I just got up and thought about it and I had friends who were starting a company and I just decided to join them. And link exchange was a non obvious thing, but at least it was in technology. The first idea that Tony Hsieh and Sanjay Madden wanted to start was a Subways franchise on campus. I was like, come on guys, can we find a more leveraged business? And technology is great because it's a very leveraged business. The cost of producing the software is limited and the margins that you can make off of that business if it scales properly is high. And so we're all very, very fortunate to work in technology. If you just take a step back and think about it from that standpoint.
Did you do a pre parade or have a version of your pre parade when you were thinking about joining them or was it more serendipitous?
The pre parade I had was well, if this company fails I can always go back to the PhD program. I'd be fine. So yes, I mean in some sense I didn't label it pre parade but I did think about what is the potential downside in the situation. And it wasn't so bad. I can always go back and get a PhD, finish it off and get a, a job somewhere else. And then the other flip side is what happens if this company actually worked and it was one of the more successful companies at that time. And so I did think about how big can a banner advertising exchange can be. And it turned out to be a fairly large banner advertising exchange for the time in 1998. 99.
Maybe we can fast forward to another chapter in your journey which was joining Zappos, another company that you worked on with Tony. And as I understand it, it was actually a company that you had invested in, kind of invested in through your incubator and then joined a little bit later on when it maybe it seemed like a non obvious bet. So could you tell us a little bit more about that story, how you decided to go and work in the shoe business and pursue that venture?
Yeah, I never thought I'd be In the shoe business. We invested in Zappos out of the fund that we started after Link Exchange was sold to Microsoft. And we had raised $27 million from friends and family to start a seed fund. And one of the investments was Zappos. And we almost didn't make the investment. Nick Swimmer, who was the founder, decided to leave us a voicemail and he said that this sounds crazy, but I want to start a shoe business online. And we're like, come on, everybody has to try their shoes on first. How can you start a shoe business? And he then went through some of the facts. That seems to be a very important aspect of the business. He had looked into the market and realized that the shoe business is 40 billion and 5% was being done on mail order. So it doesn't take a genius to think that the Internet was going to be bigger than mail order. And that was initially a spin enough market to start a business in. And so we decided to invest in the company. And it was tough going at the beginning. We had not a ton of shoe experience. So we had to go hire someone named Fred Mosler. And he was working in the shoe department in Nordstrom's. But then when he joined Zappos, none of the brands wanted to sell to him. We had set up a bunch of meetings for the World Shoe association that we were going to and people would greet him and pat him on the back or give him hugs. And then they realized he was no longer with Nordstrom's and they basically escorted him out of the booth except for maybe, you know, he had maybe I'm going to, I don't know the exact Number of both 90 something meeting set up for that week. And except for about seven brands, all of them said no. So it was a very tough beginning. But over time we wore those brands down and built a business by having one of the best selection. But selection was just not enough because many people can provide selection on the Internet because you're basically having central distribution and central catalog. So we decided to focus on service. And I think that that is one of those situations where I've learned over time that you need to have differentiation. A lot of storytelling is about differentiation. Why are you different? Why are you different than anybody else? You don't want to compete head to head. You want to tell the story about why your product, why your company is unique. And I think sometimes we forget that. We just talk about why we're better than the competition. In fact, the best companies never talk about the compet, they just talk about the fact that they're different than everybody else and they see the world has a certain problem, and the company is out there to solve that particular problem in a very unique way.
At Zappos, you formed a really unique culture that you alluded to around service, and that felt like a big point of differentiation for you for a long time. Can you tell us more about kind of how you decided to focus on that and how that maybe played into your differentiation that you're talking about in retail?
There are many ways to differentiate. In traditional retail, it was being the biggest or being the Nichiest and having a different selection or charging the most because you have a differentiated brand. A lot of nice brands that we all love, they probably charge you a very nice premium to what you're actually getting, but you. You're willing to pay for it because you believe in their story, or you're buying things for the cheapest, or you price compare because they're approximately the same. It's a commodity. And we didn't want to pick any of those points. And we thought that service is one of those situations where everybody else is competing on selection and price on the Internet. And maybe we wanted to go opposite from price and opposite from just being a commodity. And so we thought that providing great service was going to be a way where we can maintain prices. And there is also, there's an element of the fact that Tony and I always admire brands that provide a great service. So often I think about founders and whether they have a founder problem fit or a founder market fit to the thing that they're trying to solve. And both Tony and I always liked brands that provided good service. It wasn't necessarily the best product, but it was the best experience in our view, because you got better service than going to one place versus another.
Interesting. So you kind of build up all of this intuition over your operating career about what it takes to build a successful startup. And, and I'm curious, as you left Zappos, transitioned into the investing world and joined Sequoia and became a professional investor, how did you have to retrain or double down on that intuition? How did that change when you transitioned from operating to investing?
There are obviously changes, but I think most of the fundamentals are pretty much the same, at least the way we do venture capital. At Sequoia, we don't call it venture capital, we don't call it investing. We're trying to partner with the founders that we we back, and we want to be sparring partners during good times and shock absorbers during Bad times. And we want to be partners. And so a lot of the intuition we have is whether we want to partner with someone or not. And yes, we have to make a return for our limited partners, for sure. But the way we sort of view it is where we want to back people who are outliers. They have a novel and compelling insight about the world, and they're working in a market that is maybe not large today, but will be large in the future. But it has to be large at some point. And so there are good market tailwinds around what you're building, and we're looking for those things. But in some sense, what many good investors do is to know which rules that they're going to break. So if you sort of look at every single venture capitalist, they want to outlier team. They want to have a large market. They want you to solve a problem on a large market with a product or service that everybody wants or needs. And therefore you can charge a differentiated amount for. If you check all the boxes, you're either in a situation where you have a null set because you can't find everything that fits, or you. You're in a situation where the company is priced to perfection. And the way to make outlier returns is to know that this stuff is not a checkbox. You have to figure out what you're gonna lean into. And the same is true with entrepreneurship. You can't check every single box in that list. That's not how companies get formed. You get passionate about an idea that you see the world's gotten wrong and you wanna go solve it, and it starts there. And as simple as that, you've had.
A chance to partner with some of the best founders of recent generations, founders of Airbnb and DoorDash, and some of these companies from the early days, maybe because it seems like these founders, they were outliers, they actually kind of maybe went against the common patterns. What did you see in maybe one or two of these companies? If you can tell us an example of what got you excited, what inspired you to want to partner with them?
I mean, founders are. They're all unique and different in many ways. And so you're asking for the commonalities, and I think the uniqueness is what makes them special for the companies that they're going to start. So if you take a founder that's very successful, like Brian Chesky at Airbnb, and you put him into another company, yes, he probably will be successful operating a different company, but he may not be as successful running something that is, that is very, very different from this experience that he wants to give the world. And the same is true with Tony Hsu at Doordash. If you take him out of Doordash and put him somewhere else, can he be successful? Sure. He was working at other companies and he was successful there. But I don't know if you get the same outlier elements. But the commonalities are founders are generally relentless. They just have a lot of positivity about the world. Their heads are in the cloud, but their feet are planted on the ground, meaning they can see things at a super high level and be super optimistic and see above the clouds and see the sun and out into the horizon. But they are grounded in reality. And often we talk about people who are able to hold two opposite ideas and make sense of it. And that tension, we talk a lot about that at Sequoia. We want to be a firm where we hold a lot of opposites in tension. But founders, the best founders, do that too.
I think most of the folks in the audience here, they're kind of in the negative one to zero phase through, maybe kind of preceder seed founder. Over the coming months and years, many of them are going to go out and raise their first rounds financing and figure out who to partner with. Since you see so many companies and founders go through this journey, I was wondering if you could, you know, talk to any of the common mistakes or myths that you see founders making or following when they go out and you know, raise their seed round. What are the, what are the common mistakes or myths that you would like to maybe dispel for this audience here?
I think the one thing I would encourage everybody to do is that when you get raising, it's a two way street. You're not just pitching your company. You should interview the potential investor that's going to invest in your company. My brother works for a hedge fund and so when he doesn't like the investment, he can trade out of it the next day. This is not the same thing in the private side. When we invest, we're on your cap table for a long period of time. It's very hard for you to buy the investor out. The opposite is also true. You're kind of stuck with the investor that you let into your account table and so be thoughtful about who you let into your account table. But it's also an opportunity for you to recruit a partner. And I think sometimes, especially at the seed round, many founders just look at it as capital and that's perfectly fine. If you don't need any help. But I'm pretty sure at the seed round, especially the seed round, you want all the help you can get. And so find people who are going to be helpful for you and realize that if the journey, if you're successful, that journey with that, whoever you let to be an investor is going to be a decade long, if not longer, if it's successful. If it's not successful, it will still be many years. And I don't think people think about that enough.
I want to be conscious of time here and make sure we get to plenty of questions from the audience. So I'll just have a few more here. Maybe shifting to kind of the present times. There's a lot going on in the world. About a year ago, you and the rest of your partners showed this presentation on Adapting to Endure, where you talked about the turbulent markets and times and how founders should adapt their thinking, shift their thinking to react to it. And I was wondering if you could maybe talk to your perspectives on kind of the macro in the world right now. Could you share maybe an abbreviated or updated perspective on how founders should be thinking about the macro, given that on one hand there's a lot of uncertainty in the world, and the other hand there feels like there are bubbles or excitement around things like AI that are pushing the world forward. What is your latest thinking there?
Well, we're not macro investors. When we see certain trends, we will talk about or write about it. Many of the things that we write about were not macro trends. They were just, you know, things that we think people should be aware of. So there was the black swan memo that came out. Then there was, you know, accelerating out of the turn, coming out of COVID and then Adapting to Endure had a lot to do with the fact that many of the companies that we saw had raised way too much money, their valuation had gotten ahead of them, but their business was not at the same stage as it should have been. And we're heading into a time where some of this was going to get rationalized. I think today, if, you know, looking at today, there are a lot of opportunities with this new wave of AI. There's also we haven't seen interest rates as high as this level for a while. It's not the highest level of interest rates, by the way, so I don't think people should be concerned about that. But so we see the current environment as there's this tug of war between all these opportunities that are happening, but also just the higher cost environment to create a company. So higher interest Rates just means the cost of capital is going to be higher. So that's going to affect your valuation. The cost of inflation being up and salaries being higher is just going to cost more for your company. And at the same time, there's all this power with AI to do things in much more efficient ways than has been in the past. And so in some sense there's this tug of war happening and I think it's incumbent on founders to sort of understand that. And any place you can find efficiency, you should use it, which was not necessarily the way that we thought about the world in the past. When money was chosen cheap and interest rates were low, it was grow at all costs. And now it's much more of a balance. You have to grow, but you have to grow in a much more constrained environment. And we haven't had to do that for probably 10, 15 years.
I'll ask the question that I think was maybe our most commonly requested because it's top of mind for everyone and you alluded to it there, which is kind of the AI craze that is going on right now. Tell us a little bit about your thoughts on that. What specific kind of AI trends or applications do you find most promising for startups and early stage companies right now? And then maybe on the flip side, what are things that you are skeptical of?
Well, there are a lot of people here, you guys will probably have more of the ideas than I would. So I would encourage you to think about it yourself and talk to lots of other people than to listen to me pontificate about that. There's lots of things happening that are moving very, very fast. But I think also language is important. AI has existed for a long period of time. I think the proper thing that we're viewing now is this ability for large language models and transformers to do things we never thought was possible. And a few years ago we could have thought that computer vision was the edge of AI. Right now we think large language models is on the edge of AI. We may not think that in three to five years from today, maybe it will be longer, I don't know. I wouldn't pretend to know that. But I would say that we should all understand how powerful large language models are and what you can do with them. And so, so if you ask my infrastructure partners, they would talk about, well, let's understand AI safety and all the things that you need to have safety be in there. You think about all the large language model tooling that is required to make that productive for applications, even sort of having the right compute so that you can run these models, the infrastructure to do that, whether it's Foundry or coreweave or any of these companies. Um, and then there's an element of, of like bringing that stuff to life. And so to bring that stuff to life has to do with what applications can be made. And now I think it's quite interesting. One of the things that I've learned over time is that someone else. Someone's feature is someone else's bug and vice versa. So you've heard the term that hallucinations is potentially a feature and not a bug. Well, that's maybe true in consumer because, well, if you ask an LLM to create an image for you and it doesn't quite work, it's like, oh, that's kind of interesting because that hallucination is a feature. Well, I don't know if that's true in certain other applications. And so we need to fix that too. So if you are doing surgery, I don't think a hallucination and drawing scalpel across your. Your body at a tangent was what was intended. That hallucination is not going to be very helpful. So in that case, the hallucination is an error and it can become a liability. There's going to be a lot of this work that's going to get rationalized for when do we want hallucinations and when we do not want those hallucinations before we can bring real applications to life. That could be tuning and, and the developer stack that gets created. And on top of that, the first initial applications with creativity, whether it's midjourney or Runway ML, all of these things, or pika, all of these things are just touching the surface of what's potentially possible. So creativity, I think will be vastly improved with AI and that will lead to consumer social applications such as Kana Suite. But also the most powerful things are going to be things that make our lives a lot easier. Whether it's applications and customer support or law or anything where it reduces the burden of places where humans are spending a lot of time doing grunt work should get compressed so that we can do other things that require the things that humans are best at.
Hopefully the next application will come from someone in this room.
Yeah, but I'm sure you guys have way better ideas than I do, so I would encourage you to continue to think about it. The other thing I would encourage you to do is don't pursue someone else's idea and passion. Make sure you really want to work on that idea for the next 10 years.
Maybe with that, why don't we open it up to the audience for some questions? People have a question, just raise your hand. We'll call them out and then pass around a mic, I believe, to make sure that the folks on Zoom can hear us. Who has questions? Why don't we start with Tomas over here? Get him the mic. Hey, Alfred.
Hi, Tomas.
If you were rebuilding Zappos kind of customer service obsession with LLMs, like if you could go back in time but you had access to ChatGPT, what would you do differently? If anything?
It's a good question. I think that the thing that was hard about customer service in the way that we built Zappos was the feedback loop to change the product. A lot of people talk about, oh, I can reduce the cost of the support ticket. Yes, we can do that. And I think a lot of companies are already experimenting with, before this, before LLMs, with machine learning to automate some of the tickets that come in, whether it's calls or emails or things that are broken in the product, but realize the reason they're calling in is something was broken in your product and getting that feedback loop back to the product team and the engineering team to go fix that was a process. But imagine if you could just automatically have some of these changes happen in your product. That would be pretty powerful. And you know, in many of the sort of situations where you would just at the end of a quarter, you get all the tickets and you realize this is the largest ticket that returns. We need to automate the return process. Exchanges. We need to automate the exchange process. Tracking my package. We need to automate the tracking my package problem. Those things are you wait for a period of time to figure that out and then you change the product. I mean, it's kind of slow. Imagine if you could just do that in a continuous fashion.
Super interesting. More questions.
Thank you. How do you think about AI and defensibility in AI given the speed of everything changing? So defensibility is always an. Is an important question. You're basically asking about what are your long term moats. And I think it's one of those interesting questions where in the early days of a startup you probably have no differentiation at all. You're getting a product launch, you're trying it out, and over time you want to think about whether you have differentiation. And I think the process by which AI is going to keep improving, you need to just make sure your product improves at a faster rate. That's not a very fulfilling answer to your question, but that is how Technology works. So if processors get faster and faster and faster, your, your ability to produce a calculator needs to be more and more sophisticated. So creating a, you know, simple calculator wasn't enough. If you produce MA, you know, R or, or MathWorks, that would be more defensible. So, so think about it from that standpoint. It's the same thing. So the power of the LLM will get better and better and your product has to get richer and richer and richer. I often think about startups as you have a thin layer or a thin wedge and then you need to thicken the layer or widen the wedge and so your surface area of your product has to increase or deepen.
We had another one over here.
Hey Alfred. So you talk about the best companies, they don't talk about competition. So each of the best companies are unique. My question is. So my partner and I are kind of in this zero to one phase. We are very passionate about this idea. We think there's a problem of the world one, so. But in our market research we saw there are some other early players in the domain they are kind of trying to solve like the high level of this same problem domain. So in this kind of situation, what would we recommend?
So I think if there are already companies in the space that are solving that particular problem, you need to have a unique take on why you're going to solve it better than they will and different than they will. And I use better, better and different together. Differentiation without making your product better is not really that useful. You do have to be better than your competition, but you have to be different.
Yeah, I think just a quick follow up. So I think these days there are so many new companies, everybody wants to use AI to revolutionize the domain. So sometimes from this very early competitors, I feel it's really hard to tell.
You can't.
Yeah. So what's their.
I'll give you an example from doordash days. Very competitive space. Right. You can think of doordash as being no different than anybody else or they have to figure out how to be different. One of the things they differentiated on was. So it's a three sided marketplace. There's drivers, there's consumers, and there's merchants or restaurants. In the very beginning they focus on selection, which is not what every single restaurant delivery company focused on. They just try to be different in a dimension that they believe will end up making them better because the consumer wanted selection. You and I may individually only order from three to five restaurants and that's fine. But this group three times 300 people. That's a lot of different restaurants. Yes, there's going to be overlap, but they believe that selection was going to be important. And so this is where I think founders have to come up with a novel and compelling insight into the industry that no one else has. And yes, everybody's going to move fast, but they're going to move fast in different directions.
Thank you.
I think that's a great anecdote that highlights that. Other questions. You can come over here. Bring the mic around.
I had a question about something you mentioned earlier, which was that for you believe that the alignment between the uniqueness of like a founder being suited to the specific business idea or company they're working on is really important. And I thought it would be helpful if you could expand on that a little bit more, maybe with examples of, like, investments you've made where you felt like the founder was really uniquely suited to that specific business and why I think so.
If you heard the story about Tony at DoorDash, he grew up washing dishes with his mom at a restaurant and he was by her side. And he grew up learning about the restaurant business and knew the pain points of a restaurateur where they had a lot of kitchen capacity, but not necessarily a lot of front and capacity in the front of the house. And so he had us insight that dated back to when he was 12 years old. So that's an example. Keller, who is the founder of Zipline, he'd been building robots when he was a young child, and he had always believed that robots could do things in very automated fashions that humans would prefer not to do. And so did it translate into a physical robot? No, it translated into originally a platform for robotics, which was originally robotive. That pivoted to Zipline, which is a drone company. At least it's sort of in the same space where he's trying to think about problems where it's just more efficient for a robot to do that job.
Jonathan, I saw on your LinkedIn you have something called Venture Frogs. Is that just a holding company for angels or did you have any, like, side hustles with Tony that are interesting to share?
Venture Frogs was created after Link Exchange was sold to Microsoft, and it was basically friends and family of Link Exchange invested in Venture Frogs and that was our seed fund.
Did you have. Sorry, I was going to. Did you have any side hustles or fun side things with Tony?
Side things? I mean, the main hustle was the fun, but we had a restaurant, Bencher Frogs Restaurant, which was not that successful restaurant business was never good. But as I mentioned, Tony and Sanjay wanted to have a Subways franchise on campus at Stanford. And back then it was unheard of. And I told them there's already one on University Avenue. But they wanted like, no, nobody wants to go off campus. Just have an on campus. And back then it was like, no commercial companies are on campus. Obviously that's changed. They were always a little ahead of their times. So then we had a restaurant, we had maybe a few side hustles. Like we bought some domains such as drugs.com and bbq.com and we thought potentially sell certain things on those websites or just use them for SEO. But the main work was investing in that fund.
And we go back here, maybe one more and then we'll come back over here.
I'm curious about relationships. You mentioned earlier about staying on chart table for 10 years. And I'm sure, like the company you invested, not every single one is as successful. Probably many of them are like just regular growth, lukewarm. What's the relationship like between those companies? And as investor, is it like going to Thanksgiving dinner? Really awkward. And any advice there, like, in terms of kind of those relationships? Yeah, thank you.
It's a very good question. I mean, I do mean what we mean when I said that Sequoia would try to be sparring partners during good times and shock absorbers during bad times. So I think when you know whether the company is doing well or not, you know better than the board member. And so when things are going too well, what we see is a bit of complacency. It's always the best time to say, hey, are you reaching your full potential? Can you go higher? That's the best time to sort of be a sparring partner. And then when things are going poorly, you know that things are going poorly. So anybody yelling at you is not going to be that valuable. We need to roll up our sleeves and help. And so I often think about it from that standpoint. And so that's the relationship we want to have with our founders. Relationships are complicated. And I think if, you know, if it was. We kind of think that everything goes up and to the right. It doesn't. It's a bunch of swigglies. You guys like to use the word squiggly. It's just, it's nonlinear and the relationship is also nonlinear. But hopefully you grow from the experience. And if you do, I think that that makes for a good relationship. If you don't grow from the experience, then it's not a great relationship.
Come back over to this side.
Good.
Again, how do you think about the dynamic between startups and incumbents? Normally startup find a smaller problem that incumbents overlook, but in this most recent AI wave, everyone trying to solve the same problem more or less high level wise, how do you think, who do you think will capture or create more value in this AI wave between incumbents and startups?
Well, I think the who captures more is not the relevant question because both will capture a lot. So let's just understand that from all the way back to when I started looking at technology, because I helped when I was young and in junior high school I started building computers and robots, the computer industry created lots of value for both incumbents and for startups. The Internet created lots of value for incumbents and for startups. That happened in cloud, that happened in mobile, it will happen in AI. And I think you're right at the beginning, the first initial innings of any of these technology waves, people seem to gravitate towards the same problem. But the companies that break out as startups solve something slightly different. And so I would encourage you to think about that. One of the lines that we now are using all the time is the Henry Ford line. If I ask my customers what they want, they would ask for faster horses. I think a lot of incumbents are producing faster horses. But have we reimagined what the car is with this AI wave? Think about all the things that didn't work before that could potentially work today. I often think about like, are you wrong about the investment thesis? Because there was not a good why now? This? Large language models create a new why now? For something that could have happened, you think about the computer industry. Many algorithms that mathematically someone had shown was this is an interesting algorithm could not be computed for a long period of time. And then our chips got faster. We created GPUs. Those GPUs were like, wait a minute, this performs really well with transformers, et cetera. But algorithms sometimes were created for a long time and was dismissed until the computers got fast enough. Okay, now we have large language models. What ideas could exist today that couldn't exist before? I'll give you examples of recent history that you will understand. Dropbox was an idea that in 1999 people tried. There was a company called xDrive. The problem with that is they couldn't automatically increase or decrease capacity because they had to build their own servers. So they had to provision so much more. And as a startup that was really, really hard to pull off the cloud Happens and you can automatically provision up or down, which saves a whole bunch of cost. So the company Dropbox was possible in the cloud, which was not possible before. I would also say that Uber, DoorDash, Instacart were tried before, but because you didn't have mobile, you didn't have GPS and you didn't have maps and navigation, those companies were not profitable. Imagine a taxi driver having to have all the city's streets in their head, head. And that is true for a taxi driver, for a delivery person, et cetera. So we basically used mobile and the fact there's a mobile device to allow anybody to become a taxi driver, a delivery driver, et cetera. And so I often sort of think about what can LLMs do that we didn't think was possible before? And then, you know, in terms of how quickly things are moving and people solving similar problems. We just went through OpenAI's Dev Day. There's a bunch of announcements. How does the world change now? Think about how the world changes. Both for. Oh, great. Those ideas I can't work on anymore, but it opens up another whole new set of possibilities. I was at a TED Talk where I forget the name of the speaker now, blanking. But he said that every problem has a solution and every solution creates another problem. This is the fun part about working in technology because it moves so fast. Even if a problem gets solved, there's new opportunities.
Is there maybe from your recent investments, a company that you think is building kind of the car for LLMs, that more innovative idea, imagining what the future could look like? Is there, is there a company that more recent than Dropbox that you would highlight for this, this latest trend of large language models?
Well, we, we obviously have to think that to invest, but I don't know if we're necessarily right or wrong. So a lot of people talk about English as a new programming language, Right. And so, yeah, Copilot is probably the most interesting native AI application that was created so far. Now you can't invest in that. GitHub owns it, right? GitHub is owned by Microsoft. Well, is there another situation where language or English is the code? And in some sense, our chief legal officer at Sequoia, Jung sun, said that law has actually always been in that situation. English or whatever language is the programming language for law because you write everything in plain or convoluted English. But that is quite interesting. And so now that large language models can exist, it's part of the reason why we invest in Harvard.
More questions from the audience. Samira.
Hi, Alfred so my question is, how do you ground yourself outside of the wave? Like how much do you actually think about non LLM things on a daily basis, if at all? I'm curious about that because there are constantly waves that are coming and going, but there are things to invest in that might not be part of the wave. And I wonder how you as an investor actually catch yourself or if you could maybe share some examples from the past that was not part of a wave but you invested in and it turned out to be a good investment. So curious about those.
Yeah, so I think the, it's a very good question, by the way. I think when you, when the wave is obvious, it's, it's not a great time to invest. Valuations are way higher than it should be, et cetera. You want to catch the wave before or you want to let the wave crash and then invest from there. You laugh, but some of the best investments were made after 1999. Right? So in the Internet, some of the best investments were made not in 2010, 2011 or whenever, in mobile, whenever the iPhone came out, it took a little bit of time. And so I think that you want to think about that all the time. Now, as a founder, I don't think that that applies the same way because you're setting the valuation. So you should just focus on what has to be true over a longer period of time for you to build that company. So I think there are a lot of quotes that Bezos is attributed to and one of the, the quotes I love the most is the fact that the one that he talks about, yes, there's always a new shiny penny, but sometimes you should focus on things that will be stable over time, because the things that are stable over time you can build a business around. And then he goes back and refers it back to Amazon, which is convenience and low prices. And nobody wants to have bad customer service. So they want to be the best, the most customer centric company on the planet. Nobody's going to say, oh, I want this later, I want it as quickly as I want it. Nobody's going to say, I want the same thing but for a higher price. So low price does matter. And so I think you should think about the trends that are going to carry you for a period of time, but what is going to be stable over a long period of time for you to build your company? And for me, grounding myself, I try not to be on my device all the time. It's still right here. I try to make sure I clear my head and try to read things that are outside of technology.
Maybe we can go to Chris.
Thanks. Kind of follow up question. I've been super into mixed reality for like 10 years and it's always just around the corner. I guess I'm wondering, you know, I've spoken to other founders maybe that are like really into bitcoin, been doing that for a really long time and it almost feels in some way that, you know, the time for those things has come and gone and now it's all about AI. So do you have any advice for founders who are true believers?
Yes, I think there could be. You can ask the question in a slightly different way, which is there's always going to be some mixed reality elements that could be made today, even though it seems it has come and gone. So what is it today that would be a very valuable mixed reality product that can be made. And if you're going to build this business over 10, 20, 30 years, it won't come and go because there will be more and more improvements in hardware. I think the limitation of mixed reality is hardware and nobody wants to be tethered or have something that's five to ten pounds on their head. So those things have to come down in both weight and capacity for compute and capacity for carrying a charge or just use less charge. And so those things are going to get worked on. It just may take some time.
Fortunately, Chris was working on that before svc.
So I mean, I think if you solve those problems, those become much more valuable. And I do think there are certain things that have to happen, right? Like the hardware has to happen before a plethora of applications AI, the foundation models have to get worked on first before dev tools can be interesting, before applications can be be interesting. So there's an order that these things get built. But if you want the world that you want to create is up to you. And so you can accelerate one of those levels of. And I think in this case, if you're very good at accelerating the hardware, it will make for. It will make mixed reality a reality.
I think we maybe have time for one more question, folks.
Hi, my name is Louise. Louise, I'm guessing you have tremendous exposure and access to, you know, the edge of technology and information. So I'm curious, in your experience, what has been something or a few things that have truly surprised you and this could be like obviously or non obvious and then obvious in hindsight and then just to give you some time to think, I'm in the genome editing space. And so the idea that Cas9 this enzyme from bacteria could be coupled with a small piece of rna, could directly edit DNA. Was both incredibly powerful and also beautifully elegant in nature. Curious what you've seen in your career, that's been truly surprising.
I'm going to date myself, but I thought, you know, I thought the ability to send email to anybody in the world when I was in college was truly surprising. And I think that, you know, I think we forget how, like, how powerful that is. I thought the touchscreen was quite surprising. Keep in mind, back to your sort of assessment about mixed reality, the touchscreen. If you go back in Wikipedia, people tried the touch screen in 1972 and it had to be an innovation in glass, not surface or anything like that. That sort of made it possible. And Corning was the one that sort of did much of the work to make it manufacturable. And so one of the things that's surprising to me is the interplay between all the different fields. And I think sometimes we're myopic on just computer science in this part of the world, but many of the innovations are a combination of different fields. And so your example is a great example of crispr. And I think there are many examples where you come up with it's the GPS chip in the phone with navigation that makes a bunch of things possible. My fascination has always been, I grew up in New York City and there are a bunch of services that were possible in New York and they were not possible anywhere else until everybody had a smartphone. So I thought that that was quite interesting. And the way my son learns math today is very different than the way I learned math. The way you can visualize things. I was like, oh, I wish I'd learned it that way because it just was so much more enlightening to see it and see things in rotation and the graphics that we are capable of producing today. I think the sad part is that we're not reinventing education fast enough, given what is possible today. You know, there was an article that I read about why we're not producing enough. We're not producing Einstein's anymore. Basically the gist of the article was for a long period of time, people had more personalized education. They had their own, not personal tutor, but teachers would just spend more time and tutoring the child and giving them custom work. And we don't do that anymore. But I think AI has the capacity to do that for the world, which would be great.
That's an amazing question to end on. And I guess maybe just one last one. What is the best way that SVC members can stay in touch with you and support you.
Stay in touch. My email is lyn L. I nikoiacap.com, feel free to just email me, support me whenever you want to come talk to us. We're open for business and we have a seed fund, a venture fund, the growth fund. We invest from idea to IPO and beyond. And I wish you all the best of luck in the companies that you create.
Amazing. Thank you for joining us.
More from Alfred
Sequoia’s Alfred Lin explains why your startup should focus on being different rather than “better”
Alfred Lin from Sequoia Capital | Advice for founders, future of consumer social, and more