In this video, the hosts discuss the recent jump in U.S. mortgage rates, which have surged back above 7% after a brief dip. They explain how this rise affects land investors, especially on the disposition side. Higher rates make traditional bank financing less attractive, pushing buyers toward all‑cash offers or owner‑financing arrangements where the investor acts as the lender. The speakers outline how to structure owner‑financing deals, the possibility of flipping the resulting promissory notes to note investors, and the tighter qualification criteria those investors now apply. They also note that rising inflation and oil prices can motivate sellers to liquidate land assets, creating acquisition opportunities. The overall advice is to adapt strategies—price aggressively, use owner‑financing judiciously, and consider note‑flipping—to stay profitable in a high‑rate environment.
Chapters
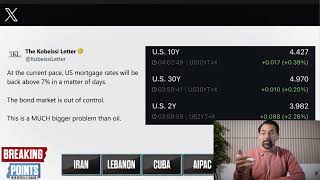
a completely different era for the US. And we put up F1. There had been some hope. Mortgage interest rates had been coming back down to earth. Hope— there was some hope that people who were locked into their mortgages would be able to start— would be able to sell, that people who've been waiting forever to buy a house would be able to buy. In the last couple weeks, we're now surging 7% again. You know, could be, could be in sight if, if these trends continue. We're up over, back over 6%.
Damn, 7% in a matter of days. This isn't the best news to see as a real estate investor and how this affects us on the land investing side. Think of it more so on the disposition side when we're looking to sell something, right? Because ideally we would want an all-cash buyer and we can close within 2 to 4 weeks. That would be fantastic. There are also people that are going to be leveraging financing, normally traditional financing, right? So leveraging a bank through, let's say, Farm and Credit. And those are going to start to decrease because the interest rates are going to be higher. Now, people are going to be turning to us when they are looking to buy something, and they're going to want to leverage owner financing. And if you're unfamiliar with owner financing, we are essentially the bank, right? So we negotiate with the end buyer, we determine what the down payment would be, what the interest rate is attached to that and what the monthly installments would be. And then we essentially act as the bank if they are unable to fulfill payments. Now, ideally, like that is still a good strategy, but ideally, we would want to flip it and then just get all cash back and then be able to rinse and repeat. Now what we can do in a situation like this, if owner financing is the only play that we have, we could do owner financing and flip the note to a note investor as long as everything fits the criteria of what the note investor is looking for. And those restrictions are normally going to be, or their qualification process is normally going to be a little bit tighter when we see stuff like this with interest rates starting to increase. Now, another common concern right now is overall inflation, right? So price of oil that's increased. And when oil increases, there's fears of just groceries, everyday living expenses, energy is going to increase with cost as well. Now that's something that's going to benefit us as land investors on the acquisition side, because people are going to be more motivated as well too, in wanting to liquidate their assets. To have more capital readily available just to handle daily life or do whatever else that they would want to do with that capital. So this isn't the best thing to see, but at the same time, as long as we are smart with our strategy and we price aggressively, we'll be in a good spot.