The Plan B Playbook
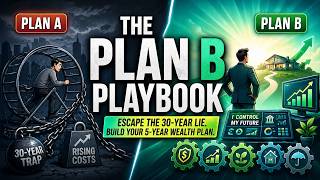
A financial framework called the Income Snowball claims to make you work-optional in 5-10 years by building cash-flow assets while paying down debt, without needing extra income. The system promises your first passive income stream in 45 days and walks through a four-step roadmap: eliminate risk, use leverage wisely, find high-return assets, and build cash-flow systems.
Chapters
Okay, let's dive right into this explainer. If you're a busy professional, you know the drill, right? Save your pennies for 40 years, cross your fingers, and just kinda hope your 401 survives the next market crash. Well, what if there was a rock-solid Plan B? Today, we're exploring a totally fascinating framework designed specifically to help you build a reliable income stream right from scratch. So, the big question right off the bat: Can you actually build a Plan B income stream with absolutely zero savings? I know it sounds crazy, but the TARDIS Wealth Strategies framework we're unpacking today says yes. They're literally challenging everything we're traditionally taught about money, arguing you absolutely do not need a massive pile of cash to start generating passive income right now. Look, the traditional path is honestly just a slog. You scrimp, you save for decades, and you're told to pay off every single dime of debt before you even think about investing. But the TARDIS approach? It completely flips this paradigm on its head. By building assets and paying down debt simultaneously, they claim you could become work optional in just 5 to 10 years, even if you're starting completely from zero. Here's our step-by-step playbook for today: we'll cover the need for a Plan B, unpack the Income Snowball, look at spotting and avoiding risky investments, break down the actual steps to passive income, share some real professional success stories, and finally, talk about achieving work optional status. Alright, kicking things off with Section 1: The Need for Plan B—Why Busy Professionals Need an Alternative. You know, this strategy isn't for day traders glued to 6 monitors. It's really engineered for you. Maybe you're a high earner who's frustrated by an underperforming 401. Or, actually, maybe you're making a great salary but still feel totally trapped by consumer debt and a lack of savings. The point is, you need a reliable Plan B that that doesn't force you to wait 40 years to finally enjoy your life. Moving right along to Section 2: The Income Snowball Explained. This is the engine of your Plan B. So the central engine driving this whole thing is what they call the Income Snowball. And look, this isn't just some catchy buzzword. It's a patented framework originally built by a USC lawyer and Harvard mathematicians who ran something like 72 iterations to perfect it. The secret sauce? It uses your existing monthly cash flow to generate income while you pay down debt at the exact same time. And the best part is that this engine multiplies your cash flow without forcing you into a second job. No way! You don't have to drive an Uber on weekends, flip houses in your precious spare time, or lose sleep stressing over stock market speculation. It's designed to effortlessly use the money that's already flowing through your bank account. Which brings us to Section 3: Spotting and Avoiding Risky Investments. Basically, protecting your wealth. Now, to make the income snowball actually work, you've gotta dodge some major financial landmines. That means stepping off the absolute rollercoaster of the traditional stock market and definitely avoiding risky real estate flips that just turn into full-time jobs. And most importantly, it means understanding the massive difference between dangerous consumer debt and smart, Calculated financial leverage. So, how do you navigate around those landmines? Well, the system lays out some specific steps. First, you apply a strict one-question test to instantly weed out bad investments. Second, you build a power team of advisors. And here's the kicker: they have to be strictly aligned with your goals, meaning they aren't just making commissions off your choices. Finally, you take one critical, calculated action before investing to ensure every single asset actually performs. Alright, onto Section 4: Steps to Passive Income: Getting from Zero to Cash Flow. Distilled right from their source material, here is your 4-step roadmap to replacing a paycheck: Step 1: Brutally eliminate risk. Step 2: Use leverage wisely, which, you know, is a massive mental shift from the whole "all debt is bad" mindset. Step 3: Hunt down high-return, low-risk investments. And Step 4: Build out systems that generate ongoing cash flow. Forget crossing your fingers and praying for appreciation. This is all about acquiring real, cash-flowing assets today. 45 days! Let that sink in for a second. 45 days is the average time a member using this specific framework to create their very first passive income stream. I mean, compare that to waiting 40 years for a retirement account to mature. It's a real game-changer. Let's look at some proof in Section 5. Real professional success stories. Take Dan Hansen, for example. Using this playbook, it took him just 21 months to wipe out $85,000 in consumer debt. 85 grand! Now, he's taking that freed-up cash flow and pouring it straight into passive wealth. It's like the ultimate dual-purpose strategy in action. Then look at Michael Bertrand's amazingly accelerated timeline. He generated $10,000 in passive income in just his first 6 months. $10 grand in 6 months! It really proves what is mathematically possible when you restructure exactly how your money moves. And Tom Cantarino proves this works perfectly for business owners too. He had assets, but they were just in the wrong structure. By applying this framework, he hit total financial freedom at just 31 years old. It's absolutely crucial to realize it's not always about making more money; sometimes it's about restructuring the whole shebang you already have. Finally, Section 6: Achieving Work-Optional Status: Finding Your New Timeline. Based on the data from thousands of households using this playbook, the average maximum time it takes to reach complete financial independence is just 10 years. Yep, 10 years to become entirely work-optional. That completely shatters that standard 40-year corporate grind we're all taught to just accept, doesn't it? So, as we wrap up this explainer, I want to leave you with a real thought-provoker. What would it actually take for you to walk away from your job today? Think about it. If the traditional playbook just has you stuck working harder for your money instead of making your money work for you, well, what is your plan B to finally become work optional?