Simple Budgeting Strategy to Become Financially Free
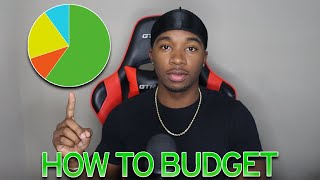
Josiah Stewart breaks down a five-account budgeting system: 60% for bills, 10% for emergency savings capped at six months of expenses, 20% for investments like crypto or stocks, and 10% for guilt-free spending. The percentages scale automatically as income grows, letting you upgrade your lifestyle without overspending.
Chapters
What is goodie, my people? We are back again with another gem. Listen, today I have a strategy that I'm very excited to share with you guys that I personally believe will help a lot of people regardless of your age, regardless of how much money you make, regardless of where you live. I believe that this strategy will help a lot of people become financially free and get out of the rat race. So if you're excited for this video, make sure you smash the like button, subscribe, and hit the post notification bell because you're gonna want to be notified whenever I drop these gems. These are the type of gems that I've explained to you guys multiple different times. They're the most valuable gems in the entire world, the type of gems that you literally would hire a hitman to kill your grandma's best friend just to find out where she emptied her freaking life savings at, so you could therefore go and steal her life savings and invest into the things or the gems that I'm explaining to you guys. It's that serious. So hit the post notification bell and let's just hop right into this. Wait, before we hop into the video, I have officially released my Crip Fire Academy course. Thingy. It's literally a whole course that takes you from step 1 to step a million if you know absolutely nothing about crypto, or if you're even in crypto as of right now and need to learn more information, whether it be the psychology of trading, whether it be how to read charts and do technical analysis, how to find coins before they 100x, 1000x, million x. This course is literally for you, and this is really the perfect time to get this course because if you've been keeping up with the crypto market, it's been down pretty nicely, and that means everything is on sale. So this is the perfect time to actually start building a position in it. And how are you going to build a position in it if you don't know what's what the heck it is. I have a solution for you. Cryptfireacademy.com, go check it out, you know what I'm saying? Great information in there. Also, my Patreon is doing great. I just called a call out yesterday, we're up 40% overnight. That means you went to sleep and woke up 40% richer than you went to sleep, which is great. So if you are interested in knowing every single thing that I invest in, everything I buy, everything I sell, when I'm taking profit, when I'm researching a new coin or anything like that, patreon.com/juviasgems. All the links are inside the description And without further ado, let's hop right into this. Before we hop into this, you guys have to understand one thing. I've talked to many people about this. People hit me up all the time asking me like my strategy for budgeting and how do I save money or how do I have money to invest? And it makes me realize something, right? People overall end up spending as much money as they make no matter how much money they make. Somebody that makes $60,000, if they get a raise and start making $80,000, they'll somehow end up spending that $80,000 as if they never had the raise. They could have been living perfectly fine at $60,000. They had a nice house, nice car, whatever the heck they had, you know what I'm saying? But as soon as they get a raise, they end up filling up that gap. It's like the shark analogy. You guys probably heard it before. It's like if you put a baby shark inside of a shark tank or a shark bowl, it'll only grow as big as that shark bowl. But if you put it in the ocean, it'll grow up to 8 feet or whatever the heck they say. But it's really the same thing when it comes to people and spending money. People can make millions of dollars and still live paycheck to paycheck if they don't have this simple financial mindset down pat. And that's kind of what I'm gonna be getting at in this video. I'm gonna show you guys a whole chart that I made, and it's kind of gonna help you guys kind of keep yourself in perspective while also allowing you to up your funds for certain things when you make more money. So let's hop right into this chart. So for this strategy, you'll need 5 bank accounts, and I'm gonna break down what all these 5 bank accounts are. The first bank account is what I call your business account. That account is, no matter if you have a business or not, if you sell products or not, it's literally just where all your money goes. So all the money that you make, whether it be from your salary or let's say you have other streams of income, all that money goes into that business account. And as soon as that business, or as soon as that money hits the business account, I should say, then it's funneled into these other accounts. You have a bills account, you have an effort account, you have an investment account, you have an emergency account. Keep in mind, I have numbers next to all of these different accounts and these are percentages. You don't have to use these exact percentages. It is a good base number to start off, but I'm just gonna use these percentages just for now, just for the example. You see bills account is 60%, effort account is 10%, investment account is 20%, and emergency account is 10%. So let's hop into what all these accounts are for and how you're going to use them and how you allocate funds into them. So your bills account is the first one that we have to start off with. You have to basically do the calculations on what are your actual expenses, right? Before you start any of this account stuff or the percentages stuff, before you can say how much percentage is getting put into any of these other parts of the circle, you have to know how much money is needed in your bills account. This is different for everybody. So what you have to do before starting all this is calculate your actual expenses. I'm not talking about your shopping spree expenses. I'm not talking about your vacation expenses. I'm talking about your bills, your necessities. I'm talking about your food. I'm talking about your rent, your, health insurance, your car insurance, your car note, all the bills that you have to pay in order to live, that is the amount that you need to have in your bills account. So let's say you make $100,000. Let's say you make $60,000. Whatever amount you make, you could be making $1 million. This all applies, right? So let's say you're making $60,000. You're taking 60% of that every single time you get paid that $5,000 a month. You're taking 60%, of that $5,000 a month and you're putting it straight into that bills account because you made up and you did the calculations and you're like, all my expenses are below 60%, 60% of my whole salary per month. And that's a good number to be at. You really shouldn't be too much higher than 60% of your salary. You should not need to spend 100% of your salary in order to survive. If that is the case, you need to descale your life and kind of reel it in a little bit. You know what I'm saying? You're living too lavish, but do whatever the heck you want to do at any point. I'm just, I'm just, I'm telling you my own personal advice. But back to what I was saying, once you figured out you can live on 60% of your salary, every single time you get paid, whatever amount it is, even if you got paid $10, instantly put 60%, which is $6, into your bills account. And that account is used to pay all of your bills. You're not taking it to that bills account and putting it into your emergency fund account or your investment account or your effort account. That's specifically only for bills and only use it for bills. Next, we have this emergency account. If you guys have heard me multiple times trashing savings accounts, I think it's the stupidest thing in the entire world. I hate when people say, oh, I keep putting money into savings, I got, I got a big savings account. What is it for? What are you saving for? You know what I'm saying? There's a complete difference between an emergency account and a savings account, and I'll explain what it is. An emergency account caps out. It does not go on forever and ever. There's not infinity. An emergency account for me is different for you, whatever you feel safe with, but for me It's 6 months. I need to have 6 months of living expenses kind of saved up and locked away that I don't touch. I'm not going in there to buy new sneakers. I'm not going in there to pay bills unless like I have to and it's an emergency. I lost my job. That's what the emergency account is for. You need, let's say $20,000 is the number you say. Once you reach $20,000 in your emergency account, stop putting money in there. You don't need to add more money in there because that is your 6 months of living expenses. Don't waste money putting more money inside of your emergency account unless your expenses rise. Let's say at first you needed $20,000 to live for 6 months, but then you started making more money and now you need $25,000 for your emergency account or to live for 6 months. That's cool, but once it reaches that $25,000, you cut that out. You're not funneling money back into that emergency account and kind of just making an everlasting emergency account. That's kind of where you would put your investment account money at. Now let's get into the investment account. It's literally what it says. It's an investment account. You're putting money in there to invest it. You're saving to invest. I have no problem with people saving to invest. But when you just tell me you're saving and you're saving and I ask you what you're saving for, you say you're saving for a rainy day. That, that, it rains like 3 times a week. You know what I'm saying? What is you, it's not a rainy day. You know what I'm saying? Like realistically, money should be going into your investment account From, and you see I put 20% here 'cause I kind of prioritize investment accounts 'cause the investment account is how you'll end up making more money. So then you could put more money into all of these different accounts. But like I was saying, you have a savings account or an investment account for better terms with a goal in mind. So you're not just throwing money in there for no reason. You're throwing money in there to save up to buy an investment property. You're throwing money in there to save it to buy a car, to put it on Turo. You're throwing, money in there to save up to start a business, whatever it is, you're constantly putting money in there and that money is not gonna stay in there. That money is to be used to buy something else. So when you're starting this investment account, you can obviously put money in before you have a goal of what you have in mind that you wanna invest it in. It could be crypto, it could be stocks, it could be a business, it could be property. It's literally completely up to you. But like I said, you could start off by not having a goal for what you wanna spend that investment account money on, but you should get a goal as fast as possible so that you know Okay, I now have $5,000 in my investment account. I can now put a down payment on this Tesla so I can now go and start using that Tesla for Turo and renting it out to people and generating more streams of income. So investment account is a savings account with a goal. Don't have a savings account with no goal because you're literally throwing money away at that point. And now next is this, my favorite part, the effort account, right? It's literally what it says. I made up all the names of all these accounts if you did not know. This is not like a legal term or anything like that. The effort account is literally exactly what it looks like. It's money that you put in there that you can spend on whatever the heck you want to spend it on. This is the money that you can burn. This is money that you can waste on freaking a Bugatti. You could waste it on a Rolex. A Rolex ain't a waste if you get a good one. You could waste it on literally anything though. I'm saying this is that, that account where you don't care how much money you spend of it because that's, that's your money to spend. There's no guilt in spending any of that money. And I feel like everybody needs an account like that. Everybody needs some money where they don't feel bad about spending money. A lot of people go through life and if they spend $300 on a pair of sneakers, they're going to be kicking themselves. They're like, dang, I need that $300. I could have spent that on this. I should have spent it on this. But if you have it in your effort account, that means you already allocated all the money into all the other accounts and this is the money that you have earned to treat yourself or treat your spouse or treat whoever the heck it is that you want to spend that money on. So, that's really a simple plan. You have to understand with this plan, it's great due to the fact that it grows. It's not a fixed number. I'm not saying put $10,000 in the bills account, put $50,000 into the emergency account, put this amount into an investment account. It's percentages. So that means when you start making more money, those percentages, even though it's the same percentage, the amount that you're putting in grows. So that means your bills account grows. So that means when you start making money, you can get a nicer car, you can get a nicer house. It's not limiting you to living at the same point that you started at. Let's say you made $60,000 now, but now you're doing really great and making $200,000. You can still have all these different circles and still be responsible with your money while still being able to upgrade your lifestyle. A lot of people say to live below your means, and this helps you live below your means at all times, even if you're growing what below your means means when you're making more money. Because at the end of the day, you're still doing the same thing. You're still being smart and having an emergency fund. You're still being smart and having an investment account that's making you more money. You're still being smart and covering all your bills. You're not behind on your bills. You're not getting into a whole bunch of debt. So that's why this is great, using these percentages versus using a fixed number. It's something that I've recommended for a lot of people. It's something that I did, and I've explained this before. If you can't get a bank account or if you don't have a bank account, use envelopes, use a drawer. If you have 5 different drawers, put it into 5 different drawers, put it into 5 different envelopes, but make sure you're actually separating it. The same thing with a bank account. Just don't think that you can just have one bank account and keep in your mind how much you're supposed to spend on this, how much you're supposed to spend on that. Get different bank accounts so it's very simple and you automatically know where to funnel it out of once it hits that business account that I was talking about. But that is the end of the video. Let me know what you guys think. Let me know if you guys have any questions when it comes to it. If you guys need help on how to set yours up, I can try and give you guys some type of advice. But I'm not a financial advisor. Y'all should know this by now. But feel free to hit me up on Instagram if you have any type of questions at all. I really like helping people out with their finances or giving people advice, I should say, when it comes to their finances. So I have no problem answering any DMs if you guys have any DMs. Also leave a comment down below if you have any questions as well. Let me know what other videos you guys want me to go over. I told you guys in the last video where how I, well, I told you guys how I made my money. I suggested that I could do a budgeting video A bunch of people hit me up and said they wanted the budgeting video. So now I'm making the budgeting video. Let me know if you guys want me to kind of give you guys, I can give you guys advice on different investment stuff. Let's say you have your investment account growing and you don't know what to spend it on. I can make a video giving you guys the best 5 side hustles or whatever it is. Y'all let me know in the comments down below. But subscribe if you're not subscribed already. Smash the like button, hit the post notification bell so you're notified whenever I drop these gems. Y'all know how valuable they are. I don't gotta talk about nobody's grandma. Right now. But, um, yeah, good luck on our trades, looking on your crypto, good luck on your jobs, good luck on your, your accounts, good luck on life as a whole, man. And I'm gonna see you on the next video.