Nik Storonsky, Revolut Founder: What Revolut Needs to Do to Hit $100BN Valuation | E1233

In this interview, Revolut founder and CEO Nik Storonsky discusses how the company operates as a KPI‑centric organization, his philosophy on hiring and managing a high‑performing team, and the painful lessons learned from scaling with professional managers. He explains Revolut’s product‑bet framework, highlighting successes (eSIM, RevPoints) and failures (salary‑advance), and outlines the criteria for launching new bets. Storonsky compares the UK and US capital markets, arguing that US listing is more rational due to lower transaction costs, and describes the regulatory challenges of obtaining banking licences in the UK, US, and LATAM. He shares insights on crypto strategy, the importance of brand marketing, and the company’s aggressive geographic rollout (Europe, US, LATAM). The conversation also covers his data‑driven investing initiative “Quantum Light,” cap‑table control mechanisms, and his personal leadership style, including work‑life balance, decision‑making under pressure, and long‑term vision for Revolut (50 markets, 30‑40 M daily active users, private‑banking offering).
Chapters
I just don't understand how the product which is being provided by UK can compete with the product provided by US. It is less liquid, so it's much worse compared to US, plus it's much more expensive because you pay stamp duty, right? So, it's like, it's just not rational.
And so you would list in the US?
I consider myself a rational person, right? If I get a better product from UK, I will list in UK. But so far, if you just compare these products, I mean, one is far ahead compared to the other.
Ready to go? Nik, I'm so excited to do this. Thank you so much for having us in your office first.
Thanks for coming.
Not at all. Listen, I was chatting to Klaus Hommels before, and he said, you know, I'm not going to do the German accent because I'm terrible at it, but he said that Revolut is one of the most KPI-led companies. And so I just wanted to start with, How do you approach KPI-based leadership and what does that actually mean?
Well, basically it's the whole goal setting, right? So we set up the goals for the company. So usually we have 5, 6 goals a year and then we quantify these goals. So what does it mean to achieve a certain goal? Then we cascade these goals on the department level, then on the team level, and then on individual. So every single effectively team, department, and on the company, We have metrics describing the performance and then all people go through performance review process every quarter. Then they're judged based on the metrics that they delivered, their skills, and then cultural values.
In terms of the management, when you get the metrics, how do you think about distributed management? I spoke to a lot of your team and you have a lot of direct reports.
Yeah.
How many direct reports do you have and how do you think about distributed management?
So, we've got 40+ reports. I mean, to be honest with you, I build a team already for last 5 years. So, generally because I don't really work with people who are not excellent. Another way I define people who are excellent, strong, average, or below average is pretty simple. So, they should be like a self-guided missile, right? So, excellent people, they select the goal themselves, then they press the button, then they reach the goal themselves. Strong people, you need to show them the goal and they reach the goal themselves without you iterating with them. Average people, you need on a weekly basis iterate to reach the goal. And then below average people, I mean, you iterate with them, but, you know, sometimes or very often they don't reach the goal. So the key is to select all your direct reports either strong or excellent, so they're able to reach the goal themselves without you kind of directing them.
Will they be excellent on day 1 and how long do you give them to get good enough?
Well, majority of people, you see them performing strong or excellent after 3, 4 weeks, right? So they hit the ground running on week 3. Majority of them, they actually probably on week 1. So generally, if you see a person is not performing for 1, 2 months, most likely they'll not be performing for the next year. So I don't really believe in kind of, you know, needing some time to adapt, to speed up. So if the person is not delivering within the first 3 months, most likely they will not.
What are the most common ways you find them not delivering in the first 3 months? Like, what are the most obvious signs?
Well, you just give them the goals, right? And then you have some weekly or biweekly catch-ups and then they show you what they produced. And then you just observe what they produce for 2, 3 weeks, how smart they are, how deep they go with their analysis. It's just based on what they show you.
Do you agree with when there's doubt, there's no doubt?
When there is doubt, there is no doubt. Yeah, 100%. I mean, as soon as you start doubting, I mean, there's no doubt.
In terms of the different people, I love that kind of spectrum from like, you know, excellent to strong to average. I chatted to, I mean, your Alan Changs of the world, but so many who work with you and have worked with you. And they said that what you look for in people has changed a lot over the years. You used to like, not like the management consultants and the investment bankers. And now you've got a lot more professional management. How do you think about that? And is that fair?
I don't think it's fair, right? Because I was always looking for people who can deliver, right? So I was always execution-oriented rather than talk-oriented. Because if you look at all these management consultants, they come to you with a nice presentation, explain you how to get things done. Reality is when you start hiring management consultants to help you run the company, that means your employees are not competent in what they do, right? And for me, it's a bad sign.
Should employees compete?
Should employees compete?
Yeah. You said that.
With each other?
Yeah.
No, I don't think so. I think they should collaborate. They should work as a team. They should work on common goals.
Can I ask, when you look back at the growth of the team in particular, what was the most painful scaling bit and what did you learn from that?
Well, I think, you know, I made a lot of mistakes scaling team and I think the most painful mistake was believing, well, I never believed it, but I was forced to believe that, you know, in order to scale the company, you need to hire experienced professional managers. That's a dead end. I think I hired like, you know, 55 through executive recruiters, paid like, you know, $2 million in fees. I ended up, you know, firing 49 or 50 of them. So, it's such a waste of money.
How did you change as a leader? I mean this in the nicest way. You also got a lot more friendly.
I was always friendly.
You're always friendly?
Yeah, but you feel more comfortable with media. Well, yeah, probably because, you know, I, I know by now I have a lot of experience speaking on media. Yeah, but I was always, you know, holding people accountable to deliver, right? You know, sometimes I was communicating more in a harsher way. Or sometimes, you know, in a softer way, but I was always, you know, forcing people to deliver.
What do you think when you look forward now, you most need to work on in your own leadership style? Where are you like, I'm still not great and I'd like to get better?
Or usually when I hired people in a new area that I haven't worked before. For example, when I started Revolut 10 years ago, I was hiring my first head of compliance, head of recruitment, head of people. I'm terrible at hiring first roles. I never kind of, you know, worked before, so I ended up, you know, trying, you know, many people until, you know, I find the good ones. And I learned how to do it now, so every time when I hire a new role which I never hired before, I first interview the whole market, try to learn from people how they do their job, and only after I learn how they do their job, I kind of select the best person for the job. Because in reality, if you never kind of worked with designers, you have zero skills to hire designers. If you never worked in reg affairs or government affairs, you have zero skills to assess who's good, who's not. So in order to first learn the skills, you need to interview as many people from this area as possible. Then you learn and then you'll be able to select.
Can I ask, when you think about the different areas where you invest in, you mentioned that kind of the compliance, the regulatory, do you think the best CEOs are the best resource allocators?
I think so. Yeah. I think the best CEOs can squeeze a lot of IRR out of, you know, very little resource.
When you think about where you squeezed IRR most effectively, what comes to mind first?
Myself. Yeah, I think I'm very efficient into getting people to deliver with small resources. And I'm very cost-conscious as well. So I think, you know, people when they throw money at the problem, they're just wrong people. I think, you know, what really delivers the most is your brainpower, right? When you sit down, then force yourself to think how to solve the problem the most kind of, you know, cost-effective and efficient way, that's actually much more powerful compared to spending millions on, I don't know, external people, external consultants, and so on, or hiring, you know, super experienced professionals for a lot of money.
Where did you spend money that with the benefit of hindsight you wish you hadn't?
Well, I think we're very efficient in spending money, to be honest with you. I think when I look at our costs, I think our top cost is actually marketing now, and then the second cost is people.
Has your idea around brand marketing evolved? You know, before, you're a very data-driven, performance-driven guy. We like seeing what inputs lead to what outputs. And brand marketing is fucking hard because it's like 50% works, but you don't know which one. Has your ideas on brand marketing changed?
I do believe in brand marketing now. Before I didn't. And, but you need to be very careful in what you buy as an asset to show your brand. For example, recently we started buying AirPods. Jetbridges, and I personally believe IRR on it is amazing. But, you know, we clearly cannot measure it. But if your brand marketing is only a very small portion of performance marketing and you can afford it, and then you believe, you know, that these assets are great, why not?
Can I ask, when you think about, bluntly, the expansion to the US and banking licenses, I do want to start on the banking license. It took longer than expected. What did— this one was from Mickey, so you can blame him, not me. What did you learn about building a regulated business from the banking license process taking longer?
Oh, what I really learned is, uh, it's, uh, so whenever you want to build a bank, you'd rather get a banking license before you have customers. So that's, uh, kind of, you know, key lesson because as soon as you have many customers, millions of customers, tens of millions of customers, regulators will be kind of, you know, much more thorough in assessing your capabilities. As a result, the whole license process will take, you know, much longer. And then for smaller banks or for banks who don't have clients, they don't really assess because there's nothing to assess, right? So they grant the license much easier.
Can I ask you though, if you have that status much earlier and you are, say, Monzo, where you did decide to get it earlier, It inhibits your ability to execute on product in such a fast way because you are bluntly encumbered by regulators much sooner. No, like, do you wish you'd done it sooner?
Oh, 100%. No, reality, you can also build their governance process around the products, around all the countries in a very tech-driven, efficient way. So yes, it'll be a bit slower, but I mean, not that slow to be honest here. If you really apply, uh, brains, how to optimize governance, how to build a whole structure, processes, who approves what and when, you can do it much better compared to legacy banks.
And so you didn't because you just didn't. Why did you not earlier then when you reflect on it?
Or I wasn't experienced, right? So I didn't know what is the right way. Yeah. So I did it wrong.
How would you rate your relationship with the regulators today?
It's actually much better, right? Because Again, because I was inexperienced and I had this perception in my mind, which was, well, not forced on me, but confirmed by many, many people, investors, that because I'm young, right, I'm very like, you know, techie, I should not speak with regulators because they will not understand me. Instead, I should hire some gray-haired banking CEO who who've been in the business for a long time and that they need to speak with regulators. What I really found is actually very bad advice, right? Because whenever you speak with regulators yourself, whenever you explain exactly in plain English what we do, how we do it, because you build it yourself or I build it myself, right? I can explain it in very simple terms. And because we are also innovating a lot in this area as compared to legacy banks. And you show data as well that our results are better compared to legacy banks. That's in the end what matters, right? If you show data, you show that that's how you've been like, you know, 3 or 4 years ago. That's how we do now. That's how other banks are doing. We are ahead of them. That's what matters. The problem with traditional banking CEOs, they're not tech-driven at all. And then they'd rather speak in very vague, jargon to hide, uh, their incompetency or their limited knowledge in, in tech-related, uh, matters. So regulators, I don't think they like it.
What have been your biggest lessons around crypto, Nik?
Biggest lessons around crypto? Uh, never speculate in crypto.
Have you changed your mind on anything in crypto? You made the decision to include crypto early. How do you reflect on that now?
I think it's a good decision. I think, because reality, a lot of use cases in crypto is still speculation, right? People, I mean, speculate is more, I would say, entertaining for them. But then some use cases are definitely valid. For example, stablecoins or enabling instant money transfers through stablecoins, competing with SWIFT on corresponding banking system. Yeah, it's, it's actually very valuable.
What's been the biggest challenge with the crypto product?
There were quite a few. I mean, really, probably biggest challenge is different licenses in different countries and then different rules attached to these licenses. I remember when we received our crypto license several years ago in UK, there were certain rules attached to it, which actually caused kind of 99% false positive. So for example, a person wants to send money in crypto. To another account, and then we would block this transfer because of certain rules imposed by regulator. But then in 99.9% of cases, we were wrong, you know, blocking this transfer because I mean transfer is was okay, right? It wasn't fraudulent, wasn't. So it took us, you know, some time to explain to regulator, show data that these rules that you impose on us are actually wrong rules. We should kind of optimize it, and then we can. capture, you know, more kind of fraudulent transfers and then not waste time of, like, innocent people.
I totally get you. You mentioned that kind of the different regulatory elements. You moved, like, added the US as another geography. I never understand the US, Nik, if I'm honest, because like, I mean, the thing I love about Revolut is Revolut is the one company from Europe that shits on its US counterparts. Like, Chime is the biggest player in the US, which is like a quarter of the size of Revolut. Which is completely unique. Why has no one been able to win US neobanking? I don't understand that.
Well, I think in US, first of all, so there is a culture in tech companies, they don't want to be regulated. Because they don't want to be regulated, they need to partner with a bank to use their license and use their platform. As soon as you partner with a bank and use their license, use their platform, you need to follow their processes, which are not automated. which are not built as a product, it slows you down. Plus on top there is compliance of the bank that needs to approve every single screen, every single marketing material and so on. And because they are not very efficient, it slows you down. Plus because you're not a bank, you're not able to use your balance sheet or your deposits, so you cannot really do credit cards efficiently. And the US is credit-driven market and whatever a customer spends with a credit card, bank receives actually much more money from a merchant compared to debit card. And banks, they effectively spend part of this interchange to do, to give additional benefits to customers in air miles or points. As a result, credit cards are much more attractive for customers compared to debit card. Well, as a result, you see fintechs purely partnering with the bank issuing debit cards, just not very attractive value proposition.
So, what When we think about going into the market, it's been hard. What's been harder than you thought, and what's been easier than you thought?
I mean, 99% of things were harder than I thought.
Yeah, the few things that were easier were things that actually don't matter as well. Nothing in life that's, like, meaningful is easy.
Yeah, nothing is easy.
Do you think the Revolut brand is strong in the US?
Not yet, but we will get there. As soon as we get banking license in US, launch a bank there. It will take time, but I think, you know, we can get where we are now in Europe, in US.
I saw your talk with Antoine, not Antoine, Martin, sorry, at Index. And you said about the US banking license, is that now? Like, how do you think about the staging of the US rollout and the banking license there?
So basically, first we need to roll out our UK bank, so go through all this mobilization And then put our UK customers on the bank. As soon as we get it done, it actually unlocks us or our ability to apply for license in the US.
What will you do to win the US in a way that people who've tried before haven't won the US with?
People in the US never tried their digital bank with a credit card, with all the functionalities that we have already. So one simple app where you have all the financial services that you need. to spend.
Do you think Monzo did?
Uh, Monzo still are not in the US as far as I know.
I mean, they expanded there, just didn't work.
Didn't work. Okay. Yeah, maybe. Maybe I'm not up to date on Monzo.
Don't worry about it. I asked them and it was a bit of an awkward conversation. Um, so I totally get it. You're also in LATAM and crushing there. How do you feel about the LATAM market? What did you do that worked really well?
Now what we've done, we applied for license in Brazil, for banking license in Brazil. So we got a banking license in Mexico ahead of Nubank. We, I think we applied already in Colombia for banking license. So we're working on Peru as well. Basically trying to capture like in the top 4, top 5 markets and launch.
Can you do North and South America at the same time?
Yeah, you can parallelize. I mean, it's hard, but almost anything is possible.
When you look back at the products, what product introduction that you made has been the biggest needle mover?
I mean, the reality changes. Like 3 years ago or when we launched, or 5 years ago, business accounts already, you know, went very well in terms of growth. But then recently we launched also, I don't know, eScenes growing super fast, RevPoints growing super fast because our scale is so much larger compared to 5 years ago. So whenever we launch product on market with the right product-market fit, it just scales super quickly. So you cannot really compare with also very successful product we launched 5 years ago because yes, 5 years ago it was super fast, but if you look at speed of growth now, it was very slow.
What product did you think would be a mega hit that wasn't?
I'm actually pretty bad at this. Like every time when I think on certain product that it will be a mega hit. It's not. And sometimes when I'm, well, when I think it will not, it will.
Which one, when you thought it would, did it not, most comes to mind?
Well, for example, we launched salary advance to compete with credit card. So, the idea is a person just, well, receives salary in our account and then halfway through the period, for the salary, they press a button, they receive half of your salary. So it's pretty cool. So it competes with credit cards and it competes with loans, much cheaper as well. But it didn't work for us because the whole conversion funnel was very bad. First you need to sell to enterprise, then enterprise needs to sell to their employees. You also need to sell into payroll systems. So if you look at conversions, I mean, for a lot of effort we ended up having, I don't know, like— 1%. 100+ people using a solo hotspot. So we decided to just set it up.
Well, this is the hard thing when you get to your scale, which is like, it just has to be meaningful and there's opportunity cost to everything that you do. You know, I always chat to Anton and he's like, oh man, it needs to be 10x. It needs to be 10x. How do you think about what is worthy of your time in terms of new products, in terms of size?
So usually to launch a product, you need to have a very small team of 10 people. They will work on the product for say 1 to 1.5 years. Cost will be probably, I don't know, £2-3 million. And because they're all independent, you can run a lot of bets independently. And so the way we think about what to launch, what not to launch, we just have a committee of people who've done it before, who launched products before, and they have an opinion. And so when everyone is positive, we launch things. When everyone is negative, we don't launch. If there is a mixed opinion, we still launch.
How many bets do you have running at a time?
20+ in parallel.
20+ bets?
If you look at the last 2, 3 years, we launched, I think, 27 bets.
Okay, so you have 20+ bets running at once. And then what percent make it?
So usually, so out of 27 bets that we launched last 2.5, 3 years, like amazingly worked probably Let's say 5, 5, 6 didn't work at all. And the rest are just, you know, somewhere in the middle. But if you look at the whole portfolio, how much money it generates, it's just amazing. It's exponential.
Okay, so with the 5, 6, because the 5 that work, you're like, great, let's give them more money.
Yeah, you kind of scale it up, yeah.
How much more money do you give them all the same?
Does it— The way it works, so you've got the team, then they launch it, then you look at how much money they generate. After they launch the product, month 1, month 2, month 3, month 4, you compare it with other bets when you launched it. And then say top 30, 40%, if you have, you know, growth stick, you just allow them to hire additional team and additional team. So one team becomes 2 teams, 3 teams, and becomes a department.
Okay, so we have that.
What about the—
and so they're the 5 that work. The 5, 6 in the middle are really hard because you don't want to waste money. There's an opportunity cost to those people. What do you do with the ones where it's like, hmm?
So you don't scale it, right? So you still have only one team working on it. For those bets that are really scaling up, producing a lot of money, you add more people to work on kind of new features for this particular product.
Which one of these bets today are you most excited about?
I like actually eSIM. It worked pretty well for us.
So eSIM?
eSIM, yeah. It's a very nice product. I think it's the best in the market now. It's a beautiful product.
I love it.
Yeah, yeah. So super easy, you know, compared to all other kind of standalone apps out there.
Are the winners obvious? Like, do they always just go up and to the right, or does it take time for you to build conviction in what you like?
Surprisingly, they, like, on month 1, month 2, month 3, they always, you know, go up. So you don't have doubts. They have winners.
Do they present to you, like, 27 bets at one time? How do you manage that hierarchy of information decision-making?
So we just build a nice tracking system, right? So we have Jira, obviously tracking every single bet, then everything feeds into dashboard as well. So just open the dashboard and then you see the list of your bets, the list of bets that are being cooked, another 20, which stage are they, like, you know, are they being developed, are they at our kind of approval process? Um, then you see how much gross profit each bet generates and so on and so forth. So it's pretty visual and very clear.
This is gonna sound so random, but Ben Affleck gave a speech the other day about AI in movies, and he said that art is knowing what to build and craft is knowing when to stop, which I thought was a really nice description of, bluntly, the importance of simplicity. Do you worry that with so many bets, you lose simplicity and you get overcrowding?
You need to solve this problem through interface. So interface should be super simple, right? So you need to show the right product at the right time. If you look at the car, right, car has, you know, a lot of functionality, but then it's pretty simple, right? And then on top of it, we've got electric cars. Like screens. I mean, if you think about functionality of the car, there's a lot of, yeah, right? But then it's, it's very simply built. So you just drive where you want, you play music when you want, and so on. So the same with banking product. I mean, ultimately people need a lot of products, but then if you position everything in a very simple way, then there is no problem.
Which product would you most like to do that you haven't done?
Private bank. I think it'll be pretty cool to build a private bank.
Agreed. Why haven't you done it?
I think it was too early. Now we have a lot of customers and then a lot of customers actually have a lot of balances with us. Some of them have, you know, millions in our accounts. So I think it's time to build private banking for people with a lot of liquid assets.
So we have Revolut today, what does Revolut look like in 3 years' time, both from a product and from a business perspective?
So in 3 years' time, we would love to be probably live in 50 markets to be—
Where are we today? How many are we live in?
39 now.
Okay.
Yeah. So we want to be number 1 in, say, 90% of these markets in terms of growth.
How many are we number 1 in today?
I think we are number 1 in 19 or 20.
19 or 20.
And basically fully localized as a bank in, say, 40 markets. So, providing local accounts, local credit cards, local payment methods, loans, and so on. So, just be as competitive as local banks. Or even, you know, more competitive. So that's the goal. And then hopefully to have, I would say, 30 to 40 million daily active people. So now we're here, we're around 10 million daily active people.
So we have that in 3 years. Which market is the most important that you win?
I think in 3 years it'll be too early for us to win. So yeah, maybe if we win every single large market in Europe. So top 10 markets in Europe, yeah.
Okay.
And then right now we have our penetration of market share, I would say it depends from 5% to sometimes 70%. On average, I would say 10%. So if we manage to go from 10% to 30-40% market share in our top 10 markets, so that will be already probably 4x business compared to Do you think the market makeup of banking will fundamentally shift in the next generation?
And what I mean by that is I saw actually your, again, talk with Martin and you said about the huge fragmentation in the banking market.
Yeah.
Do you think that will continue or do you think we will see, bluntly, a lot more concentration with fewer bigger players?
Yeah, I think because of different regulations, different markets, all the banks are very local, right? Because it's very hard to kind of, you know, build a bank in one country and then scale it. Outside without proper tech. So I think we have as a company we have a unique opportunity to actually scale and build a global bank across many many markets purely because tech allows us to do it. Actually, if you think about it, a similar similar picture was in venture business, right? So when the venture business started, you have a lot of you know VC funds. focused on the US, some VC funds focused on Europe, a lot of VC funds focused on Asia and so on. So they're very similar to banking as well.
And so we move into a world of globalized banking players who own, bluntly, much larger positions.
Yeah, I think, uh, with time, in 5 years' time, you'll, you'll see much less number of banks and there are few global players.
Nik, what needs to change in the business before you go public?
I mean, in reality, we already run the business as a public company. We're just not a public company. So we run everything because we're a bank. So we need to have even stronger controls compared to public companies.
So why would you want to go public? You know, we saw Databricks do this secondary transaction. I think yesterday it was $6 to $8 billion of liquidity to investors and to employees. You know, obviously Revolut publicly done the secondaries. Why would you want to?
Well, we still have a lot of VC investors, right? But sooner or later, we'll want to kind of, you know, sell their shareholdings and return money to investors. So I think public markets allow you to have more liquidity compared to just private markets.
There's no way this is going to get kept in, but I have to ask it.
Sure.
Would you list in London?
Would I list in London? I mean, problem with the UK is if you think about UK versus US, UK is much more liquid, right? And then trading in US is free, right? If you look at trading in UK, you always buy a stamp duty tax, which is 0.5%. So I just don't understand how the product which is being provided by UK can compete with the product provided by US. It is less liquid, so it's much worse compared to US, plus it's much more expensive because you pay stamp duty, right? So, it's like, it's just not rational.
And so you would list in the US?
Look, I'm, I consider myself a rational person, right? That's all I can answer. So, unless I have, you know, a better product from UK, then, yeah, if I get a better product from UK, I will list in UK. But so far, if you just compare these products, I mean, one is far ahead compared to the other.
How do you respond to the suggestions that you've moved to Dubai?
Well, I do spend some time in Dubai. Every year. So we've got a large team there, plus we're getting licenses. But no, I don't live permanently in Dubai.
Is the culture different across the world? When you go to different offices around the world, is Revolut a monoculture or are they actually very different independent cultures?
Our culture is the same across all offices. So people are smart, people are hungry, people are working hard, people want to achieve things. That's common across all the cultures.
Can I ask you one on— we mentioned the liquidity to investors earlier. You've been unbelievable at maintaining a really tight control of your cap table, um, where other founders haven't, bluntly. What have you done to maintain such good control of the cap table?
Control it in what?
In preventing secondaries, preventing private transactions, preventing side deals.
Yeah, just because, uh, again, it's pretty obvious, right? As soon as you don't have control, so then every time when you try to raise a primary round, You're competing with all these early investors who want to sell at a large discount because, I mean, they made so much money and they're okay to exit, you know, as soon as possible because they make like, I don't know, like 50x, 100x, right? And it actually prevents company to raise primary as a result because they're really kind of, you know, hurting the company. We had to put all these controls in place.
In terms of competitors that you really respect around the world, Who do you most respect and why then?
Well, like obviously if I look at competition, Nubank is amazing what they do. Well, country is also great, right? There's no competition there and the rates are high. Credit cards have, you know, very high rates as well. So I think, you know, Nubank is very strong. Then I think JP Morgan, you know, have a very good team in the US, so as a bank. Very strong. Well, if you look at Asia, right, so it's a bit different dynamic. So we've got companies like WeChat, so they're very strong. I mean, in reality, there are like many good companies.
Which would be a harder market for you to win, US or Asia?
I think Asia.
Why?
Well, because they don't allow your banking license to trade. In the US, I believe there is a large challenge to get it.
It's also a fundamentally different UI that they're used to. I mean, it's an entirely new product paradigm that you have to engage with. Culturally, it's not nearly as aligned as US and UK. So I totally get that. You must have quantum light, Nick.
Yeah. So yeah, let me maybe just spend one minute on explaining what quantum light is. So basically, because I was raising money so many times, I've done it like 7 or 8 times. And like almost every time I experienced some very negative experience. For example, I think it was 2019. I agreed a term sheet with investor. I think it was like $7 billion valuation. And then next day market dropped 10%, S&P dropped 10%, then term sheet was withdrawn and then it became like $5 billion or whatever. Then like even recently, like, you know, secondaries that were done, we kind of, you know, agreed everything with all investors and then there was like, you know, market dropped. Then luckily it went back, but we had some investors withdrawing term sheets. Or like when I was raising money for Series A, like no one believed me, no one wanted to invest. I spent like 4, 5, 6 months going through every single investor, then saying them that, okay, it's really great business. They looked at my unit economics and unit economics was negative. Of course it was negative because I just started. Right? It's a volume game. Anyway, what I learned that a lot of investors, they are A, following the crowd very often, and B, they're very emotions-driven, right? Sometimes they like the founder, sometimes they don't like the founder, they don't like the founder and don't invest. So it's not very scientific. So 2 years ago, I set up effectively a small team of data scientists and data engineers who collected a lot of data on startups. And then we trained machine learning models on the startups, selecting the best startups. And then the machine learning model actually amazingly outperforms 95% of VCs out there on backtest. And that's how I started this business. So effectively, I have an independent team of 20 people who are building and polishing data science models. And then models give you a list of companies where to invest. And then we just go to this company and invest.
Where's the entry point? Because you need to have enough—
Series B.
Okay, so you need to have enough data, so Series B. Okay, so you can select the best companies better than investors. Fine, cool. Generally though, if you can select them better and there's data for that, the winners are more obvious.
Yeah.
And so if the winners are more obvious, selection is one thing, but winning is another. How do you think about winning when there's 5 others and you've got Sequoia, And you've got index and you have all the pretty—
I mean, the reality is not that straightforward, right? If you look at companies that model selects and we have, we tested probably like 300+ features, right? Then we selected now like best 25, which statistically give you a signal, right? Whether to invest in a company or not. So the features are like, obviously it's very important who are investors, who is a lead. And the bet of the lead. So we actually track IRR for every single fund. And then based on this IRR, it's an input in the model. The model kind of selects whether to invest or not. Then who is the founder? Did the first step?
Oh, you track IRRs of seed funds?
No, we track IRR on kind of on the fund level for each investor. And then if we see a good investor with good IRR investing, it's obviously like a positive signal. Anyway, model takes, say, 25 features. One of the features we're investing is dynamic evaluation, quality of employees, quality of founder, whether they had a non-standard education. Age is important as well.
Why is age important? What do you find about age?
Well, it's, if you look at statistics, so 20 to 25 is actually quite negative, like too early is negative, then 25 to 30 is okay. 30 to 35 is the best age. After 35, I mean, there is a clear negative correlation with the success. So sweet spot is 25 to 35 for founders at Series B.
Okay, so we have 25 to 35. You said education there and you said investing in education early is important. Why do you think it's so important and do you think our current education system does it right?
Well, I just look at data, right? And then at stats and then statistics. Statistics clearly show that top universities, STEM degree have a much more positive correlation with the success of the company. And obviously it's not for like any other professional there, but particularly for startups. I mean, it is important purely based on stats.
Which was the hardest funding round to raise? You mentioned earlier that, you know, the Series A, for example, you spent 5 months on.
Which was the hardest round to raise? I think our first one was very hard. The first one. Every single one was easier, easier than I think 2019 or, well, we started raising in 2019. We closed, I think, in February or in January 2020, just before COVID We were very lucky, but it took time to close it.
How big was that round?
So valuation was $5 billion, which dropped from $7 billion.
Oh wait, you did it at five?
Yeah, we did it at five. Oh wow, so I had no choice.
Yeah, yeah.
Wow. Yeah.
Okay, so how much did you raise at five then?
I think it was three hundred million. Something like that. Yeah.
Does that work? Because like as a relationship, it kind of dam— like I'd be damaged if you tried to haggle me down because the markets are moving.
Like how? I mean, look, in the end, it's business, right? them. It's business for me and yeah, I mean, we just move on.
Who's your favorite investor?
I have a few favorites. I mean, I've got, you know, fantastic investors, to be honest with you. Like, Matan from Index, you know, very smart. John, TCV, very smart as well. Miki, which you spoke with, from Ribbit, you know, very good.
Has your definition of success changed?
I think if you define success by kind of, you know, percentage of goals that you Reached. That's very simple, right? If your goal is, I don't know, to be happily married with kids and then you reach it, you're 100% successful, right? If your goal is, I don't know, make more money, you haven't reached it, then you're not. It's a pretty simple definition.
Does money make you happy, Nik?
I don't think money makes you happier. I think money is just additional instrument that you can use in order to achieve certain goals.
What do you think you've not achieved today that you most want to achieve?
Well, I haven't won US market, right? I think it's very important to tick this box, especially for European startup.
For sure. Totally.
It's always the opposite, right? US companies, they always win Europe and I almost never see an exception. So I think it'll be very cool to tick this box.
Listen, I want to move into a quick fire round. So I say a short statement, you give me your immediate thoughts. Does that sound okay?
Yep.
So what do you believe that most around you disbelieve?
I think majority of people believe that balanced life allows you to be happy and achieve your goals. I think in reality, disbalanced life allows you definitely to achieve your goals. So more kind of imbalanced you are, more focused on your goals, sacrificing everything else, more likely you'll succeed these goals. And, you know, there is a high chance it'll also bring you happiness.
What period of Revolut's growth have you been most imbalanced?
Every year it's very imbalanced, right? So it's, uh, yeah, it became, you know, much more structured, much more kind of, you know, process-driven.
Um, I get it, dude, but you, you're very thin, you're athletic, you look fresh, you're not losing sleep, you're doing fitness.
Yeah.
Talk to me, what does the next day look like?
Because I, I have so much pressure right now, you know, like a lot of 99% of time is, is a lot of pain, right? Because reality What happens is even if you have organization, then all the unpleasant problems that no one else solves goes into me and I ended up doing all these shitty jobs, right? Solving problems that no one else wants to solve or can't solve. And it's pretty unpleasant. So 99% of time is not really pleasure, a lot of pain, a lot of pressure, stress. And in order to keep calm under pressure, Obviously, you need to have a lot of energy and then in order to have a lot of energy, you need to build your lifestyle in the way that brings you a lot of energy, right? So, it's obviously a lot of sports, you know, like—
What time does Nik get up in the morning?
I mean, depends in which country I am, right? Because the way I manage the business, I work 1, 2, 3 months from different countries, from different offices and it depends which time zone I am, right? For example, if I'm in UK, Like probably I wake up, you know, 6:30, you know, like sometimes, you know, I train in the morning, sometimes not, but then I start 8:30, 9:00 AM. If I'm somewhere in kind of Asia, right, then I start, you know, a bit later or much later, but then I work till, you know, 11:00 PM. If I'm in the US, then I need to start very early, like, you know, Which venture investor do you most respect and learn from?
Just learn from, not like your favorite, like you go out for holidays with, like you actually learn from, first call when you're in trouble.
Well, I call people who've done similar things in the past, right? So who built very large businesses. So I've got a couple of friends who built very large businesses and some of them, they never used VCs. And they just print cash, those businesses. So, I think, you know, in some ways they are much better compared to me.
What would you do if you knew you wouldn't fail?
I would just keep trying things, but then I'm— whenever I try things, I always think I will not fail.
What have you changed your mind on in the last 12 months?
Like, you know, I spent 15, 16, 17 years in the UK and London really became a home city for me. But then when I started kind of working from different cities, I realized, you know, there is so much more like in other cities in terms of lifestyle, weather, infrastructure that a lot of people, because they're stuck in one city, living in one city, they don't really see it and they just become very close-minded. I think when you kind of manage to work or live in many, many places, then you are much more open-minded.
If you were starting Revolut again today, where would you start it?
US, most likely.
If you were advising a young person today coming out of university, what advice would you give them on optimizing their career?
Well, I think they first need to really know what they like to do, what they enjoy doing, and just go into the area, this area. If you enjoy something, I mean, you definitely need to go there.
What consumer brand do you most respect?
I think Apple, to be honest with you. Why? I think they built cool products, they built a cool brand, and they managed to stay outside of scrutiny, right? Because they produce so much money, they're a huge monopoly, they charge a lot, and they're still a kind of great company, right?
You can be CEO of any other company for a day.
Which company do you choose to be CEO of? I would like to try something in biomedicine or genetics. Yeah, that would be very interesting. Just to learn because I know zero about it.
Penultimate one. What would you do differently if you were starting Revolut again?
I would do everything faster and I would do everything much cheaper as well.
Final one. What question have I not asked that you think I should have asked or you don't get asked often?
Why do you do what you do?
People don't ask you why?
No, not at all. I'm very surprised, like no one asks. Well, I asked it actually myself many, many times and I have 2 answers, right? Because A, like what else to do? And B, yeah, I just need to do something, right? Otherwise it's very boring.
But you have to have a passion for it too. And you have to have a passion to change an ecosystem in an industry.
Yeah.
Yeah.
For 99% of the day.
Listen, Nik, thank you so much for doing this with me. Thank you for having me in the office, and this has been so much fun.
Take care.
More from Nik
Revolut CEO Nik Storonsky on Building a Fintech Giant | The David Rubenstein Show

John Doran interviewing Nik Storonsky, Founder and CEO of Revolut at the Dubai Fintech Summit
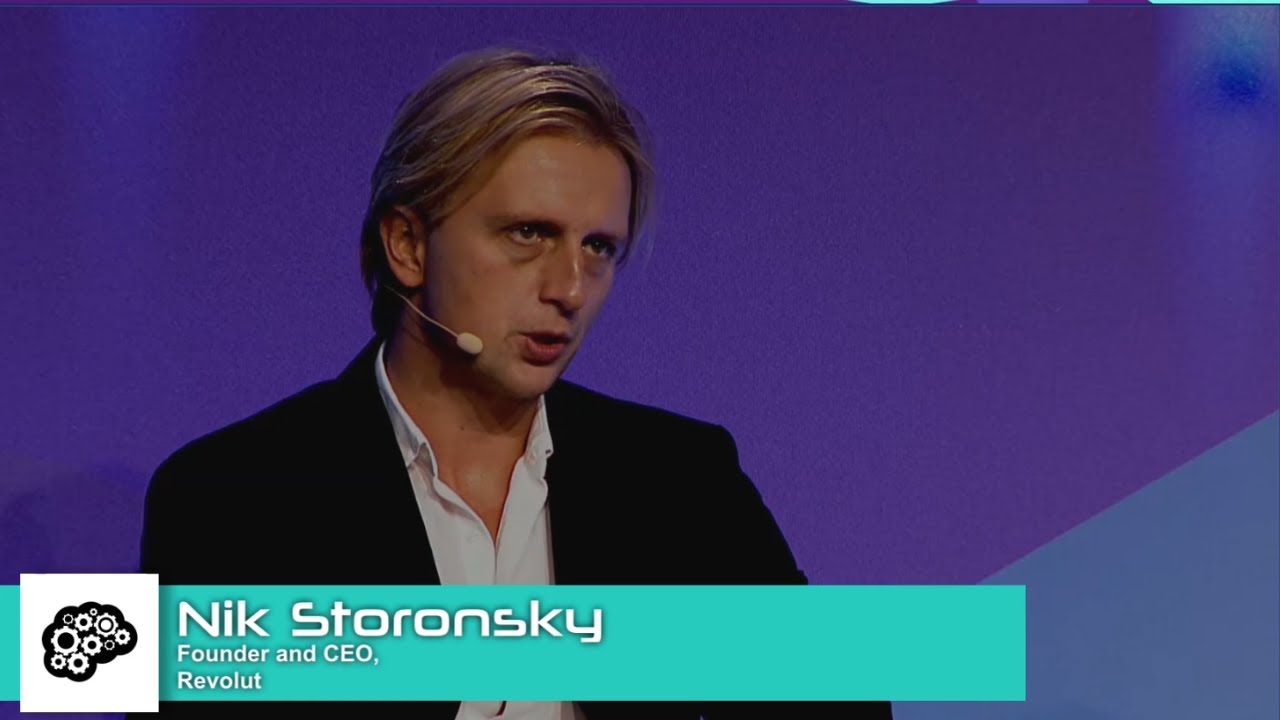
AI Summit London 2021 – Revolut's Vision for The Future of The Banking Industry