The Financials & Assumptions: Woody Creek CondosProjections
Pete Schnepp and Mike discuss the conservative financial underwriting for the Woody Creek Condos project. Key assumptions: 24 units; year-1 vacancy modeled at 23.5% (project turnover), year-2 at 10%, then 8% annually thereafter; 3% annual appreciation applied to income and expenses over a six-year hold; renovation schedule of ~30 days per unit plus 45 days lease-up; $20,000 interior renovation budget per unit; $100,000 asphalt/exterior budget; $143,000 reserves included within a $2,000,000 raise (≈ one year of interest payments); target rent $2,095/unit (≈ $158/ft²; market comps average ≈ $160/ft²); 10% management fee used in underwriting; interest-only loan with step-up rates (3.25% → 3.75% → 4.5%; blended ~3.88%). Tone: conservative, promotional. Primary intent: explain conservative assumptions and persuade investors to soft-commit.
Questions this video answers
24 units
23.5% (23 and a half percent)
10%
8% annually
3% over six years
Chapters
Foreign Mike. What's up, man?
Hey, what's going on, Pete?
All right, so what if I told you that we are over budgeted and under projected on income on this Woody Crook Creek deal and we're still projecting over 20 average annual return for our investors?
That's exciting. Would love to hear about it.
Well, you already know about it, so let's just talk about it. All right, I'm gonna share our proforma here, which we built together. Can you see it?
Yes, I see it.
So let's walk through this a little bit so everybody can kind of understand what we've built here, what the numbers look like. We're going to deep dive for a bit because one of the things that I pride myself in doing is being ultra conservative. And I know you do as well. And so we've built this model out super conservative. I know the numbers that, that we're projecting for returns seem super juicy, which a lot of people might think that we're trying to be a little bit less conservative, which is not the case. Right?
That's right. Ye. We're beating up the deal to make sure we're super conservative on this one. And it's really exceeding our expectations on it.
All right, so first off, let's talk about our vacancy rates. Okay. Shearerville as a market right now averages between 4 and 5% vacancy. Okay. There's a market stat. You can look it up. What we've modeled into our projection here is we've got 23 and a half percent vacancy on year one. Why is that? Well, it's because we're doing the project. Okay. We're going to be turning units over and we'll talk about that in a little bit. Year two, we're going to be rolling, you know, probably the last unit or two over, but we've got a 10% vacancy projected year two. And then we just hit it with 8% year over year afterwards. Why didn't we go with 5%?
Well, again, just being conservative in our underwriting and our approach. We just felt 8% is a good number and it aligns to the strength of shareables market as well the rental market. So I, you know, I just feel when you, when you underwrite the properties and if you're conservative, investors will believe it and really trust in that. And I feel we're going to exceed that. I mean, Cherryville has a strong market. I'm from the area, and it's a pretty dense market too. So I don't think we'll have a problem with Any type of vacancy. And just this one being, you know, with the reno scheduled, having the luxury feel and look, it's going to, we're going to have that strength behind us and still being under that average market of rental price.
Right. So yeah, we're ultra conservative on vacancy, almost double what the market is out there, just because we want to be ultra conservative. But what this amounts to is once we get our Turnover Done, that's two units out of 24 that are vacant, which, what's the likelihood of that happen? I mean, it could happen for sure. That's what we budgeted. But what's more likely is that we don't have those vacancies. And what that means is our project, our returns are just going to go through the roof, right? They're going to be higher, but we're, we're not banking on it. Okay, let's talk about the turnover schedule here. Well, actually, before we do that, the other thing that you can notice here is we're banking on a 3% appreciation rate over the next six years, both in income and expenses. All right, so why, why do we go with 3%? It's a number that I normally go with because I feel like it's conservative. But honestly, Mike, anybody that's owned real estate for more than a few years has, has experienced much more than that. The reality is, is we are buying right now in a market that is somewhere at the bottom of a cycle. Okay. Somewhere. And I would expect over six years to have much more than 3% appreciation. But it's just another, you know, conservative way that we build our models in order, in order to under promise and over deliver. So we've got 24 units. We're going to doing strategic upgrades, flooring, cabinets, paint, stuff like that. So we've got this whole turnover schedule built out right here. What we're planning on is essentially 30 days for renovations and 45 days to get a leased up per unit. And that amounts to a 20 and a half percent vacancy rate in year one. So we'll get this done in year one. We've calculated a 23% vacancy vacancy rate to give us a little bit of a buffer there. How do you feel about turning over a unit with the renovations in 30 days?
Well, I believe that's plenty of time. Pete, if you're asking me, just, just being in construction management and being in management myself and also having the expertise of putting in luxury final flooring in my own home and different other people's homes as well. I used to run a paint Company. I've done this stuff for years and that's plenty enough time for one unit that's only 1350 square foot. So we should be able to push the contractors, get really good contractors on board with this and just with the schedule that we've laid out, I mean it's going to line up perfectly with the lease up and really get this to where we need it positioned. And just speaking about earlier, what you had mentioned about the annual appreciation on the income and expenses. Yeah, we're super conservative about that. And just to add on to that, I've seen underwriting as high as anywhere from 6 to 10% that guys have underwritten on their particular deal. So I think we're falling back on this one a little bit conservative and showing that sustainable growth project.
Yeah, definitely. So when I originally laid this out, I wanted to go with a 60 day turnover schedule because I feel like that's really most doable. But I decided to pat it an extra 15 days. Just, you know what, maybe we have some bad weather or whatever, but if we come in the first year with a 15 or 16% vacancy rate instead of 23 like we projected, what does that mean for investors? More money. Right. Quicker distributions. So under promise over deliver. I think that's our theme, what we're trying to deliver here. All right, so that's a lot of units to turn over. Let's talk about what we're going to be doing and how much money is it going to take? Okay, so we've budgeted what I feel like is an ultra conservative amount to get these units done. We've got $20,000 per unit for interiors that' for LVP flooring, granite or quartz countertop, painting the cabinets, putting on some hardware, maybe replacing and upgrading some light fixtures or plumbing fixtures. And the appliances. Right. So they're 12 year old appliances, but they look pretty clean. Maybe we can make some strategic updates there. But 20 grand a unit for 1350 square feet goes a long way. Would you agree?
Absolutely. I think, I think that that's going to stretch a lot. We'll be, we'll have a lot of options and a lot of cash to, to be able to get the nicer upgrades in those units and get a, get a pret built product for, for the clients that are going to go in there. So I think we're going to have a really standout units in that area. So I think it'll be effective.
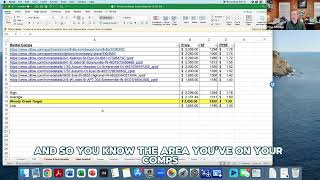
Yep. So for the exteriors, not, not a whole lot that we're going to be doing. But we've got a budget here to paint the exteriors. They don't look bad, but they're 12 years old. And you know what, a fresh paint job, some designer colors are going to attract the best tenants and give it the best curb appeal. The, the asphalt. We've got $100,000 budget here. It doesn't need to be done right away, but it sure does add the curb appeal. And if we're going to wind up doing it before we sell, we might as early on. So that's something that we're, we're bidding out right now and going to weigh that out. But it's in the budget. And then here's the kicker. We've got $143,000 in other reserves budgeted in our 2 million dollar raise. So this is just to have in the bank. And basically we came up with that number because it's one year of interest payments for the mortgage. All right. So we will have zero financial distress in this property. We were going to have a ton of money in the bank and we're going to come in under budget on this construction. It'll probably happen quicker than we antic and there will be more cash flow than we anticipate, not only just in year one but overall in the project. So this is kind of how we're laying things out. Let's go back to the comps because as you saw, we're looking to rent these units out at 2095 per unit. That's our income driver. All right. And so you know the area, you've done your comps. I've independently done my comps. But here's a quick snapshot of what's available in the area right now. Some of these are already rented, but it ranges from well, 1650 on the low end. But most of them are between 2000 and 2300. 2400 bucks, right? The, yeah, the average is 160 a foot. The high is 178 a foot. Our target puts us at 158 a foot. So what does this mean? This means we're going to have the nicest units in town for the average price. Pretty cool, right?
Yeah, I think that's great, Pete. We're going to be really the best looking units at the, at the lowest price. I mean, what better can you get? And just being from the area, I can, I can personally tell you that this is a very affluent neighborhood. We've got homes that are, are, you know, anywhere from 6,6000 square feet. All brick homes that are just right around the corner. As I drove up into the neighborhood, you'd seen Mercedes and really nice high end luxury cars in the neighborhood. Porsches, Lamborghinis. So it's, it's an affluent neighborhood. So the folks that are going in there really love the neighborhood. It's a safe neighborhood. There's not a lot of crime and there's a lot of amenities nearby. So there's a lot going on in this particular area. And just growing up in the area, that was really the hangout spot where we would, you know, entertain ourselves. The movie theater is right there around the corner. All the shopping's there. So this is a very good market, a good place to be and the folks to hang out in. So we're just going to see that competition in that, excuse me, that we're going to see that driving force when it comes to running these, these units out. And they're going to want to have that luxury feel to them. And I feel like this is, this project is going to be awesome to work with and showing the market that these units can withstand the storm.
Yeah, yeah, I agree. So what does that mean really? I mean, this deal aligns with everything that I look for in terms of the finances on a property. That's why we're doing this. Because what that means to me is ultra low risk. Okay? Ultra low risk, super conservative underwriting delivers above average returns and you know, we hit some tailwinds, we have some wins along the way and it's just gonna get better from there. This means to me, you know, this means low risk, high reward. This means you and I as a team are able to set the bar at a comfortable rate to where we're easily gonna be able to over deliver. And that's ultimately our goal. Right. So taking a look back, P and L, this is kind of how the, the math breaks out for the next six years according to our projection, which hopefully will blow it out of the water. 3% appreciation rate, Conservative vacancy rates going forward. We think we're over budgeted on all of our operational expenses. Honestly. We've got 10% management fee built in. And I know personally, I, you know, out here I pay 7%. So we're in the process of bidding out the management. A lot of this stuff is going to come in under budget, budget as well. And our interest only payments help with the cash flow. You'll see here we've got the step up interest rate starting at. Where are we at 3.25. Then it jumps up to 3.75. And then we're at four and a half the last two years, but it's a blended rate at 3.88% is how it calculates. Overall, just a fantastic project that I'm super excited about, and I know everybody that gets to see this information is going to be super excited. So, you know what? If you're out there listening and watching. So if you're interested in getting in on this deal, sign up now. Do a soft commitment because it's much easier to get your name in the hat early. We can take you out if you decide that it's not for you down the road. But if you decide in a week or two that you want to get in on this, it's probably going to be too late. So go ahead and click the link and let's get it done. Mike, any last thoughts?
Yeah. This opportunity is moving quickly. I already have a list of investors ready to commit and the spots are limited. So it's easier for. For you to reserve your investment now and remove it later if you change your mind than to try to get it in in a later date. So don't wait. This. This could be your chance to be part of an exceptional deal that we've got going on.
All right, good stuff, Mike. We'll talk to you soon.
Alrighty. Bye, Pete.
More from Pete
How I Turned $3K Into $300K Tax-Free: Real Estate Wealth Hacks You Need to Know!