Pete Schnepp walks through underwriting for Woody Creek Condos, targeting $2,095/unit rent against current market rates of $1,400–1,550. The deal assumes 23.5% vacancy in year one, drops to 8% stabilized, with $25,000 renovation per unit and $143k in initial reserves.
Questions this video answers
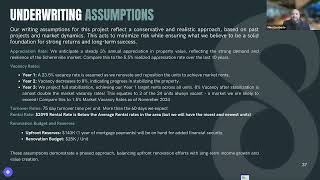
3% (straight-line, applied to value, income, and expenses).
23.5% (padded from a 60→75 day turnover assumption).
Year 2: 10%; Year 3 onward (stabilized): 8%. (8% corresponds to ~two units vacant at all times.)
$2,095 per unit (current rents ~ $1,400–1,550; comps $2,000–2,500).
$143,000 (one year of mortgage payments).
Chapters
Now we're a little bit conservative on our underwriting while really conservative on our underwriting. And we're still, we're still projecting these returns, which frankly, they're quite amazing compared to what I normally do. And so let's take a look at some of our key assumptions in our underwriting. Because these, these levers, you know, you could be, you could be less conservative on these, these levers and make the numbers look better and vice versa. It's a balance sometimes between how you project these. So the key projection is, one of the key projections is the appreciation rate. So we plugged in 3% annual appreciation in the value, the income and the expenses. Straight line, 3%. It's usually what I underwrite my deals at. Like we mentioned earlier, Shearerville has experienced five and a half percent average over the next 10 years. Now nobody knows what the future holds. Right. I feel like 3% is a safe bet. The reality is, is, well, I went through the boom and bust of 0708 and I feel like everybody that I talk to that's a big player in real estate right now seems to feel like that we are somewhere at the bottom of a market cycle.
Right.
And if that is the case, I would just naturally expect that we are going to experience a whole lot more appreciation than 3% over the next six years. I'm hoping so I'm going all in. Right. But this is how we pencil it out and it's still projecting these amazing returns. Vacancy. So, like we mentioned, the first year we're doing a big project, there's a lot of units we're going to turn over. And so we have an entire schedule that does the MA on that. And well, the math on, on our schedule is this is padded from that. So if, if our, if our renovations go exactly how they're planned, I think it said that we would be at a 16 or 17% vacancy rate. And what happened is we added some extra time for our turnovers. So that 16% vacancy rate means we could do the renovation on a unit in 30 days and we could get at least up in 30 days. So a 60 day turnover time per unit, we padded that to 75 days in case we get some inclement weather or whatever, that the vacancy rate to 20% in year one. And we went ahead and added an extra three and a half percent just to be ultra conservative. So 23.5% vacancy in year one. After that we moved the vacancy rate after stabilization year two, we have 10% projected year three and on we're at 8%. So an 8% fully vacant, fully stabilized property that equates to two units vacant at every the entire time after stabilized. Mike, what are your thoughts on that?
Yeah, I think that's very conservative underwriting. I agree with it. When we looked at it as far as the 75 day cycle and a turnaround, I mean that's plenty of time. I've, I've done my luxury vinyl flooring. As I mentioned earlier, it only one man job. It took me a month to do that. So imagine a team, imagine constructors, imagine professionals doing that and with the smaller space as well. So we should be able to knock that out very consistently without any problems. We should have enough time to do that. So I think we're being very conservative on that. Vacancy rates and, and especially when we're trying to stabilize up in the second year and third year think it's right in line with the market, if better.
Yeah. So the Indiana state average was like seven point something. And everything that we find out was about Sherville indicates something less. There was a stat we saw at one point, November of 24 was 1 1/2 percent. We've seen stats in the 4 1/2% range and sixes. So I will say here in Maricopa county we've had record evictions this last year in 2023. So vacancy rate's been, been pretty high. And so if, if Indiana is experiencing something similar to that and it's still got a seven point state average for vacancy rate, you know I would, you know, I'm already seeing that vacancy rate drop quite a bit. Like the occupancy is picking up in the last quarter for sure for me and everybody else I know in Phoenix. And I would imagine the same thing is happening but maybe on smaller scale, less percentage wise in Indiana. All right, so we talked about vacancy. What about the rental rates? That's the income driver we mentioned. We want to rent these for 2095 per unit. Right now they're renting for what, 14 to 1550. So the comps out there range from 2000 to 2500. And we, when we look at what legit ultimately would would the comps be and we average them out high to low if the average is actually lower or the average is higher than 2095. So what this means is we're going to have the nicest and newest units for the average price. We are not trying to push the market rate. We're not trying to do something that hasn't been done before. We are not like getting risky in this department. This is an ultra conservative rate and just another reason why I'm really confident that we're going to over deliver on this project. And then lastly the reserves. OK so in that $2 million raise we have 143 upfront reserves just to have padded in the bank account for us and what that we're we came up with that number because it's one year of mortgage payments, 143 just sitting in the bank. We're also in the P and l includes a $6,000 a year addition to the rent reserve budget. So we're going to have plenty of money in the bank. There's going to be zero financial distress and that's all included. And so that's another lever that people can pull if you under raise or don't figure on those reserves it just makes your look better. But we are over raising and still delivering great numbers. And then the renovation budget, our total budget for the project equates to 25,000 bucks per unit. 20,000 for the interior and 5,000 for the exterior. And 20,000 bucks a unit for a 1350 square foot condo is going to go a long way and Mike's got resources out there. Go ahead.
Mike told you yet? But I actually got a call today. You know, as you know it's this is near my hometown. I've got family out there and they've been seeing the marketing going out on on the we web and social media and they've already called me. They, they want, they've already got four folks that are or four families that want to rent the apartments or the condos already. So they also mentioned that they're looking for really nice condos just like this or living spaces with affordable rents just like this. So they can commute from Chicago and back to Indiana and enjoy the taxes. So that just speaks volumes of the market and what the tenants are looking for and this is something that they're looking for.
Yeah, yeah, good stuff. So all the major levers that you can pull and be over conservative or under conservative are right here. And honestly this is way more conservative than I generally underwrite deals in Phoenix and we're still delivering returns that look better than what I do in Phoenix. And so I think we're going to even over deliver on these but that's how it's shaken out.