Cryptospace Moscow. Roel Wolfert. Local currencies as the ancestors of cryptocurrencies
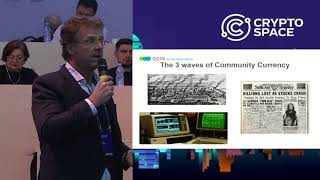
In this 2017 Cryptospace Moscow presentation, Roel Wolfert argues that modern cryptocurrencies are the fourth wave of a long history of community currencies. He begins by debunking the myth that money is a recent invention, showing that money is a 6,000‑year‑old human construct and that 97 % of its current control lies with commercial banks, not governments. He then outlines three historical waves of community money: (1) 19th‑century labor notes, (2) inter‑war local currencies such as Switzerland’s WIR, and (3) the electronic era of loyalty points, time‑banking and barter platforms, which together already represent billions of dollars in value. Wolfert explains why the fourth wave—cryptocurrencies built on blockchain and the internet—differs: global scale, transparency, and the removal of intermediaries. He links this technological shift to systemic pressures – recurring banking crises, rising public debt, demographic aging, and automation‑driven job loss – arguing that existing monetary systems cannot sustainably fund welfare or green investment. He then presents three pillars for a successful currency design: a clear “why” for each stakeholder (investors, consumers, retailers, developers, governments), a robust token model (“what”), and strong governance and team quality (“how”). He warns that most existing tokens will fail, likening weak cryptocurrencies to faulty refrigerators. Finally, he stresses that money is a legal, human‑made tool that can be reinvented now, and that adaptability, not size or intelligence, will determine survival. The talk ends with a brief Q&A where Wolfert compares the systemic risk of crypto to gold, noting crypto’s current small share of global GDP but predicting growth and greater regulation.
Questions this video answers
Wolfert explains that the total market cap of all cryptocurrencies is currently orders of magnitude smaller than the global economy and the banking sector; even a total collapse would affect only a tiny fraction of global GDP. He also notes that future regulation and asset‑backing will further reduce systemic risk.
Chapters
Can you hear me also in the back? Is the sound good? Yeah? Okay. Oh yes, that's great. I need that. We all think we are doing some really innovative, great, fancy new stuff, right? Right? Cryptocurrencies? Fuck wrong! It's 200 years old. Yeah, it's just a different technology. Yeah, and even worse, money is 6,000 years old. And just so you know, it's a human invention. Nobody owns money. Actually, it's slightly weird because— can I just ask a question? Who in the room thinks that governments control money? Can I see arms, please? Who thinks it's the government that controls money? This one. Who thinks that it's, for example, the European Central Bank or central banks that control money. So in this case, the Bank of Russia. Do they control the money? Who thinks yes? Raise your arms, please. Okay, good. Interesting. Well, let me surprise you. Money is for 97% under the full control of commercial banks. Why? That's simply how it happened over time. Yeah? But don't forget, it's a human invention. And guess what? It's up for renewal. Yeah? And I'm going to take you through a little bit of history. Sorry, can— I don't think it's working. So this is technology. That's always the problem. [SPEAKING RUSSIAN] Oh, there it is. So what I want to do right now, yeah, I know it's after dinner, so I'm going to keep it light. Yeah, I want to explain to you what is a community currency and how cryptocurrencies actually fit in as the fourth wave of cryptocurrencies, of community currencies. But if, if this is the fourth wave, why is it going to be right this time? So why is it going to be different? So I'm going to talk a little bit about what is different, and then I'll hopefully end up with the three pillars of success for any currency design, not just cryptocurrency. And I hope that's going to work for everybody. Can I get the next slide? Yeah, thank you. So community currencies, where do they come from? What is it? Actually, as I said, money is not state-owned. Money is not the sole right of commercial banks. Any person at any point in time can create its own currency. And generally, we like to do that in groups. Groups that have certain commonality, like a purpose, a business, an industry, a region. Now the region is very important here because community currencies up till not that long ago always had to be regional, bound by technology and limitations of that. But community currencies come in many shapes and forms. The simplest form The simplest form of a community currency is the stamp that you get with your local butcher for buying steak, and he rewards you for your loyalty. The most— the outside boundary of community currencies is legal tender. So that's rubles, euros, US dollars. Anything in between the stamp of the butcher and euro is a community currency. Yeah, so let me give you a few examples on how big community currencies are already in this world prior to cryptocurrency. Prior to cryptocurrency, we already had more than 100,000 loyalty schemes around the world. Yeah, more than 100,000. There's more than 15,000 local community currencies ranging from Brazil to Europe, Netherlands, into Asia, Japan, based on time banking systems or local exchange and trading platforms. And one that's probably most surprising, there's a barter industry, yeah, just exchanging goods for goods. That is worth today $80 billion in the current market. That is pretty big. Yeah? If you add up all these numbers, it's significant. To give you a real example of how big community currencies already are: in 2010, I was at Visa and we were talking about how to revive the UK economy from its downside after the financial crisis in 2008. In the UK, on loyalty schemes altogether was held 96 billion sterling in loyalty points. That's the equivalence of 8% of GDP of the UK. It could have really restored the UK economy in an instance if people started to issue that and use that currency as means of exchange. So, can I get the next slide please? Okay, so where are we on the 3 waves of community currency? A little bit of history lesson. First of all, it starts in the Industrial Revolution in 1834. An Englishman actually says, "We're seeing too much differentiation between rich and poor. The labor workers have too little rights." And they came up with labor notes. Now obviously he got them accepted in several marketplaces in Glasgow and in Manchester, yeah? But after 2 years it ran down. But this was the first experiment of what they call the Enlightened with community currencies and the trend was set. Then we're moving on to the Interbellum. Can I get— The Interbellum, which is basically the period between the First and Second World War. And we all know this was a time of huge financial crisis. We had the Wall Street crash, huge unemployment, etc. that was happening. That's why people took their faith in their own hands. In Switzerland, WIR Bank was launched. WIR is a local currency that was founded between companies to actually do trading amongst each other. Now for the ones looking up now, right now, Wikipedia, WIR Bank. WIR Bank today has 80,000 businesses in Switzerland that exchange goods and services with their currency WIR in combination with Swiss franc. It has a contribution, net contribution to the Swiss economy of over $3 billion a year. This is significant. So when the Swiss franc goes up or down, their local currency, community currency, the währ, actually stabilizes part of the net effect on their economy. So things change. So where are we? In the third wave, we see personal computers, laptops, and the internet show up. So from physical money, paper notes, coins, etc., the community currencies moved on to the PC and to the bank cards. So we saw them in electronic forms. And we saw a rise. So in the '80s, we actually seen community currency grow from a single few experiments across the globe into several thousands of community currencies. There are a number of regions, for example, in Brazil and Argentina, that were basically bankrupt introduced their own currency, set up an exchange platform, and they rebuilt a vital economy without the real or the Argentinian peso. These economies are still existing. Some of these community currencies actually decline over time for the simple reason that the purpose is fulfilled, and then the currencies disappear. Yeah, so what is really happening? Yeah, when we talk about the fourth wave or the wave of cryptocurrencies, what is going on? What is driving this? What has changed? Now I'm going to make an analogy with you so that you understand what is really going on out there. So we all know mudstreams, I think. So we've seen the effect. Can I get— yes. So a mudstream is basically a nature anomaly that destroys a lot. You see the disasters on television, whether it's in Europe, Africa, or anywhere else, it doesn't matter. It's always devastating for the people surrounding it. Now, what causes actually these mudstreams to happen? There is a simple thing, and that is human activity is the cause of the majority of mudstreams happening. Because humans, in their natural behavior, aim for efficiency. So we want to build more roads so we can drive with more cars through the mountains, at the same time preferably. We are building skiing slopes so we don't ski on our own in between the trees, hundreds or thousands of people at the same time from one mountain. We grow one sort of corn in a region and this deprives nature. This is what's happening. So what is the solution? So the solution is really in diversity, ecosystem thinking, and focus on effectiveness. This will resolve the mud stream. So now, from this analogy on how nature resolves itself, let's go back to our human world. The human world that started off with the financial crisis in 2008. Yeah? So that was not the only crisis. That's maybe the crisis most of us have felt. But research shows that we had about 97 major banking crashes in 25 years. That's 4 a year on average. Maybe you haven't noticed, but it's happening. Yeah? And 178 monetary crashes. So the Argentinian peso devaluating, the French franc devaluating, the German mark devaluating. Okay, I know they don't exist anymore, but it was always a monetary crisis. And guess what? We try to resolve that with more efficiency. So we move from all these small currencies into the euro, and the mudstream gets bigger and bigger in our of the world. But it's not everything. If it was just financial, then it wouldn't be the biggest problem. But what we also suffer from is we have an aging population. More between now, 2015, 2030, number of people above 60 will grow with 56%. That's huge. Who's going to pay for the healthcare? Who's going to pay for their pensions? Where's that money coming from? It's unaffordable. We all know this. There's more.
Yeah?
It's basically called robotics. Yeah? In a few years from now, 47% of the jobs in the West will be redundant because we're really good at delivering technology. Yeah, who's going to pay for welfare of unemployment? What are the people going to do that lose their jobs? Where out is there? What value are they going to create for this society? Yeah, taxes. Yeah, it's a big problem. We always think that let's solve this problem of we have too little money by raising taxes or cutting government expenditure. That's no longer a solution. The solution doesn't work because if you today in the Western world raise taxes with 1%, we lose 2 to 3% of GDP. So it doesn't make sense anymore. We're running to the limits of our system. The current system stops working. So what is different with cryptocurrency? And this is not going to be horribly new for most of you, at least I hope. Yeah, but let's start with the first thing. There is a system failure in banking. I think I just clearly explained it, but to reemphasize, if Yeah, we all know that we had the 2008 banking crisis, which was referred to as the credit crunch. Now, let me tell you the solution we found for the credit crunch. So we looked at $3,600 billion of debt, and you know what we did? We made it transparent and we made it $7,200 trillion of debt. So today we have 2 times more debt than in 2008 when we had the credit crunch. So failure or solution? Second topic is we're dealing here with the biggest or close to biggest difference between rich and poor people. People are unhappy. Poor people can't get rich anymore. They can't get true value out of life anymore. And they put to work day and night. This is a problem. Nature, environment, global warming. Who's going to pay in the Netherlands for higher dikes? Who's going to make sure that we restore the world for our children? Where are the investments in green energy going to come from? Where is the investment in wind? I don't know, whatever new technologies we need to create a more environmentally friendly ecosystem. Good news is we have new technology, blockchain technology, on top of internet and all the other things we already had. And this is what's going to make a difference. Yeah, let me explain why. So the real differentiator here is that with internet we brought people together, and with blockchain we make it transparent and global. So we no longer need middlemen. We don't need government. We don't need legal. We don't need notaries. This is all becoming obsolete over time. And that will help us to establish the currencies that are powered by people into society to last. So the question is, is it going to last? Yes, it will. Yeah, I think the number today was $430 billion in crypto. Don't know exact number, but that's a lot of money. And although regulators are trying to push it away, for example in China, it moves to Japan. Yeah, and if one country shuts down, the Bahamas come up and Malta's coming up and the Netherlands are coming up because we see ICOs and cryptocurrencies as a market. But not for everybody, not any currency. So you need good currencies, like you need a good refrigerator. Bad refrigerators don't keep your food very well. Bad cryptocurrencies don't keep their value. So the question really is, when we move into this space, what are these community currencies that we refer to as cryptocurrencies? What do they need to look like? So I'll try to give you a little bit of an idea, but basically a good cryptocurrency or good token needs to have a why for who, for all the stakeholders in the environment. So there's an investor, there's a consumer, maybe there's a retailer, maybe there's developers, there's partnership, maybe there's government. They all have a value that they need to get, and you need to address it. If you you fail to address one of the parties in the ecosystem with value that you're trying to serve in your small economy, because that's what you're building, you're going to fail badly. Yeah. So, and then the question is always what? A strong token model. Yes, you need to get it right and all the sort of, maybe also more technical, but in detail getting it right. Also very important is the how. Strong governance. What was it this morning? 90% is government, 50% is technology. Well, I go a little bit further than governance. Governance means legal compliance, marketing communication, quality of the team. Yeah, you can't run a business without good people. That's at the core of everything. So you need to have a good team to make that work. Now, I know this doesn't sound like rocket science, but we all know that out of the 1,300 cryptocurrencies out there, My feel says that 50% is not going to last, maybe even 80% or 90%. Yeah, and that doesn't mean they're going to disappear, they're just going to be stuck there as an illiquid asset for a very, very long time. So what do I hope you picked up? So 4 things basically. Money is a human invention, so we're all humans in this room. Pick it up and do something with it. Don't wait for the government, don't wait for commercial banks. It's under your control and it's perfectly legal. There is no law that says that you can't make your own money. The timing is now. I think I've been clear. 2008, enormous shit fan happens. Yeah? We don't solve the problem, we just double the debts in this world. Yeah, we're aging, we're doing this thing. It's time. Maybe not today, maybe tomorrow. Okay, I'll give it a day. Yeah? Maybe Monday because tomorrow is not a working day. Okay, let's do it on Monday then. Yeah? Technology is going to make a difference. Like this is Horizon 3. Yeah? Horizon 3 innovation coming to life. That's always driven by technology. But technology is only as good as the people steering it. Yeah? And last but not least, currency. Get your currency design right. That's essential for success. I hope that makes sense. And as a last final thought, always remember that it's not the big, not the smart, but the one that's most adaptable to change that will survive. So change. Thank you.
Now let's thank Roel. We have a couple of minutes for the questions session. In order to ask the question, we use the application which is CryptoSpace application. If you haven't downloaded yet and you haven't learned how to use it, you can go to App Store or Google Play and download it to your cell phone. Otherwise, through the PIN code on on your badge. If you have any questions, so please raise your hands, we're going to provide you with a mic and you can ask your question.
Ah, but there was like a phrase that we don't have future if we don't remember the past. So just before the Bretton Woods Conference, there was a system that the gold was like equally to the fiat, right? And after that, there was a huge crisis in the world. Why don't you think that Bitcoin or cryptocurrency is kind of gold and actually better than gold. Why don't you think that it is possible in the future that there will be much more, much more powerful crisis considering that fact?
So just to be clear, why, why wouldn't there be a more powerful crisis than before?
Because it will be like the whole our planet will be in this scenario.
You mean based on cryptocurrencies, the crisis?
Because it's better than gold, than a regular gold.
Well, first of all, the financial crisis was already— so the global financial industry that we had in 2008, the sheer size was probably 10,000 times bigger than the current size of all cryptocurrencies together. So, uh, that's one thing. And if you look at the global economy, that's probably 100,000 times bigger than the cryptocurrency. So if cryptocurrencies fail, we're going to lose 100,000th piece of where we are.
So I think it might be the global GDP.
Well, I don't think 20 years, for example, Oh, when cryptocurrencies are in 20 years from now. Okay, I, I would say that they're much bigger, but then in 20 years' time we have more regulation, we have more experience, we have much more cryptocurrencies. We probably will have more asset-backed cryptocurrencies, so, you know, backed up with gold, backed up with, you know, silver or commodities, or backed up with green energy, solar energy. Backed up with wind, with real assets that are tangible and delivering value for our economy. So in the current situation, I don't know, but the euro is backed with jack shit except for good promises from prime ministers and European bureaucrats, but I don't see besides that any value backed up behind the euro. This is causing, in my view, part of the distrust in legal tender. This whole drive for efficiency, less currencies, more control, the big highway. I still remember very vividly, "Oh, let's do the euro because it's going to be cheaper for everybody." That's an efficiency ruling. But what they forgot to say, that you can do less with the euro than you could do with the French franc or with the German mark because it was losing purpose. It lost identity. So over time, yeah, when we look at the crypto market, if it's evolving, it will stabilize, it will become a fair share of the economy. But we have to be careful because it's still early days. So let's not make the lessons or the, the mistakes that we made in the past. So past mistakes on community currencies are government just forbids them. That's a failure in history. The only ones that didn't do it were the Swiss, and they are now benefiting from the WIR in their economy, in their day-to-day life. When the global market starts to complain about, oh, the Swiss franc is getting really expensive, they will now lose exports because they get expensive, they don't care because they have 80,000 businesses trading in WIR. Locally. And that means that they have a local manufacturing and services industry. So that was failure number 1: government interfering with something that the market could figure out themselves pretty easily. The second thing that is really different is we now have global technology. So community currencies generally tend to fail because the formula of amount of money times circulation/velocity doesn't add up to be big enough. Yeah, I know that's an economic equation, but simple answer is community currencies were too small to last. Now with internet technology and blockchain technology, you can get like not 5,000 people into a community, but maybe 5 million all at once. And that's scale. And scale always makes things—
billions. So, or 8 billion?
Yeah, 8 billion would be nice, but then preferably also with, you know, more than 100,000 different currencies and not just one.
More from Roel
Dé Potentie van Asset-Backed Tokens!? Traditionele Finance vs. Crypto | In Gesprek met Roel Wolfert
Interview – Roel Wolfert: Ecosystem of tokenized securities in the Netherland. DeFi boom.