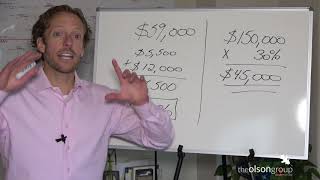
Andy Neary shows how cost-shifting in health plans hits low-income families hardest. A family earning $59,000 pays $5,500 in premiums plus a $12,000 out-of-pocket maximum, totaling nearly 30% of their gross income. He argues employers should cut both premiums and deductibles instead.
Chapters
Welcome back to striking out the status quo. Your health plan is just one mindset shift away from greatness. Alright? In the past I've shared with you the financial impact that cost shifting is having on your workforce. And for years you have been taught by the health insurance broker community that you cannot have a better health insurance plan for less money. In fact, you've been told the only way you can reduce your health insurance cost is to shift cost by increasing deductibles, increasing out of pocket limits, just asking employees to pay more. Today I want to show you the impact, the financial impact that's having on your employees today. Because for somebody making 150, $200,000, it can be hard to comprehend. So here's an example. Let's say you have a family making the average median income of a family in the United States $59,000. And they're on your health insurance plan. And your health insurance plan has the average family contribution of $5,500 a year in premium. And your health plan has a $12,000 out of pocket maximum for families. If this employee with family coverage were to max out his or her insurance, their premium plus their out of pocket limit would have them paying $17,500 for the year. Now, for a family making $59,000, that's 30% of the gross take home before taxes. Now again, it can be hard for somebody making 150, $200,000 to comprehend that. So let me give you an example. Let's say you were a CFO or a CEO making $150,000 a year. And you too had an out of pocket limit and a premium contribution that was 30% of your gross take home. You have a $45,000 out of pocket limit. Kind of puts it in a different perspective, doesn't it? Now here's where the shift needs to happen. You've been told the only way you can reduce this premium is to keep increasing this out of pocket limit. But what if you found a way to not only reduce the premium you ask your employees to make, but you reduce their out of pocket limit at the same time? Well, I'm here to tell you there has never been a greater opportunity to do that than there is today. And if you are not being shown the solutions that are out there that can help you accomplish that, you need to start searching for them today. Because the days of cost shifting need to come to an end. Because we now can not only help our employees get better access to healthcare, but we can help take money and put it back in their wallets at the same time. Till next time, bear down, focus on the target and strike out the status quo.