The Secret Payment Strategy Stripe Doesn’t Want You to Know
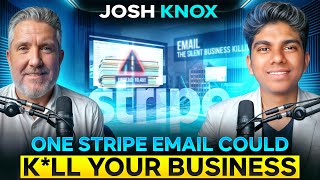
Joshua Knox, CEO of Numerik, explains how Stripe's sudden account shutdowns happen and how his platform cuts processing fees to 50-90% lower by letting customers pay with rewards cards. Numerik uses multiple merchant accounts and tokenization to avoid triggering risk alerts that plague traditional processors.
Chapters
What's your story and how did you stumble upon this business?
You know, as a kid, I just had a general sense about myself that I wanted to be a business owner.
What was it like for you in the early stage? How did you build that trust with the community overall to get those initial customers?
The reality is, is you deliver the result. So if I say I can do this, then when you trust me to do that, I better deliver that.
How do you differentiate that? Like, who should use Stripe and who shouldn't use Stripe?
Stripe is like the American Idol of payments. They want literally Everybody to come on board.
How can you help businesses save 50 to 90% cost compared to a traditional solution overall?
If you did $100,000 a month on Stripe right now, I can tell you it's going to average around $3,500 a month in cost.
You're basically de-risking by creating lower limits but multiple accounts.
Build stability in early so that you can scale and grow long-term, right?
Any last words for us to conclude the entire podcast for today? Just keep going.
Just keep putting one foot in front of the other.
What's going on? What's going on, everybody who's actually listening to this podcast right now? First of all, guys, welcome back to another episode of The Nikhil Sai Show, which is hosted by me, The Nikhil Sai. And guess what's going on today? I'm back with another amazing guest. This story will probably help you more than you can think. And not just the story I'm talking about, but the solution we are going to talk about, which is probably one of the most important components of business, but which we really don't talk a lot about, and I'm quite disappointed when I actually did face difficulties with my own business when I'm trying to process payments, gone through different, different situations. I was an Indian registered business who had to deal with Stripe to accept payments from my international clients, and I could only charge them in Indian rupees. I had to pay crazy insane forex fees on it, and I was just getting shut down back to back with zero disputes, zero refunds whatsoever, and I just Couldn't fathom that situation overall, but I was able to escape it by creating a US company and shifting all my clients to my US merchant account later on. And it was decent, but I've heard many other agency owners and coaches, consultants, you know, high-level resellers, and many other people who are in the business of attracting international clients and keeping them on retention, especially high-ticket sales, who struggle with merchant account issues almost every other day. And it's a big potential loss. I mean, as a business, getting cash into the door is probably the number one thing you should be doing. And if you don't have a way to process money from your clients, you're just doomed overall. You're, you're, you're, you're bound to die. And, you know, it's just in no time. And that's where we are trying to save you from that situation overall with the guest we are having today. And the guy who's actually jumping on today has a very interesting journey. He's been an entrepreneur on and off for over 25 years now. So he has a wide range of experience in the world of business. And the best part is he is successfully revolutionizing close to 1,000 businesses at this point with their payment solution. And he's probably the well-known guy in the HighLevel ecosystem when it comes to offering payment solutions, which are absolutely alternatives to Stripe and PayPal and all the traditional solutions you actually hear. And it's cost-effective also. So we'll definitely get into this overall. Let's not waste any time and actually let's welcome the CEO of Numerik. Joshua Knox.
Hey Josh, how's it going? Thanks for having me. I appreciate the opportunity to talk.
Yeah, absolutely, Josh. We are stoked. I believe payments is a very interesting topic that nobody talks about, and I'm glad you are here today to teach us everything about how the payment mechanism works, the merchant processing, like what's the business model of Stripe and how can we make sure we're not boggled by them or, you know, doomed at any moment with it. It's like the Thanos snap, right? Like the snap and you're out of business. You know, we want to avoid that. So I would love to get into the nitty-gritty of things, but before that, Josh, I would like to know who Josh is. What's your personality? What's your story? And how did you stumble upon this business? What was your first venture like? How was your childhood? So walk us through your journey from zero, you know, to where you are right now. How was the journey like?
Yeah, sure. That's a big question because I'm getting close to 50. So, you know, as a kid, I just had a general sense about myself that I wanted to be a business owner. My father was in corporate America and spent a tremendous amount of time traveling. He would be away for 2 or 3 weeks at a time, you know, providing a life for us or our family. But there was a sense early on, like one of my earliest businesses was actually helping my mom. She was an entrepreneur at heart as well. Before I was even 10 years old, my parents owned their own businesses. And so I saw that side of it. I saw the failures of it. Sometimes a little bit of success, but there was something about it that I liked, right? And, you know, fast forward, my first business I started when I was 13 or 14, I had a pressure washing business. I lived outside of Seattle. Seattle has a lot of moss on concrete roofs, all that kind of stuff. So me and a friend thought we would start this fun little business and we would clean sidewalks and roofs and so forth. And that didn't last for very long as a 13-year-old, because it's hard getting around to the job site. But it, but if I fast forward beyond that, you know, I got married, uh, young, had a family young, and it's been a huge blessing. But as part of that, I worked in corporate America. I worked for companies like eBay and project management there. And then I wanted, I started going to business on my own before I was 30. Like full-fledged on my own, right? Minus the, this, the few little entrepreneurial journeys in my young teenage years. One of them was in real estate. Did a little bit of investing with that. And that didn't pan out long-term. Then got back into corporate America, worked for a franchising business that franchised trade schools across the US, running their marketing department. So, Fast forward a little bit further and in about 20, it was 2018, I believe, uh, my last entrepreneurial venture kind of fizzled out. It was okay. It made a little bit of money. It wasn't tremendous, but it fizzled out and I found myself back in the marketing world and I happened upon somebody who needed kind of like a contract CMO for their payments business. And to that point, you know, I had owned businesses. I had done marketing. I had worked in corporate America. I had worked for franchising companies, marketing sales, that, those sorts of roles. And when I found this payments company, I instantly was like, yeah, great. It's a job. Right. So I take the job and then start learning a bit about payments. And what ended up happening was they were all kind of spread out, right? Which is why they hired somebody. They were spread out with their marketing efforts. They had ClickFunnels, they had WordPress, they had MailChimp, you name it. And they had some type of tool. To help with some type of marketing. And I found HighLevel at the time, right around 2019, I believe. So pretty close to when HighLevel first started coming out. And when I found that, I started paying attention to the HighLevel Facebook community. And when people started talking about payments and because I was now in payments, I started thinking, well, we got to— there's got to be a way to sort of help out here. Right. And in marketing, when you find a gap in the marketplace, you can put a product in there and hopefully you know, service somebody with it. And that's honestly how it happened. We saw a gap in the marketplace. We saw people complaining about Stripe and their frustrations with them. And I'll add a quick caveat. I am not a Stripe hater. It is a good technology, but it is a good technology for different businesses. Anyways, we saw the gap in the marketplace and we, we just started building a tool. We built our software from the ground up. Then we started partnering with banks and other people that would help merchants, right? You're a merchant, I'm a merchant, we own a business, and that could help them. And so then we just tied that software right into HighLevel, and that's how it came about, quite honestly.
Yeah, yeah, absolutely. Love that. I mean, what I like about your thing is there's, I mean, tracking payments business is probably one of the toughest business, you know, even to have that trust from somebody to be like, Like, are you going to be processing my payments? And that's like where there's probably the most skepticism and most payment processors are not well known compared to Stripe and PayPal, which are the most traditional ones, especially for these online stores and whatnot. What was it like for you in the, in the early stage? How did you build that trust with the community overall to, to get those initial customers and how do you keep that trust up? Obviously the biggest part is delivering what your promise is, and I, I'm sure you're, you're doing a good job with that. But what was it like for you to get into the payments business first and build your own brand and get your brand up and running in the space?
Well, you probably know what it's like. It's incredibly stressful, right? When you're trying to, when you create a product and you're right, trying to get, you know, people to trust in what you're doing. The reality is, is you deliver the result. So if I say I can do this, in our case, if I can, if I say I can lower your cost 50 to 90%, then when you trust me to do that, I better deliver that. And because we can deliver that, we started gaining a name in the HighLevel community, gratefully so. You know, Sean and Robin and Varun have all been wonderful to us, giving us their time and their listening to us, but overall allowing us to be part of the community, talk about solutions inside of the community, which they do for a lot of folks, right? But delivering, but allowing us to deliver that result. The end of it. If I say I'm going to do something, I better deliver that. If I deliver that, then keeping the, our clients is just about taking care of them. If I respond quickly, if I answer questions right, if I'm passionate about what I say I'm going to do, do it and then continue doing it month over month over month. Our longest clients have been with us for more than 2 years now since we're only 3 years old. Right. So, uh, it's just about delivering the result. That's really what it comes down to.
Yeah, I completely agree. But can you give us a rough rundown? Like, again, we use Stripe even till date, and I think it's definitely a great platform. And you said an interesting point when you're starting the podcast, which is we are not Stripe haters, but I believe it's for a specific type of business is what you said. How do you differentiate that? Like, who should use Stripe? Who shouldn't use Stripe? Or if you should use both, like Stripe and an alternative payment platform like yours. How they could decide which is best for them overall?
Yeah. So there's a couple of ways that we kind of help people determine it, right? We're, we're of the opinion, let's give you the information that helps you make a good decision for your business. And which is why I say I'm not a Stripe hater. They're obviously, they're a very successful company. They've got a really, really great technology. That business piece, are you the right business for Stripe? So Stripe is like the American Idol of payments. They want literally everybody to come on board, audition for them, show them the business that they got, how many sales they're going to do. And then because they're so good at what they do, they can tell whether or not you're profitable for them. They can tell whether or not you're high risk for them. There's all these different factors that they can go through just in how they run their business to determine whether or not the two of you are a good fit. Fit for them. And if you end up being higher risk and not as profitable and some other things, then it doesn't make a lot of sense for them to keep your business because they would rather focus on somebody they could service better, right? It would be sort of the same as if you drove a Ford car, you wouldn't go to a Honda dealership to ask them questions about your Ford car, right? While they, while they still sell cars, both companies, There's a difference there in the, in the actual product, right? And so if you, if you think about Stripe and you think about a different payment provider, somebody like us, the difference is, is we want high risk. We know how to service that particular business. We know what they're doing. We've become experts at the GHL agency owner. So not just high risk business, but, but specific to GHL agency owners as well. And so while Stripe is again, a great tool, PayPal is a great tool, right? They obviously do something right. Are they the absolute right solution for your business? And the answer is only you can decide that. We simply provide you the information to help you decide that. So the second part of your question was, how do you determine if you as a business owner would want to use somebody like us? So I always say this sort of a catchphrase, if you will. A lot of people don't want the truth. They just want convenience. Right? So the truth is you can get a Stripe account, you can get it super fast, but the— and it comes conveniently, right? But the reality and the truth of it is, is they could also shut you down just as fast. And no matter how good your business is, right? You're very successful, right? Congratulations on all of that. You know that no matter how successful you are, if somebody shuts you off and you can't take money in, You don't really have a business, right? If you can't get paid at the end of the day, you can't pay your team. You can't pay your own bills. Like there's all kinds of consequences to you not being able to get paid, right? You're not going to just say, all right, everybody's got to mail me a check now. Right there. It just doesn't work that way. So you can have the best website. You can have the best copywriting. You can throw the best webinars. You can have the best sales team and appointment setters and all of it. And the second somebody turns off your ability to take payment, it's over, right? Stripe is good. I think we're better specifically to the community that we talk about, the HighLevel community, those who do digital advertising. Yourself is a perfect example. And you've just said in the beginning, if even if you've never had a problem, right, if you've never had a chargeback, you've never had a dispute, you've never had to worry about refunds. You've always delivered your product. You've got amazing clients and they all love you to death. You could still get an email tomorrow and Stripe could say, you know what, we've assessed your business and we're going to close your account. It's not for us. That's their right to do as a business owner. So when you think about that, and then you think about how we set up our businesses, which means I'm going to get you a traditional account. You're not going to share it with anybody else. When you go to Stripe, you're sort of sharing it, if you will. It's a sub-account of their main account. Kind of like a mailgun or something, if you will, in terms of email analogy. If you come to us, it's your account with a specific bank. Depending upon the volume that you're doing, if you're doing $50,000 or more a month, I'm going to say we're going to get a second account because for low extra cost, maybe an additional $25 in a month, and I'm already 50 to 90% less than Stripe and PayPal and Auth.net and all those other things. If I add another $25 a month and add another account, now it's virtually impossible for you to ever be shut down. If you have a problem with one, we just automatically through the technology, switch the volume to number two. And if we have a problem with one and we need to switch to number two, then I'm going to say, let's go get a third. And we keep two running simultaneously, work on the challenges in number one and get it back. Almost like if you had three lanes on a highway and you had an accident in one, we'd shift all the traffic to 2, fix the problem in 1, and then we get 3 open again. Does that make sense?
Yeah, it does, it does. I think that's a very interesting way to understand how the alternative payments actually work compared to the traditional ones. And it's like the, the biggest factor for you to sell is the de-risking for the business owner overall who is running the business. And yeah, I mean, it's a nightmare. I've seen businesses crashing down because of cash flow issues. And when you can't get cash in, guess what? Cash flow issue is obvious overall. And I've seen businesses suffering, especially the businesses we are into, right? Like, when I look at a high-ticket coaching company, a consulting firm, or an agency, or somebody who's reselling a software like GoHighLevel, for example, they have insane amount of subscriptions happening. And if their payment processor is gone and they cannot migrate their customers without losing customers, which is the trickiest part overall in the migration process as well, you're basically signing a death warrant for yourself, especially for your business. Really, really tricky. So I would love to know, you are saying an interesting factor talking about alternative payment solutions like yourself being 50 to 90% cost effective overall. And can you tell me how is that even possible? And give us an analogy, like what happens if there's $100,000 being processed in Stripe at a traditional, you know, solution level? And what happens in your platform? And how would that bottle down to how can you help businesses save 50 to 90% cost compared to a traditional solution overall?
Yeah, it's a great question. So the way we do it is we tap into consumer behavior, right? You buy things, I buy things, our friends buy things. We all have our own spending habits, right? So you might prefer cash, I might prefer a card, somebody else we know might prefer to spend crypto, something like that, right? But overall, collectively, we know that most people want to use a card to make payment for something. And they want to use, they want to do it for two reasons. They want their airline miles, their rewards points, their cash back, right? We all want the reward that Visa, MasterCard, and American Express want to give us. And two, the convenience. Now I'm going to add a third one. It's actually super secure for the consumer, right? So for those three reasons, consumers will choose, even when they're incentivized to not use a card, They'll still choose 98% of the time to use a card. So by knowing what consumers want to do and how they spend money in their individual lives, I can then use technology, what we specifically developed at Numerik, to let them use their power of choice on how they want to spend money with you. So I can say to them, hey, you can buy this product or service with a card, or you can buy it with a bank transfer or check, right? An online check. When I do that, I can transfer the cost of the credit card processing to them because they have a choice and they're still willing 98% of the time to use a card because of those 3 reasons, right? The rewards, the airline miles, the convenience of it, and the protection of it. Right. So when I tap into that consumer behavior, I automatically make my merchants winners. Every month, 50 to 90% less cost. Now, the second part of your question is what's the actual number? If you did $100,000 a month on Stripe right now, I can tell you it's going to average around $3,500 a month in cost. With me, it might be $120 total. So the savings becomes significant, right? Most people don't pay that close attention to the actual cost at Stripe because Stripe strategically did something very smart. When you take a payment in, they take the amount of their cost out of every single payment. So it looks much smaller when you're looking at an individual payment. If $100 comes in, they're like, hey, we'll take $4 of that. You're like, $96 is pretty good. At the end of the month, it becomes a bigger bill when you add it up. But most people don't add it up. So what ends up happening over time is Instead of it being 2.9%, it's really averaging out a little over 3, 3.5%. I still talk to merchants probably a couple times a month that are 4, 5, and 6%. They just don't know. And a lot of it is what you said right in the beginning. Most people don't pay that much attention to payments. They think it is just a tool instead of understanding that it's a strategy. The same as if you have a marketing strategy in your business. I'm going to spend my advertising dollars on Facebook ads and Google ads. And that's my marketing strategy to gain attraction and attention and make sales. But they think payments are everything's, uh, they think payments are a hammer and everything else is a nail, right? That's how people tend to think about it. They think, well, I should be able to set up an account and have it take me 2 minutes, but I'm going to spend 2 weeks or 2 months tweaking my website, making sure my messaging is right, the images are correct, the icons are correct. They'll spend all that time and energy on a website and then immediately just pass on payments. When you pass on payments, right? If I— let's just go easy math and I say it's $3,000 a month for that $100 grand at Stripe. At the end of the year, that's $36 grand. That's a lot of money. You can hire all kinds of new team members to grow the business because you, you move this way or that way because you now have more cash flow in your business to do so. So it's much more than that $3 or $4 per $100 that you're missing out on as a business when you don't think about payments strategically. Makes sense?
I love that. Yeah, it totally makes sense. I hope this is heard by a lot of high-level users or people who are selling, you know, a little bit compared to the normal industry, like high-risk, you know, processing overall. And this is Really, really insightful. And what I love about what you just mentioned, Josh, it's not just the $100,000 you're processing in Stripe and maybe losing focus on it. It's also if there is one little $2 transaction which is being disputed because of a duplicate payment, the entire merchant account could go wrong and the cost associated to not being able to process at the time and not able to have multiple accounts at the same time with Stripe and whatnot can drive you crazy. And with you, with any alternative payment platforms like yours, it's definitely, you know, you're passing on the credit card fees to the consumer because that's their choice. So they choose to pay additional. So you don't have the stress to ask them for additional money. It's just how the system works and you're paying a very small fraction cost. So it's making a lot of sense. And what I love about this is, Josh, if you take 4%, it might look like 4%, but if you look at the bottom line, let's say your business is net 20%, Bottom line, let's say you're generating $100,000 in revenue, you're making $20K net profit. If you keep extra 4% because you're charging credit card fee, you just increase your profit by 20%. Like just adding that processing fee back to your, yeah, back to your customer. And that's just, now you could just do 20% more things, meaning instead of buying 4 cars, you could buy 5. Like, isn't that exciting?
Yeah, no, it totally is. I mean, you're pointing out exactly what we talk to people about. And what often happens, I get, I generally run into two personalities. I could never do that. I'll lose sales. I can't believe you would even consider passing on. It's this sort of end of the world scenario in the head that I could never do it. Let me tell you who uses us. People that sell, resell HighLevel and they sell it for $97 a month, or they set up for $497 a month, but it also works for plastic surgeons that we have that do $25,000 and $30,000 procedures. LASIK surgeons that do $15,000 procedures. When they give their patient at that high dollar amount a choice, that patient 98% of the time still chooses the card. That consumer behavior is so powerful. All you need to do as a merchant or as a business owner is just tap into it. Just give somebody a choice and they will choose what's right for them 100% of the time. And so when you understand that, then the math really gets to be a lot of fun. Just exactly like you said, all of a sudden your profit margin goes up, your cash flow is up, and you can start making different decisions in your business that may have caused you stress before. I need to hire another team member to do XYZ, but I, I just don't have the cash flow. Doing this opens up a tremendous amount of cash flow in the business. Which then lets you as a business owner grow your business, right?
Yeah. Yeah. I love that. Appreciate the explanation. And let's talk about this. This is a very interesting dynamic. I mean, risk management, you know, for payment processing is probably the most— like they exist for that same reason. Like they just want to make sure that the right merchants are getting paid and the wrong merchants are getting penalized overall. And the people who are doing bad stuff, you know, it could be, you know, stealing credit cards or Casino or whatever it is, which is not good for the society, they should be penalized. Now, in your situation, I would love to understand from your perspective on how the de-risking is done for merchants who are actually processing. I'll give an example just so you understand more. There is, again, I'm not talking about the special snowflakes who have 100,000 customers who never had a dispute or refund issue. If somebody says I had never, I never disputed, I never had a dispute. I would say like you haven't done enough business. Like that's probably the reason you haven't seen dispute or a refund situation. If you have, you know, a few hundred customers, at least if you get to a few thousand and if you processed over a million bucks, there is no way you'll have that one guy who just want to, you know, revolt against you no matter what. So I would love to know in that kind of situations, what's the typical traditional solution does and how a platform like yours is de-risking and helping the merchants overall? Because I have seen my clients going through difficult situations when they get a refund or a chargeback, like their accounts get shut down, they need to re-verify their identity, they got to submit a lot of paperwork, and the likeliness of them actually winning the dispute is also close to none. So I'm curious on what do you think about the situations and what should the business owner think about while they're seeing these situations in their business and how can they actually do a better job while running this the situation?
Yeah. So when it comes to our side of, uh, of how we do things, we mitigate that risk by just understanding who that business owner is and, and where they're at as a business. Right? So if you think about a typical business, it's going to grow steadily over time. Yes, you can have launches. Yes, you can have new releases or you can have a new product that catches fire. But generally speaking, a business will grow in phases, right? You'll have the initial phase where you've got transactions coming in, sales coming in. That'll reflect in bank statements. It's pretty easy to see. There are just general financial patterns that happen. So when it comes to us, we look at all that in the beginning, right? Our bank partners want to see how your business has been operating. If it's an existing business, we, we can help new businesses, but mostly we help existing businesses. So we're going to take a look at those bank statements up front and just see how everything's going. We're going to see how much operating capital you have, what your average ticket price is, how much you expect to sell in a month. And sometimes it honestly just comes down to the math. So if you come to us and you say, hey, I, I really want to be able to sell $100,000 worth of stuff. Right. And I've got a great product and people are buying it, but we see your bank statements and you've only ever sold $5,000 worth of stuff and you got a nickel in the bank account. Then we're probably not going to approve you for $100,000. We don't want to set you up for failure. We want to set you up for success. So instead of giving you $100,000 in approved volume, we might say, let's start at $10,000 and let's make adjustments as you grow. Now, the other piece of that is, as I said in the beginning, if you really wanted to grow quickly, you knew you could do it, but you had higher risk because you had lower capital. Right? I see in the bank statement you got less money. We can still add a couple more accounts and actually increase your capacity that way. So the same way we think about stability of accounts, we also think about capacity of accounts. So think of it this way. If you go Christmas shopping, right? I don't know if, I don't know if you do Christmas in India. Let's, let's say you go birthday shopping. Okay. If you go birthday shopping and you spend money on a credit card, you have spending capacity. Capacity, right? Let's say you have an available capacity of $10,000 on an Amex card. Okay. Well, if you go out and get a Visa card and they also give you 10, now you can really spend $20,000. I'm not advocating go spend 20, but you have increased capacity. We can do the same thing with merchant accounts. So if you're a newer business, but let's say you would, you had run a business before, so you know how to grow a business, but the new one has just a little bit of capital, we'll get you 10 here, get you 10 here, get you 10 here. That's now 30. Does that make sense? So I can grow you exponentially while still keeping you safe and stable short-term versus long-term. Does that make sense?
Hmm. Yeah, it does. It does. So you're basically de-risking by creating lower limits, but multiple accounts. So even if they're over-processing, they could push that volume into multiple accounts. So they are just under the limit. And not getting that attention, which typically triggers, you know, a transaction. For example, in my case, I had a very fast growth in my company. As you know my story, I was an Indian business previously. When I processed a few hundred dollars transaction on the first few days, they were fine with it. But once I started processing $3,000, $5,000, $10,000 transactions, they were like, whoa, whoa, whoa. Like, who is this Indian guy, you know, charging 700,000, you know, like Indian rupees and whatnot. I was like, okay. Like there was something, you know, which, which, which was triggered overall. And I got into trouble for doing nothing wrong, but I solved it successfully. But I believe that's what you're trying to de-risk by creating those minimal accounts overall. Okay.
That's pretty interesting. We're trying to build stability. We're trying to, not trying, we build stability in early so that you can scale and grow long-term, right? When we build it in early, when we do the early work, of understanding who you are, what you sell, how you sell it, when you sell it, when you deliver it, all these things, we can build in a good foundation to then springboard you to that growth long-term, right? And it's still possible to scale quickly. We can add multiple accounts, or we can say sales are going really well. We get the bank to take a look at some things again. We keep an open line of communication with all of our banking partners for all of our merchants. Because it's a work in progress. It's not a, oh my gosh, that guy sold $700,000 worth of stuff. He must be trouble. It is, what did he do and how can we support it? Does that make sense? So we're not looking at it so much from, we don't really trust that this is real and we don't want to support it. We're looking at it from how can we trust it and support it short-term and long-term. So we do the work upfront. Same as if you would do the work to build a team, build a website, develop a marketing strategy. We just do it upfront versus drag it out over time or make it so simple that we can then take it away simply. I'd rather do the early work and mitigate the risk fast upfront so that we can grow together longer. Now you asked another question. You asked a question about handling disputes.
Yes.
Our thresholds are different. When we do that early work, when we really, uh, ask the right questions about your business from day one, then our threshold for chargebacks is gonna be higher, right? Because we know more about you and your business, and we can see that there might be a challenge here or there, but that's a natural portion. Just like you said, if nobody's ever had a single problem, they probably haven't done enough business. Understanding that business does come with its challenges lets us go, okay, there might be a few bumps in the road here. Okay. Did a bump happen? Great. What are you doing to take care of it? Okay. I'm doing X, Y, and Z to take care of it. Wonderful. Keep going. Whereas somebody like Stripe is going to go, you know what? That's just too much for us. We're just going to shut it down. We don't really have the time to get into it and talk to people. They're not really set up for that. And that's okay. They're not set up for it. And that's perfectly okay. We're set up for that.
Hmm. Yeah, I think, yeah, you're right. Like it just brings back to the same explanation you were given in the beginning of the conversation. You gotta understand what's the nature of the business and you know, who do you really want to transact with or, you know, be associated to your company with. And I believe having both at the same time is like a smart way to run it. But, you know, going all in with either one could be risky. So I appreciate that perspective and I kind of see the sense that they have more, you know, pessimistic view. Like if, if something is wrong, like if some, there's a new like new, new, new, new activity which is happening, which is not usual pattern. They want to trigger an alarm. But you have more of an optimistic view, like, hey, like, wow, looks like things are going right. Like, how could we support you? Do you need more alternative accounts? And can we help you with this or that? And yeah, it's a pretty cool situation here. Now let me ask you an interesting question which is ringing my mind for a long time. Overall, payments is a very unique— it's probably the most sensitive thing. Like, Usually agencies, right, they don't want to reveal their client's name or even contact info for the employees, you know, for several reasons, especially when you're talking about the below-the-line chain and whatnot. And we are living in a society where sharing passwords is also a little like tough. Like, you know, I don't want to trust somebody with my password. Like I want to use some secured password platform to share my password. And we are talking about client's information, sensitive payment information, and being able to recurring transact with them and have that relationship with a trusted payment platform. So how do you handle your compliance, you know, your security and your uptime overall at an alternative payment platform? Because at Stripe, I mean, obvious they have transacted, what if I'm not mistaken, I've seen an article where they have transacted like a trillion dollars or something through their platform. And I was like, mind blown. I was like, what? Like they're almost controlling 70% of the flow in US, and which was surprising to me, like, wow, like, that's a monster right there. Like, they could control any business if they really want to. So I'm curious on how do you deal with that overall perspective of security compliance and sensitive information, and how a client could be rest assured that your platform could actually give them that, you know, side of business where they could trust you and do long-term business with you?
Yeah, so it's a great question. So I'll use Stripe as an example. I think last year, you're right. They did about $1 trillion in volume. Payments run on what are called payment rails. There are processors that transact the business on the backend. Most people don't know that part of the business, mostly because it's not that sexy. It's just right. At the end of the day, Stripe is a software and there's a bank on the backside of it, a couple of banks that help process that volume. It's just how money works. The banks on the backside of ours, our payment rails have done more than double that in a year. So we are tied into the second largest processor in the US. So our software that transacts the business, which is what Stripe is doing, right? It still runs through a bank. There's still a gateway. There's still a bank. There's still payment rails, there's still card brands. All of that part of the business is so similar that most people wouldn't recognize the difference between one or the other. The difference in the softwares comes down to obviously, you know, brand identity, user interfaces, that sort of thing. The security is just part of how all of us operate. Now, are there some that are probably less secure? I'm sure there are. But for us, everything from top to bottom is what's called PCI compliant. So from the processor to the gateway to our software, we tokenize all of our payment data, which is more secure than encryption that actually gets tokenized and it lives offsite. We don't hold that. We call it back when it's necessary to call it back. So we keep ourselves and our clients 100% secure and we have 100% uptime. And it's because of how we've built the system that allows us to do that. When you, when you build it sort of, what's the best way to describe it without losing people? If you build it sort of in a component status and every one of those components has 100% uptime, then you generally don't run into problems because you, you can sort of move pieces in and out if you did have a problem. If that makes sense. So yeah, we're, we're 100% PCI compliant. Every one of our merchants is automatically from day one, once they start, 100% PCI compliant. And we can provide proof of that. In fact, we, we're, we have the ability to import Stripe data into our system. So if you're doing $100,000 a month and you've got 200 clients and they're all going through Stripe right now, and you say, hey, I want to move to Numerik, you don't have to collect the cards again. We can just import that Stripe data. In order to be able to do that, we have to prove to Stripe that we're PCI compliant to the highest level. I send that information to Stripe all the time when, when people make the request and Stripe instantly sends us the data. So they can't do what they're willing to do and we can't do what we're willing to do if that connection and that data security doesn't exist. Does that make sense? Sure.
Yeah, it does. It definitely does. So you're basically giving that confidence for people who actually need that reassurance that Everything is safe and secure. And yeah, I mean, that was probably like one of the things, you know, like I have actually heard, like, I know people who got stuck with their Stripe account. They keep their business shut for a few weeks to resolve the issue with Stripe instead of trying an alternative. I was like, why don't you try like an alter— they were like, I don't trust— I'm like, you know what, you're signing up for death if you don't get an alternative overall, you know, like you're not guaranteed to get your account back or get an alternative account open up. With them, you know, you gotta have a different LLC and then they will not trust you because you can't process like so much transaction with the new LLC in a very short period. So there is definitely a lot of trust. So let's get back to, you know, a few, a few different questions we have for the series. So can you walk us through the typical tools you use on a daily basis to manage your clients, your personal productivity? One thing I like about you is you talk— you have close to 1,000 people who are actively using the software. You have had contacted with thousands and thousands of HighLevel users potentially can be your partners, but you still manage that personal touch element in your conversations. So I'm curious, do you use your mental brain and your natural ability to do that, or do you have a system around this? I would love to know what tools do you use on a daily basis to run your business?
Yeah, thanks. There's a lot of mental power that goes into it for sure, but we use HighLevel. That's one of the tools that we use to manage our business and it's a big, big tool that we use. Um, for me, I just like people, to be honest with you. And because I like people and I like having conversations, I generally have been blessed to remember who I'm talking to, what we've talked about. The bigger we get, I will say, the harder it is getting to remember absolutely everybody. But if I've had an interaction with somebody, generally speaking, my brain can recall, you know, what we've talked about and and so forth. The more, obviously the more I interact with them, the more that deepens the connection with them. But yeah, we use HighLevel. We have our software, um, and our software actually has a little bit of a CRM component to it, but it's a lot of it's just attached to GHL. And then we have, uh, our bank providers, uh, tools that we use. So one of the unique things that we've done is we've brought the app— so when you get a merchant account, You have to apply to what's called a sponsor bank, and that sponsor bank then re-reviews the application and the supporting documents. It's honestly, it's all the same data you're already giving to Stripe. They just ask for it over months of time. We ask for it right up front. Just tell us everything right up front and we can get you going. But when you work with multiple providers, we have 12 to 15 banks that we can send our merchants through to get approved. When you do that, every one of those people has, or providers has a different application process. We've brought it all in-house. We built our own application. It lives in our software. So you can apply to us and then we can send it out to where we need to send it out to get the approvals to, to have everything managed in-house. So we've got GHL, our software, and then we've got bank softwares that we work with.
Hmm. Interesting. Makes sense. Can you walk us through a typical day? Like what do you do from the time you wake up to the time you sleep? How does your average day look like?
Yeah, I mean, I get up, I go to the gym first, uh, then I study in the morning. Um, I'm a spiritual person, so I study scripture and, and that sort of stuff. Um, and then I get to work pretty early. I don't know, 7 o'clock, 8 o'clock in the morning, and I just start digging into the projects that we have going on, or if somebody needs a question answered, um, I'll do that. I still am very much involved in the day-to-day stuff, although this, this quarter it's gonna shift off my plate. So, and I work with the team, we have team meetings. So I talk to the sales team, I talk to our application team, or I talk to our development team. I talk to my, I've got a business partner, we talk. But yeah, I mean, it's, I think it's a typical working day. I get up and work the business and do what's required to support our clients and, you know, continue to make a product that we're pretty proud of the innovation that we do and how fast we can develop and get to market with some of the features that we develop inside inside of our payment software. And so that piece I really, really enjoy. But yeah, I mean, day-to-day management stuff of a business, my favorite part's talking to clients.
Yeah, I could see that. Now, what, like most times when a business is going after an alternative payment platform, you know, this is not traditional, like I'm talking about not Stripe or PayPal, like a newer company or smaller company like yours. The biggest problem they would think about is, will I be capped? I, again, you kind of answered that question by de-risking into multiple accounts, but if you could share, you know, any information on how big of an account you could actually manage, that would give people who are listening who might want to consider working with you a little bit more confidence. Like, okay, like if even if I could get bigger, like that's the scale which I'm looking at, at least at an active transaction standpoint. So what would that, peak look like, maybe at a yearly business or maybe at a monthly transaction volume, if you could give some rough idea.
Yeah, there's, I mean, to be honest with you, it's going to sound super cliché. There's really no limit to what we can manage. The technology is built in such a way and our banking providers are built in such a way that we could handle multi-seven-figure businesses a month. Like they're doing a couple million dollars a month in volume. We could easily handle that. Uh, I have found, you may have found this to be true as well. Those clients that are doing the most business actually take the least amount of effort to manage. New business owners tend to be a little bit more stressed, tend to see every nickel and dime, and that's okay. That's part of the nature of growing a business, right? But what I've noticed is our biggest clients are that, you know, do lots and lots and lots of volume every month. They take the least amount of management effort. So yeah, we, we, I mean, we could easily handle multiple millions a month per one client.
Hmm. That's interesting to know. Can you, if you could go back, Josh, and talk to the 20-year-old yourself, you know, who was probably getting married early, starting a new family, you know, and maybe, you know, getting into corporate very soon. And if you can give yourself an advice, What would that be?
Believe in yourself. That, that's the number one thing that I think, I don't know if it's just young people, but I think entrepreneurs in general don't have enough belief in their ability. Um, it's hard, right? You know, you, you're a young person, but you're all, you're already very successful, but you had a, there was probably a belief in yourself that you could just keep going. No matter how hard it got, you could keep going. And so I think if I was to go back to that younger self, while I had a general hope that I could be successful, I don't know that I really believed in myself that early on. In fact, I could tell you, I didn't. I think I got married at 23, was a father by 24. Um, I'm not quite 50. We have our first grandchild now. So my oldest has already had her first child. I don't think I had that belief in myself when I was that young. I think I knew how to do a couple things. I think I knew how to work really hard for another company and use my God-given abilities to do good work for somebody else. I don't know that I had the belief in myself that I could support a family that young on my own, if that makes sense. So short answer, believe in yourself.
Yeah, I love that advice. And I mean, for entrepreneurship, right? Like, so lonely, and it's you working in a corner office with a laptop in your lap with no desk in the beginning, and you gotta trust yourself that you're gonna make this big. It is tough, and there is nobody else who tells if you're doing right or wrong, and you can only see the ship burning all over the place. So it's, it's really tough to— I mean, we all feel that emotion you have gone through, and I think it's great advice for people who are listening as well as a good reminder. Now, Josh, if you could go back and talk about your achievements you're proud of, what would that be? And what's your big goal, which you would like to achieve in the next coming years?
Business or personal?
Both.
Both. So first and foremost, in my world, there's a pretty famous saying that says no success in business will ever amount to anything for failure in the home. Uh, I didn't quite word that right. So for me, the, the, the thing that I'm most proud of is my family. Um, my kids and seeing them be successful. Um, my wife who I'm super grateful for. So in, in my personal life, that's the most, I mean, it just in life in general, but personal and business, that's the most important thing. No amount of success in my business will ever match that success. Having said that, I've been given a huge opportunity that I'm grabbing with both hands, and that's to serve tens of thousands of business owners with payments. And so if I were to say, you know, so far, what have we achieved? I mean, listen, we compete against Stripe and I wouldn't say it's a win game and a lose game, but we're competing against somebody that has done a trillion dollars in business. Who has been given the keys to the GHL kingdom because they're that much further advanced in terms of business lifetime and technology. But I think we've come up with something that's hugely comparable in terms of what it can do. So the software that we've built at Numerik has a tremendous amount of ability that already matches what Stripe can do. Building that backend of that, the structure to support tens of thousands of businesses, that's the next goal. The next goal is to be able to have this same interaction with our clients that still lets us scale to 10, 20, 30, 40,000 users.
Yeah.
Yeah. That's the—
I love that.
That would be the end goal for us. I, now I would also then add If I can bring on my kids or my— I have one son-in-law right now. Eventually my kids will all get married. But if we can then bring them into the business and have them, you know, have a legacy business to run that they love as much and provides for their families, that would be almost the ultimate.
I love that overall. So if you could share the biggest mistake you have made, which we all can avoid, making again, what would that be?
Not listening to the experts, right? There are people that have been where I'm trying to get to. Same for you. There have been people that have been where you're at, right? There are the people that are listening to this podcast. There are people already at where you're trying to get to. Listen to them. They have made mistakes that you can learn from so that you don't have to make the same mistake. That doesn't mean you won't make mistakes and you can choose to call them mistakes or learning lessons. But at the end of the day, if we would listen to those who have already been there before us and let go of our ego, then we can get to our goals faster, either in the current business that we're trying or the next one that will be successful. Does that make sense?
Yeah. Yeah, it does. It does. I think Coachability is, you know, one of the most important traits to be ultra successful in life, you could— you just know so much. And if you have the ego that I know it all, then yeah, you're just not going far away. That's, that's what I could say. And that's why I love mentorships and programs and, you know, masterminds, communities, and podcasts and whatnot where I could learn from other people. So appreciate you sharing that advice. What inspires you, Josh? Like, what's your motivation to wake up, get to work, build the software, help other people process payments?
That's a great question. I think the general nature of having something that impacts people's lives the way that it does, you know, our, our top clients are saving over $10,000 a month in cost, which then helps them grow their business because like we said before, the cash flow. I think the piece that gets us to that point though, is the fact that we can keep innovating what we're doing. We can keep Whether it's a small tweak or a big innovation, that's the stuff that excites me on the business. I get up and I might listen to a podcast about marketing and it might tweak my brain to think about the business in a slightly different way where I can then go, all right, that would be great if we could do that and offer that and provide that. That's what gets me going every day, or as you say, inspired. It's thinking about how much better we can still get. And I think we're pretty good. But I, but that, that aspect of, can we do this a little bit better? Could we do that a little bit better? That one needs to be really improved or that one's already doing well. Can we make a small tweak to it? That's what excites me. Yeah.
Yeah. I love that. I mean, if you're better 1% every day, you are at least 3 times better than, you know, where you are originally starting, you know, from 1 year from now. So that's so important. Now, if somebody's listening to this podcast and they now realize the importance of having an alternative platform, how can they reach out? What would be the best place for them to try Numerik?
Yeah, you can go to our website, numeric.com. It's not spelled the same as the word numeric, so everybody always asks us, how did you get your company name? Numeric, the way we spell it, N as in Nancy, O-O as in Mary, E-R-I-K dot com. Is the phonetic spelling of the word numeric, which is numbers, right? So payments are about numbers. Your business is about the right numbers. Um, so that's where the name comes from. But yeah, you can find us at numeric.com. And, uh, if you're in the HighLevel group, uh, look up my name, Joshua Knox, in the HighLevel group. Uh, you can find me generally talking about payments, answering questions. Every once in a while I'll have a smart thought. I know how to answer a GHL specific question. Um, yeah, that's how you can find us.
Perfect. And any last words for us to conclude the entire podcast for today?
Just keep going. Just keep putting one foot in front of the other, uh, and just keep believing in yourself and you'll get to where you need to be.
Appreciate that advice. I think that's so powerful. Josh, thank you so much for taking out your time and giving a mini masterclass on payment processing for our fellow entrepreneurs. Who will definitely go through the difficult situations we have talked about. It's a part of entrepreneurship, and appreciate you sharing different insights and helping us understand behind the scenes on how everything works in payment processing so they can make a decision for themselves. So guys, hope you learned the importance of having an alternative payment platform. It could be Numric, it could be anybody, it could be you having an alternative way to actually collect money. It doesn't matter what you do, but have that de-risking factor in your business because if you can't process payments, you don't have a business. Keep that in mind. I've seen situations where businesses break down to zero when they don't have an alternative payment platform. So please keep that in mind and hope you enjoyed this podcast. Share this podcast with other entrepreneurs who would enjoy this show and stay tuned. I'll be back with another amazing guest just like Josh. Thank you so much for tuning in.
More from Nikhil
BURNED $1.5M in his 17years online #digitalmarketing #entrepreneur #onlinebusiness