Agent Accreditation intro video #realtor #realestateeducation #realestateagent #buyersagent
The video, presented by Beth and a supporting speaker, introduces Ownify – a shared‑ownership program designed to make homeownership attainable for first‑time buyers with as little as a 2% down payment. The program treats a home as 1,000 "bricks"; the buyer purchases 2% (20 bricks) up front and then pays a single, fixed monthly amount for five years that covers (1) a portion that buys additional bricks (building equity), (2) all home‑ownership costs (property tax, insurance, repairs), and (3) an occupancy fee. Ownify handles closing costs, inspections, and repairs, and provides a full‑cash offer to sellers. Eligibility requires a single‑family home priced $250‑$750k within the Triangle MLS, a credit score of 680+, U.S. citizenship or permanent residency, and first‑time‑buyer status (no current mortgage). The program targets three buyer personas – the "Renting Pro" who assumes homeownership is out of reach, the "On‑the‑Fence" buyer wary of market risk and repairs, and the "New‑Start" buyer after a life change. A side‑by‑side financial comparison shows Ownify’s lower upfront cost and comparable or lower monthly payment versus a traditional mortgage, while the rent‑and‑save route lacks equity building. The video outlines the payment schedule, equity accumulation (e.g., $34,778 equity after five years on a $300k home), and three post‑term options: renew for another five years, use the accrued equity as a down payment to obtain a mortgage and buy out Ownify, or cash out equity and have Ownify relist the property. Funding is achieved through fractional ownership: Ownify contributes an 8% co‑investment, investors purchase the remaining 90% of bricks, and the buyer ultimately holds 10% after five years. For agents, Ownify offers a new market of renters, full‑cash offers with fast (12‑20 day) closings, reduced workload, and a dedicated portal with accreditation, tracking, and marketing tools. The video concludes with next steps: an operational video, accreditation quiz, and portal access, and provides Beth’s contact email for further questions.
Chapters
Hello, thank you for taking the time out of your busy day to watch this video about Ownify. Ownify is a new product that helps provide a new path towards homeownership for first-time homebuyers. Our mission is to rebuild the path to homeownership to make it achievable for the next generation of homebuyers. The current first-time homebuyer age is 36, and our goal is to help bring that down to allow people to start building wealth and financial independence much earlier in life. We believe that happiness is owning your own home. We want to be able to create happiness and financial independence by making homeownership achievable. We want ownies to be able to live their future now, buying the home they want to live in and being an owner from day one. What we're going to do is watch a very quick high-level overview of Ownify. And on the other side of that, we'll kind of dive in a little bit deeper into the nitty-gritty of how it works and who we are.
Ownify has developed a new way to help first-time homebuyers buy their first home with only 2% down payment required. We take care of all the rest: closing costs, due diligence, earnest money, inspections, and repairs. The first step is to save your 2% down payment. You can use your own money, or family and friends can chip in and help. Once you've saved 2%, Ownify can help you buy your home. The next step is to get pre-qualified. Visit Ownify.com to apply. Our simple online application takes just minutes to complete. Fill in a few simple fields with your information. If you're buying with a partner, simply add them to the application. We'll email them with the next steps. Ownify then quickly performs a soft credit check to make sure you're eligible. This doesn't impact your credit score in any way. Once your credit has been checked, Ownify verifies your income and identity. That's all it takes to see your personalized home buying budget. You're now pre-qualified. It doesn't cost you anything, and you aren't committed to our program. Your home budget is the maximum home price you can buy with Ownify. We're also showing you an illustrative payment schedule using your maximum home buying budget to display the 5 years fixed monthly payments. The next step is to sign the Ownify agreement and submit your $500 application fee. Half of this fee goes towards your 2% down payment, while the other half is refundable if you don't end up buying a home with Ownify. Now we're ready to move forward as partners to purchase your new home. You can work with your agent or we can recommend a great agent in your area. They'll help you find the home that's perfect for you within your Ownify budget. And while you're looking with your agent, Ownify is working hard behind the scenes. So when it's time to make an offer, you can move fast. Once you find the perfect home, we update the agreement with details of the home and send you the actual 5-year fixed payment schedule. After you sign the updated documents and send Onify the 2% down payment, your agent can submit our full cash offer, ensuring you look attractive to the seller. Onify's experienced closing team takes care of everything from this point to win the home, working with your agent and local third parties like an inspector and closing attorney to finalize the deal. The day has come when you receive the Please. We're thrilled that you have partnered with us to purchase your home. You are now an ONI and have freedom and flexibility as shared owners in your home. Stress, worry, and uncertainty are things of the past. So how does shared ownership work? Well, think of your home as 1,000 bricks. With the Ownify program, you buy 2% of the bricks on day 1. 2% is equal to 20 bricks. In partnering with you, Ownify owns the other 98% of the bricks, and you pay rent on the bricks you haven't bought from us. You buy more bricks every month. Over time, you own more of your home outright, reducing the bricks you have to rent from Ownify. You're buying your home brick by brick. One simple monthly payment covers your occupancy, repairs, taxes, insurance, and buys more bricks every month based on the current home value, building your equity ownership in the home. Ownify will arrange and pay for any necessary repairs. You can relax knowing that if anything goes wrong in your home, a leaky roof or a broken water heater, we have it covered. We only work with trusted local contractors to make repairs. Ownify covers everything for your home from property taxes to insurance. The only things you need to organize are utilities and internet service. As an Owny, you can decorate, renovate, and even remodel your home. Of course, any major work needs to be permitted and approved by Ownify. Once you buy out the remaining BRICKS from Ownify, any increase in the property's value based on the improvements you have made is yours to keep. Ownership on day one. No mortgage. Affordable payments. Ownify, a revolutionary new path to homeownership.
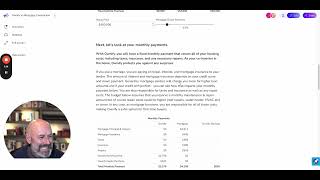
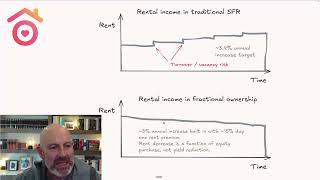
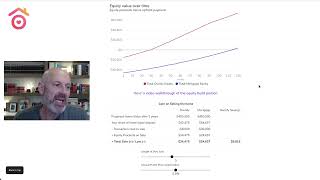
I just think that that video does such a wonderful job of giving that high-level overview of Ownify and how it works. So now we'll dive in a little bit deeper and be able to see exactly how do we make this happen. But first, let's do a little quick overview of how do we compare. This chart is fantastic because it shows how Ownify is able to take the best of both worlds when it comes to renting and owning and having a mortgage. So with Ownify, you're going to have equity ownership from day one. You're going to know exactly what your payment is for the next 5 years, no matter what, it will not change. The onee is going to have the ability to renovate and remodel. And once they do a renovation, if there's an additional appraisal, if there's additional value added to the appraisal, that is theirs to keep. Keep. We do not take that from them. There's an affordable upfront commitment with Ownify because we only need the 2% down. We do not need the, the super big commitment needed with the mortgage. Repairs are included, which is fantastic for first-time home buyers who are nervous about the worry of something major going wrong with their home and having to come out of pocket for that repair cost. We also include insurance and property tax. Making it easy on the ONI to just move in and enjoy their new home. So what does qualification look like? For the property, the house or the property that the ONI is going to choose must be a single-family home. We are not doing townhomes or condos. We will eventually perhaps move into townhouses, but at this moment Both of those are off the table. The property needs to be for sale. It needs to be not under— it also cannot be under construction. If it's within 90 days of completion, we will definitely work with the builder and the buyer to see about getting that deal done. Though the value for the property needs to be between $250,000 and $750,000, and the property needs to be listed within the Triangle, located within the Triangle. And that means any, any area that's within the Triangle MLS is something that Ownify will be able to purchase. It does not have to be listed on the Triangle MLS, but it needs to be within the locations that are included within that MLS. And HOA fees are permitted, so we will just kind of tack those into the monthly occupancy fee that is paid to Ownify. Now for the customer, when you're talking to your buyers, keep in mind that these are the qualifications that we have regarding their ability to use Ownify. Their credit score needs to be at least 680. They need to be a US citizen or a permanent resident. We're going to do an affordability assessment based on their current income and payments that they are making and give them a budget regard— with that information. They also need to be a first-time homebuyer. This is a very loose definition of first-time homebuyer. Ownify's definition is that you are considered a first-time homebuyer if you do not currently have a mortgage in your name. You could have paid off your mortgage last week and you are now considered a first-time homebuyer from Ownify. So as agents, when you're thinking about who in the world can you take this product and, you know, educate them about Ownify, your target customers, we've come up with 3 that seem to fit the mold the best. The first one is the Renting Pro. This is the person who doesn't even think that homeownership is a possibility. They figured that they're going to be renting for many more years and haven't even started to think about it. They are an untapped market. And we believe that this is going to really hopefully change things for them. And allow them to start building wealth much earlier. The second is the on-the-fence buyer. We've all had the buyer that is on the fence and super nervous about all the things that could go wrong with owning a home. They're worried about the market tanking. They're worried about depreciation. They're worried about the major repairs. Ownify is your solution for that because that helps give them stepping stones into homeownership. And the third is the new start buyer. The new start buyer, you know, perhaps has gone through a life change such as a divorce or they've sold their big— a couple sold their big house and need something smaller. We are here to help them as well because they're still considered first-time home buyers once they've sold that original property. Um, and we are going to be able to take away some of the stress that comes along with the home purchase and make life easier for them. With Ownify, there is just that one simple monthly payment that the onee is going to make, and that payment includes 3 different things. The first being the home equity purchase. So each month that they make a payment, a portion of that will be going towards purchasing the bricks for the home, and that at the end of 5 years, as mentioned in the video, they will have 10% equity in the home, which they can use to do a couple of different things. Which we'll talk about in just a minute. Next up in the payment is also homeownership costs. So we factor in property taxes, insurance, and repairs that are covered. Everything is built into the one price for the home. And then the occupancy payment, which is the ability to live in the home, it's your exclusive occupancy rights. Now based on the home purchase of $300,000, you can see here how Ownify compares against a mortgage and the ability, the Rent and Save. So the upfront payment is just $6,000. That is the 2% equity buy. That gives them 2% equity on day 1, and their monthly payment is $2,484. Each month, approximately, they will be buying about $406 equity that goes towards them owning more bricks in the home. Everything is included in the payment, as mentioned before. Now with the mortgage, we put down $30,000 for the upfront payment because we understand that, you know, you're going to have to pay the, the closing costs and the due diligence and the earnest money and the inspections and all the things that come along with purchasing a home that aren't included in just, you know, obtaining a mortgage. With the mortgage, you can see that, you know, they have a payment of $2,554, which is a smidge higher than with Ownify. But if you look at the principal, as we all know, mortgages are front-loaded with interest. So at the beginning of a mortgage for the first, you know, big chunky years, most of the payments are going towards interest. So it's kind of fun to see that with Ownify at the beginning of the payments, Ownify, you're buying more equity in the home than you would be with a mortgage. The rent and save is, you know, the third option, and it is the, you know, you can get in for an upfront payment of less than what the 2% would be, but at the same time, you are not building wealth. You are actually spending $500 a month in addition to your rent trying to save up money so that you can eventually have a down payment. So as you can see, it looks like Onify is the clear winner here for a lot of people. Here is an example payment schedule for a home purchase at $300,000. So as you can see over the years, the years 1 through 5, the total payment does not change and from that $2,484. The occupancy payment and the equity buy do fluctuate a little bit over the years, but the payment stays the exact same. And as you can see, as the years progress, the equity stake is increasing, as is the equity value, leaving the buyer with $34,778 at the end of 5 years. Now, the main, one of the big questions we get all the time is, so how does the ONI exit the situation? How does the ONI, what happens if the ONI wants to leave early? The ONI is allowed to leave whenever they want to. Just like with a mortgage, if you leave between years 1 and 3, you're gonna have to pay, you know, it's gonna hurt a little bit because you've put so much in and it's too soon to get anything back out. So that's kind of along those lines. We definitely recommend that the ONIs try their best to stay for at least 3 years. We understand things come up and we will absolutely work with them. But this slide, we're gonna talk about what happens at the end of the 5-year contract term. There are 3 different scenarios that can take place here. One, the ONI can decide to renew. They're perfectly happy with the way things are going. They love working with Ownify and the stress-free life that they have with Ownify. So they are allowed to renew for another 5 years and stay in the home. Nothing changes here except for they have more flexibility with their equity buy. If they come into a big chunk of money and they decide they want to up their equity payments each month and buy more bricks, that is perfectly okay. If something happens where they need to pinch some pennies for a while and they want to stop buying equity in the home and reduce their monthly payment, that's perfectly okay as well. So after year 5, they definitely have some more wiggle room as far as that goes. The second option is, is they could use their 10% equity that they've accumulated as a down payment for a mortgage and, and buy Ownify out from the home. So at that point, the LLC that has the buyer and Ownify on the property will be dissolved. The buyer will then have the— own the home outright with the mortgage, and Ownify will move along onto the next property. The third option is they can cash out their accumulated equity minus the 2% listing fee, which we collect in order to be able to relist the property and get it back on the market. They will be able to say to us, make a phone call and say, "Hi, we have decided that we would like to move on." What we will do is, you know, give them their equity and they can move on out of the home and we will then list the property. They are not responsible for listing the property. They are not responsible for anything other than just letting us know what they wish to do. So a lot of questions, a lot of times we hear, "How is this possible? It sounds way too good to be true." Well, it's not. We have some really smart folks who behind the scenes have come up with an amazing, amazing way to help everybody out in this situation. So on day 1, the owner, the owner has a 2% ownership stake in the property with that down payment that they make. Ownify as a company puts in 8% co-investment for a total of 10%. That allows an additional 90% available to be purchased, the bricks to be purchased by investors. So how that works is we are going to have something called fractional homeownership, and the ONI will continue to build the equity at the same time that the general public can come in and purchase bricks of the home and help build their wealth as well. This is helping keep the properties out of institutional investors' hands and help get more first-time homebuyers in homes. It's going to be amazing because the, the owner has the comfort knowing that this is their home. They're not going to have to worry about, you know, somebody coming to show up on their property to have a picnic. No one's going to really know where the home is. They're just going to have the information about the home. So the owner doesn't have to worry about that as part of this process with this funding model. It's just another way to make sure that the properties remain in buyers' hands and not the institutional investors, and we can allow more people to actually own property as opposed to just renting the property. So at the end of the 5 years, only, well, over the next 5 years with this funding model, UNIFI is selling our 8% share to the ONI so that at the end of the 5 years, the ONI has that 10% equity. Now, this does not mean that if the ONI decides to sell, they have to worry about any of this. All this means is that this is how we are funding the property, and this is how we are really and truly trying to help clear up the problem of first-time homebuyers not being able to get into homes. So why would you as an agent want to work with us at, at Ownify? Well, we've come up with some great, great ideas of why you should. One is you're going to be able to turn that whole entire untapped market of renters into buyers. Once they get a wind of this, then hopefully they're all going to want to come and use Ownify to be able to start building their their own financial independence. You're going to be able to win more deals because with Ownify, we are presenting a full cash offer with a quick close. As you can see on the next thing where we have fast and certain close, we will be able to close the deal within 12 to 20 days if that works out for all parties. We will also reduce the time and effort by 50% approximately. We figure there's a lot that's gonna be taken off your plate as far as this goes, but you will still be getting paid your full commission. Now what happens when that owning decides that they want to move on at the end of 5 years or anytime before or after? What we're going to do is we're going to call you as the buyer's agent who put the buyer in the home and give you first right ability to list that property if that's what you would like to do. So therefore we've come up with these reasons that we think that will make life Great and wonderful for an agent to work with us at Ownify to be able to put more first-time homebuyers in homes. So now that we've gone through all of this fun stuff, the next steps. One is introduction to Ownify. You have just done that. Thank you for sticking with me. Next up is an operational video where I will dive in a little bit more into the actual process that goes on when a buyer decides they want to work with Ownify and what that looks like for you as the agent. After that, there's a quick, easy accreditation quiz that will not take very long whatsoever. And then once you've completed that quiz, you will be able to have it— you will receive an invitation in your email to join our agent portal. This is an amazing tool that I highly recommend you check out. We have, um, all kinds of one-pagers and videos and information just for agents on that portal. In addition to that, you're also able to invite your buyers via the portal so that when that, you know, once you've invited them and they've started the process, you're able to actually track it through that backend portal to see exactly where they are and if they get snagged or if they have questions or where they're at, and you'll be able to kind of watch it in real time. It's a wonderful tool and we highly recommend that you utilize it. And this will actually allow you to win more deals. So I want to thank you guys all very, very much for taking the time to watch this video. Feel free to shoot me an email. My email is on the screen, beth@ownify.com. I am also very happy to, you know, do a one-on-one meeting if you have further questions. I look forward to meeting you as an accredited agent. And I hope you have a wonderful day. Thank you again.
More from Frank
How to Save 5-7% on Your Home Purchase. #firsttimehomebuyer #homebuying #buyersagent #mortgage
Ownify University: how does the purchase option in fractional ownership work?
Claude MLO Agent boosted homebuyer engagement by 8x! #mortgageloanofficer #mortgageloanoriginator
Wall Street vs First Time Homebuyers Understanding the Housing Market #housingmarket
Homeownership: Your Ultimate Wealth Builder Explained by Frank Rohde #housingmarket