In this presentation, Frank Rhode, founder and CEO of Ownify, outlines the Ownify Home Fund, a platform that fractionalizes starter homes into 10,000 tradable shares called “bricks.” The fund aims to address the current home‑affordability crisis for first‑time buyers by allowing them to co‑own a home while providing investors with strong, AI‑backed returns. Rhode introduces the founding team’s mortgage, real‑estate, impact‑fund, and finance expertise, and describes the fund’s expansion across markets such as the Triangle, Charlotte, Nashville, and Dallas. He details the fund’s performance—approximately 19% annualized gross return, 100% on‑time payments, 4% vacancy, 100% occupancy, and maintenance costs roughly 80% below industry averages—driven by a sophisticated AI underwriting engine that qualifies only about 2% of applicants and selects high‑quality properties. The presentation highlights five core levers of value: home‑price appreciation, superior rental yields (enhanced by buyer choice and long‑term leases with rent escalations), perfect occupancy, flawless credit underwriting, and the co‑ownership mindset that reduces maintenance costs. Investment options include straight limited‑partner stakes (target 16% IRR, 8‑10% preferred returns) and joint‑venture/custom portfolio structures. Contact information is provided for interested investors.
Chapters
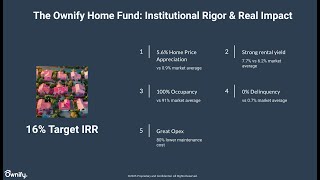
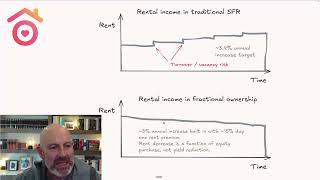
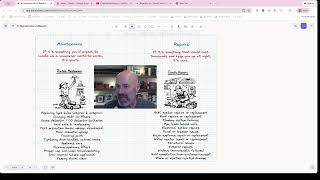
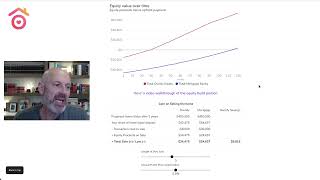
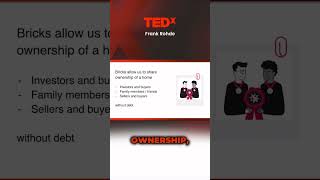
Hi everyone, my name is Frank Rhode. I'm founder and CEO of Ownify, and I just wanted to give you a quick flyover on the Ownify Home Fund investment opportunity. Home ownership reimagined. What we're doing is enabling first-time home buyers while partnering them with investors to generate strong returns. As you all know, buying a home is a cornerstone of the American dream. However, today it has never been more difficult, especially for first-time home buyers. Home affordability is the lowest in over 50 years. Between home prices, mortgage rates, the down payment requirements, student debt weighing on people, more and more first-time buyers are getting squeezed out of the market. So we've come together as a team to build a solution that solves this problem. My background is mortgage pricing. I spent 15 years as the CEO of Nomis Solutions building the pricing engine for a lot of the large mortgage lenders globally. I partnered up with Ben, who ran mortgages at SoFi, more recently ran operations at Divi Homes, and had built a portfolio of over 5,000 homes to bring the real estate expertise to the table. Allie joined us, she ran the Harvard Impact Fund, and then Sam, finance background from Homelight Unison Investment, entrepreneurial software engineering background to really tackle this problem. So what we're doing here is reimagining a journey into homeownership really by challenging some of the core assumptions that have been around for way too long. Structurally at the core, what we're doing is We're fractionalizing or tokenizing starter homes into 10,000 ownable shares, or bricks as we call them. And that fractional ownership really opens up a number of ways for first-time home buyers in particular to participate in real estate wealth creation while picking a home that they can make their own. We launched about 2 years ago. We started buying homes in the Triangle in North Carolina, so Raleigh, Durham, Cary. We expanded to Charlotte, we expanded to Nashville, Dallas. We're now looking at expanding into other markets. The early results are really encouraging. We're generating at the portfolio level a gross return of about 19% for our investors annualized. We're seeing 100% on-time payments, 4% vacancy, 100% occupancy. We see significantly below average, about 80% below industry maintenance costs on these homes because of the co-ownership mentality of our customers owning shares in the home and truly taking care of them as co-owners rather than tenants. And then obviously on the customer side, we're seeing equity and wealth accumulation. We're seeing a lower down payment, saving the average customer about $29,000 upfront, and we're saving them somewhere between $350 to $400 per month relative to where mortgage rates are today. Enabled is all of that by a very sophisticated AI-driven underwriting engine that really looks at two pieces here. One, the customers— we're qualifying about 2% of applicants into eligibility for the Ownify Home Fund. And then we're qualifying properties, and we're putting together very qualified first-time home buyers with great-looking starter homes to create these unique investment value propositions for our investors. As I mentioned, gross return 19% on an annual basis, 16% is our target return, and there are really 5 core levers here that I just wanna quickly run through. The first one is home price appreciation. Select markets, Selecting the right properties, buying them below market through aggressive cash offers gives us a much better shot. And so far what we've seen in the portfolio, about 5.6% unlevered home price appreciation on an annual basis compared to just shy of a point in the market as a whole. Now obviously we're going through a slowdown in home price appreciation and we see that as a buying opportunity as we scale up the portfolio. Second big lever is getting a better gross rental yield. And that is driven by really two underlying structures here. One, we give the customer the choice to pick a home off the MLS, go on Zillow, go on Redfin, find a home, buy that with us as their co-buyer. And that choice, right, and that flexibility, the broader choice of homes out there actually allows us to command a much better rental yield than that that you get to get out of an existing portfolio of rental homes. The second one is that we sign long-term lease agreements that have built-in rent escalation, and that ultimately gives us about 150 basis points of higher gross rental yield lowest taxes compared to the market as a whole. Second big driver is occupancy. Because we sign 5-year leases and because we turn the customer into a co-owner, there's really an incentive to not turn over, and we haven't seen turnover. So we've had 100% occupancy thus far since inception of the fund. Credit and risk underwriting basically means that we've had no delinquency. We've not had a single late payment in the portfolio. So again, driving at the margin better returns and cap rate enhancement that way. And then probably the biggest driver here of the structural co-alignment between our customers, the co-owners, and our investors is the notion that our customers are not just tenants, they're truly co-owners through this ownership of, of bricks or shares in the home. And as Warren Buffett famously said, no one ever washed a rental car. We're really seeing that. And what we're seeing is maintenance costs of about 14 basis points on the portfolio versus about 80 basis points market average. All of those things are coming together to ultimately drive better return for our investors. There's a couple of different ways in which you can become part of that journey. One, as a straight limited partner investment in the Ownify Home Fund. Again, that's a 16% target IRR, preferred returns between 8% and 10% depending on your investment size. And then obviously we're also always interested in talking to investors around JV structures, platform structures. We have a couple of those in the market where we're creating custom portfolios of co-owned homes and using this unique fractionalization structure we've built to ultimately enhance rental yield on portfolios and in markets that you might be interested in. If this is of interest, please contact me, Frank, at Ownify, or 415-549-1939 is my direct number. Here's a pretty picture of me. Again, more information on how to get in touch, and I look forward to talking to you. Thanks.