Frank Rhode, CEO of Ownify, explains how the company helps first-time buyers own homes by fractionalizing ownership into 10,000 shares they buy over time, then converting to a traditional mortgage after five years. The fund targets 16% net returns through home appreciation, rental yields, and zero delinquency. The team has bought over 5,000 homes and managed nearly $500 million in capital.
Chapters
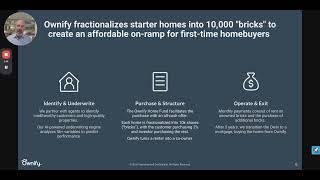
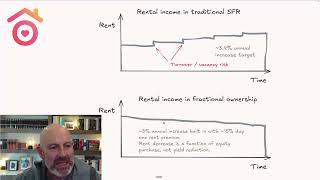
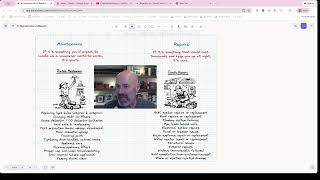
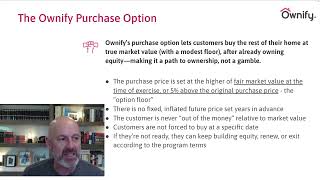
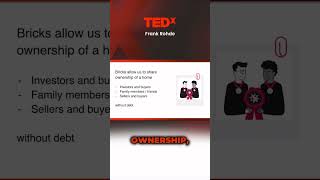
Hi there. Welcome to a quick overview of Ownify and the Ownify Home Fund. My name is Frank Rhode. I'm founder and CEO of Ownify, and I just want to take a couple of minutes to walk you through our core mission, uh, how you can participate as an investor, and what the potential returns might look like. Buying a home is the cornerstone of the American dream. Yet today it is harder for young people to buy their starter home than at any point in the last 50 years. Between rising home prices, mortgage rates that have reverted to their long-run average, student debt, down payment requirements, and competition with corporate buyers, it is harder than ever before, in particular for first-time home buyers. That is the core mission that we're solving. At Ownify, we partner savvy investors with qualified renters to make homeownership possible, and we do that through a very innovative and equity-based rather than a debt-based structure. I want to take you through how that works. Before I dive in, just a quick word on our background. We're a group of entrepreneurs, fintech founders, mortgage and real estate experts who've come together with a unique passion and goal of making ownership possible again. Between myself, Ben, Allie, and Sam, we've bought over 5,000 homes. We've managed almost half a billion dollars of investor capital, and we've built 3 companies. We're taking that experience and our collective background to really tackle this pernicious problem that we're seeing in the US today. The structure we've built is effectively a co-ownership arrangement or an equity-based fractional ownership arrangement between qualified first-time home buyers and a fund, the Ownify Home Fund, that enables accredited investors, high net worth, family office, institutional investors to put capital into a co-ownership structure designed around financing the starter home for qualified first-time buyers. This really works in 3 steps. The first step is that we underwrite and qualify first-time home buyers. So renters who are middle income, have good credit, and are looking to buy their starter home. Generally homes in the $250,000 to $500,000, maybe $600,000 range. We use technology to underwrite both the customer and potential homes that they're qualified to buy. Once we've underwritten the customer, and the customer picks a home in conjunction with an accredited agent, we purchase those homes and place them into a unique structure. We effectively fractionalize the ownership into 10,000 bricks or shares that the customer now buys over time. And as soon as we buy a home, we place this home into this— at the end of 5 years with 10%, we move the customer into a mortgage. So the right way to think about Ownify is really, it's an on-ramp to homeownership that splits the journey between renting and owning into a fractional ownership arrangement. And by virtue of doing that, we can reduce the down payment, we can reduce the monthly payment, we can make it more attainable for first-time homebuyers to get into ownership. Now, we do this by partnering qualified renters, qualified first-time buyers with investors, which means there is an investor value proposition, and the investor value proposition is really investing in a portfolio of curated single-family homes that are co-owned by the owners, the tenant buyers that are building equity over time. And so far, we've been doing this for about 3 years, and the trailing 12 months returns are about just shy of 20% IRR. So well ahead of our target of 16% net return to our investors. Then set a journey, blah, blah, blah, blah, blah. The first investor advantage lever here is home price appreciation, and we've built an AI-driven underwriting engine that allows us to pick micro markets and underwrite individual homes based on their appreciation potential. The first component of our return to investors is home price appreciation, and we achieve home price appreciation by being very diligent in selecting and underwriting individual homes for their underlying quality and their appreciation potential. We've built an underwriting engine that uses a large amount of data, but we supplant that with market knowledge and in working with local realtors. So far, our results speak for themselves in that our unlevered portfolio appreciation is 5.6% annually versus a market average of about a point. The second lever that generates investor alpha is top-of-market rental yield. We're getting stronger rental yields than the average home because we're giving the customer the choice of homes in the market. The third lever here is occupancy. Because we're structuring long-term leases and the customer's a co-owner with the stated intention of buying the home over time, we've never had a day of vacancy. We don't buy homes until the customer has chosen the home, until the customer has signed the contract. And so we have 100% occupancy since the inception of the fund. And again, ultimately that translates into higher cap rates to the investor. At the same time, we've seen zero delinquency. We've not had a single late payment in the portfolio compared to about a 0.7, 70 bps average in the market. And probably the biggest change in behavior and the biggest driver of yield is this notion that we're turning the customer from a tenant into an owner. And that change in mindset, that change in mentality really reflects well in the underlying OpEx, the operating expenses, specifically maintenance and repair costs that we've seen in the portfolio. Warren Buffett supposedly said, "No one ever washed a rental car." It's really true. We're seeing with customers who are owners and co-owners is they take better care of the properties, and ultimately that results in lower OpEx and better yield to the investors. So all of that comes together in a run rate return on the portfolio of just shy of 20%, well ahead of our 16% net IRR target for our investors. So if you're interested in learning more, please review the detailed private placement memorandum, the data room, you can schedule time with us. And there are really two ways to engage with Ownify. One, as an investor in the fund across a curated set of homes in a number of different high-growth markets. And two, to the extent that you want to use the platform to build your own portfolio of homes, we're interested. Thank you for listening, and I look forward to meeting you soon.