Ranking The Best & Worst Types Of Insurance To Sell In 2025
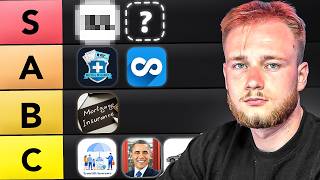
YouTube video (by Timothy Schucker) that ranks insurance product types to sell in 2025 using an S→D tier framework. The speaker assigns tiers and explains why for each product (term, mortgage protection, PNC/personal lines, Medicare, ACA/Obamacare, infinite banking/whole life, IULs, annuities, final expense), emphasizing market demand, commoditization, compliance burden, renewals potential, and earnings anecdotes.
Chapters
So what is the best type of insurance to sell in 2025? On this video I'm going to be ranking on a tier list what the best opportunities in the insurance industry are today. So let's dive in. Alright, so for anyone who is unfamiliar on how these videos work, S tier is the best tier. So this is like the, the best type of insurance or the best opportunity. Then you go A, B, C and then D is the worst or lowest tier tier. So we're going to start off here. We'll start with term insurance. All right. Now term insurance, I'm going to put this one into.
I'll put this one into B tier. Okay. Now the reason I put term insurance into B tier is like it's really a broad product that can be sold to a lot of different people. So term insurance by itself is not necessarily a bad opportunity. The biggest issue or problem with term is the fact that it's very commoditized. So when people are buying term insurance, like just to get protection, like, you know, to cover their income if they die, usually they're trying to pay as little as possible for the most amount of coverage as possible. Right. That's essentially like what they're looking to do. They're trying to save as much money as humanly possible. It's usually not really a value game. This is why you'll see these companies that will advertise, you know, term policies for as little as a dollar a day. Right.
Things like that. Right. So that's kind of the issue that I've seen with term is it's just one of those things where people don't really value it that much and it doesn't really have anything that's super unique. And if somebody wants a term policy, why couldn't they just buy it from like an AI or buy it through ethos or something? Like there's nothing that makes term really special unless you're doing like return a premium, which, I mean that can make it a little better. That's why I put it in B tier is because there are some things you can do like if you do term with living benefits or something like that, but in general just a very commoditized product, the commissions are not that great and people don't really like value it a ton. All right, so in that same line of term, I'm going to put mortgage protection. I'll put it in B tier for now. I might move this up to A tier later. Well, actually no, I'm gonna leave it in B tier and I'LL explain why. I'm gonna actually, I'm gonna put mortgage protection here. I'm gonna drop term down to C tier. So the reason I put mortgage protection in B tier is, like, when mortgage protection is hot, it's hot, right? But when it's cold, it's really cold. So it's one of those products that's like, it's either.
Everyone wants it and people really care about it, and agents are making tons of money with it. Well, what just happened? All right, Everything had glitched out for a second, but we're back, baby. So in B tier, I'm putting mortgage protection. The reason why is, again, when this product is hot and when houses are flying off the shelves, people are buying houses all the time. You can actually make a lot of money with this. It's got kind of the same thing with term to some extent, where I will say this. Mortgage protection is one of those products that is 100% sold to, not bought. Like, if somebody wasn't calling people up and selling it, people would not be buying. And the reason why is a lot of times, like, the whole sales pitch is you pretend like you're from their mortgage company, which, personally, I've never done that or been a part of that. But that's, like, what most people in the industry do. So I put it in B tier because, I mean, I know a guy who does 100 grand a month on his own pen, just a mortgage, so you can make good money with it, but it's not, like, the best opportunity, and it's not really evergreen. All right, so let's look at another one. We're going to take PNC insurance, okay? And I'm going to put this one in C tier. And the reason why is I know a lot of broke PNC guys, and I know a lot of wealthy PNC guys. So it's one of those things where, like, it really just depends. The biggest downside that I see with PNC is you're really beholden to whatever companies you represent, and, like, all of your clients always will hate you. All right, like, when have you ever been happy about your car insurance? The price always goes up anytime you use it. They just absolutely shaft you, even if you just put in a claim and don't even use the money. Like, I remember a couple years ago, I called my car insurance company, and because I had, like, a rock that hit my windshield, and I didn't even end up, like, using any of their money, but just because I called them, they jacked my. Right, my Price up. So you're just always going to get cussed out and yelled at by your customers. And it's not, it's, it's a, it's a very commoditized product. The pros are, everyone is forced to have it. So that's really good. The customer base is extremely wide, but you usually have to pay upfront. You have to pay a franchise fee to even be able to sell this product. And the commissions upfront are pretty meh. But over time, like if you stack up a big PNC book, like you can make really, really good money. And some of the wealthiest guys I know are selling these products that have renewals like PNC or Medicare. Which brings us to our next one, Medicare. I'm actually going to put in a tier with the potential for this one to go up to S tier. All right. Now Medicare is one of these products that is absolutely incredible. Okay. There's a lot of downsides which I'll get to in just a second. But the upsides is you want to sell products that play into large market trends. So right now with everything that's going on in the retirement market and with baby boomers, like having a Medicare license and being able to help people and build up like a solid renewal base is just such a great opportunity with the amount of people turning 65. And you know, I've, I've met people that have sold Medicare books for tens of millions of dollars. Like multiple people that I've met that have done that. It's a common thing that happens when you build up a book that has this renewal base. Like private equity is buying up these books. And even just as an individual agent, you know, if you just stick in the game for long enough and you build up a health insurance book like you can easily make six figures multi six figures a year. Just some renewals. The downsides, well one, the compliance is an absolute slog fest. Like every single year you got to do a hip and then you got to do the certifications for every single individual carrier. Like from an agent perspective, it's just such a pain in the ass. And you got to do the scopes of appointments and this. It's just like every year they're like drowning people in compliance which depending on who you are. For me personally, I hate, hate, hate dealing with like compliance stuff so much. That just makes my life a living hell. So I'm not like personally I don't do any advertising for Medicare. I try to stay away from it. But as from a business model perspective, if you could like not have to worry about the compliance. As an individual, I think this is a great business opportunity. But just because of the compliance and then also like it is so saturated it's insane. And you got these call centers that just call and try to switch people and there's so much crap that goes on. That's the only reason it's not at S tier, but it's one of the best money making opportunities in the industry and got a lot of people into the industry. Next up, I'm going to put Obamacare or ACA under C tier.
I actually don't know too much about this, but from my understanding it was like really hot for a couple years. And then every time that there's like a conservative president, everyone's scared it's gonna go away. And from what I've heard from talking to a few people that are super, super deep in the weeds on ACA right now, it's not great. But when it was on, I mean I knew people that were making millions of dollars a year from doing it. But it's another one of those things like Medicare where like it was such a good opportunity that the wrong people got into it. Like shady people get into it and they ruined the opportunity for everyone. So I'll leave it in C tier for now. We're gonna look next. That infinite banking, which is this one here, I'm gonna put this under A tier. Okay. The cool thing about this is like for the right person, for example, like myself, I know a lot of business owners. Like in my individual like my daily life, I'm in masterminds with business owners. I talk to a lot of people that invest in real estate. And so like I'm learning a lot about this type of product, the infinite banking, like using whole life to, you know, basically supplement your portfolio and have like that stable foundation of your investments. And the cool thing is like as you start to make more money.
This product allows you to work with really high level cool people. Because the product itself, like the philosophy behind why you would use this is just incredible. And it makes tons of sense. Like Alex Hormozi uses it, a lot of banks use it. Business owners. I'm pretty sure Ray Kroc used infinite banking with a whole life policy to like grow McDonald's. I think Walt Den's Disney used it as well. Like it's a really cool tool for business owners to be more tax advantaged and just have a stable base for their money. So the reason I put this in A tier, you can make really good money with it. You can sell massive policies. And, like, the renewals are good, too, on whole life insurance. So that's really cool. The only downside, I will say, is, like, it's a little more complex and. And you really need to be dialed in with your marketing to be able to sell these consistently. And it's also one of those things where, like, you really have to understand it. Like, there's a lot of moving pieces with that product. All right, so that's why it's going to go into A tier now. S tier. I'm going to put Iuls in S tier right now. And this is not going to be like an IUL versus Whole Life video, like IUL versus, you know, cash value Whole Life for doing all that. The reason I put IUL and S tier right now is for the sole reason that it's a really hot product and people want to put a lot of money into it. So what we've seen is, you know, I've seen clients sell 25, 30, $48,000 AP IUL policies, and it's just one of these products that, like, there's a term in fishing where, like, the fish are jumping in the boat. That's kind of what's going on with iul. And I think the reason why is, like, so many people are advertising it that, like, the collective consciousness of the US Is just becoming more aware of this product and people want to know more about it. Like, if you go to the gym and you sell life insurance and people ask you what you do and you tell them you sell life insurance, they'll probably ask you about the iul. Right? Again, not saying it's, like, the best product out there. Not saying it's the worst product out there. I'm just saying, as of right now, the opportunity for that product is extremely hot. Okay. From what I've seen, I would put annuities in the same realm here. To be honest.
I would put annuities in S tier as well. And the reason why is annuities are one of those products where, like, you can make so much money up front. I know at least three people that are making three, three or four million dollars a year net personal income just on their own pen, which is amazing, Right? And they're doing that through selling annuities. The cool thing you could do is, like, you could sell IUL's annuities and then also have, like, the Medicare piece in your. In your. In your toolbox. And then the annuities basically give you that nice upfront cash. And then the Medicare builds your renewals, which is really cool. So annuities is one of those products like where you're playing into these big market forces of the retirement boom. Right now there's 11,400 baby boomers turning 65 every day, which means there's so much qualified money that can be moved and they don't charge back. Like, there's no chargebacks with annuities. Once the money is moved, there's like, I think it depends on the carrier, but there's a set amount of time for like a rescission or like to revoke or get rid of the contract. And then once that's locked in, you can't get a charge back on the annuities. And you know, you sell a few of these a year, you can make six figures. You sell a ton of them a year, you can make seven or multi seven figures. Not saying you will do that. I'm not making an income claim, but some people I met literally met and know people that do. So it's 1000% possible. So I put annuities in S tier. Now the last product we have here is final expense. Now let me say the pros of final expense before I go into the mini cons. This is how I got my start. This channel, this exact YouTube channel, we used to talk a lot about final expense. And after just repeatedly learning the same lesson over and over and over again, but for whatever reason, not wanting to actually learn it, I just kept doing it and kept marketing for it and everything. And I was in the industry for too long. I will say the good things about it. It's extremely simple. You get paid extremely fast and there's such a need for it and such a demand. Okay? So like, and you don't have to be good at sales to do it. So that's four reasons, four things that are good about it. The cons of it is because there's. It's so easy to sell. The competition is just super immense. There's so many people that are trying to sell this and you're selling to a demographic of broke seniors that are because of Medicare, ACA and all. I'm sure there's something else that they get targeted with. This section of the population of like seniors that are on Social Security is over the top, marketed to like, their phone is always blowing up. They'll literally tell you they get like 40 spam calls a day, which they do.
And the other thing too is like, they, they're just like, they're very Frustrated. And a lot of times they're not, they don't want to talk to you. If you're helping someone position more of their money in retirement and protect it and you're talking to someone that like, has had a, an extensive career and is a successful white collar professional, like with Iuls annuities and you know, even infinite banking and some, in some cases Medicare, like, they're excited to talk to you and they value your expertise as a professional, whereas in general, like with final Expense, you're just an annoying telemarketer and they don't value you. And you know, I'm not saying every single person, but just in general, like most people's experience selling in that market. And the other thing too is if you sell to people that don't really have money and you're, you have to, they have to pay their bill for 12 months and in some cases even up to two years. Like you are basing your business on a foundation of sand. Because when you base your entire finances on people that don't have money to pay a bill consistently.
There most people most of the time, like oftentimes not most, but a lot of the time they don't pay the bill consistently. And so you end up just on this constant hamster wheel of chasing chargebacks and your quality of life and your day to day usually ends up looking like you just making dials all day long. And in the past we did marketing for this product and we were able to get people appointments, but then it's like the appointments don't show and it's like you get people leads and oftentimes they're like, they're qualified quality leads but they just never pick up the phone. And so from selling the product personally and through an agency, we scaled it to over $100,000 a month in 85 days. And then also marketing for that product for like a couple years, I've just seen the ins and outs of it. And it's one of those things where if you're brand new to the industry and you want to get a start on it, I mean it's an okay place to start, but if you start there, you need to have a, you need, need, need, need, must you like, you must have an exit plan, you must have a thing that you're going to go to next because you will get trapped in here. And this is why I think so many agents fail is because they get recruited to that side of the business. So that's my opinion. Let me know if you agree or disagree. With me in the comments down below and I'll see you in the next one.










