Tim Bell explains "buy and hold" funding for rental properties, contrasting it with earlier-covered funding types (traditional owner-occupied loans, hard money, private lenders). He focuses on commercial banks and lenders (e.g., PNC, Chase, Wells Fargo, Bank of America, US Bank) that will fund non-owner-occupied rental properties, describing qualification criteria (income, FICO, employment, rental history), typical loan terms (3, 5, 7, or 10-year terms amortized over 30 years with a balloon payment due at term end), interest and fees (typically 5–15% interest, possible points and additional fees), down payment expectations (typically ~20%, usually not borrowed), and underwriting practices (crediting ~70% of property income toward qualification, first lien requirement, and relative foreclosure reluctance compared to hard-money/private lenders).
Chapters
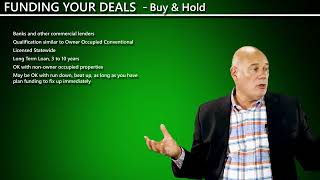
Okay, so now we get down to the last category of funding that we need to talk about and that is buy and hold funding. This is funding for your rental properties and that's what we're going to talk about now. Now we started out earlier talking about traditional long term owner occupied lenders, banks, bank of America, Wells Fargo, PNC Mortgage, Chase Bank, US bank, all those folks that provide traditional long term owner occupied loans on pretty houses. We said of course that those folks will not loan money in your fix and flips. Then we moved over here to the hard money lenders which indeed will loan money on your fix and flips. That's their niche, that's what they do. Okay, Then we moved kind of to the middle towards private lenders. Now we're all the way back over here. Now we're talking about traditional banks and commercial lenders. PNC Mortgage, Chase Bank, Wells Fargo, usa, US bank, bank of America, people like that. That's who we're back to talking about. Now they do loan money not only on owner occupied properties, but they will loan money on non owner occupied properties too. Rental properties too. Okay, that's what we're talking about. Now these folks are banks and other commercial lenders. Again, like we've talked about over here, qualification on buy and hold rental property loans is similar to non or to the owner occupied conventional. In other words, these folks once again are going to ask you for your income and your FICO score and your time on the job and your rental history and all that stuff. Your iq, your shoe size, your blood type, all that stuff. They're going to want to know all that stuff about you again. Okay, they are licensed statewide and so that means you can do business with anybody anywhere in your state. They provide long term loans 3 to 10 years. Now you might say, wait a minute Tim, I have a 30 year fixed rate mortgage on my house and you're telling me that three to 10 years is long term in these types of loans? Yes, it is. Okay. In these types of loans they typically loan money for three, five, seven or 10 years. Now at the end of that three, five, seven or 10 Years, you're going to owe the whole balance on the loan. Okay? Now basically what they do in order to make the payments affordable and in order to give you a positive, more likely chance of having a positive cash flow on your property, they're going to amortize the loan as though you were going to pay on it for 30 years, but you're going to pay it back in three to five to 10 to seven to 10 years. Okay? Which means that you're going to make payments as though you were going to pay for 30 years. And then at the end of the, say the five years or 10 years or whatever, there's going to be something called a balloon payment due. The balloon payment means the whole balance comes due to. Now that might sound a little bit scary, but it's really not that big a problem as long as the value of your property has gone up. And remember we talked about, the value of your property is based on the relationship between the net operating income and the capitalization rate. So if you're a good landlord and you've raised the rents and you've maintained your expenses and done the things you're supposed to do in managing that property, it won't be a problem for the balloon to become due because your property will be worth a lot more money at that point. Point. And then you can refinance and go up for another three, five, seven or 10 years with that lender. Okay? Now they're okay with non owner occupied properties. Again, that's what they're focusing on in that portion of their business. They may be okay with rundown, beat up, nasty, ugly and stinky as long as you have a plan to fix it up and you have the funding available to fix it up. If you don't have a plan and funding, they won't loan you money. Now if you don't have a plan and funding, here's an alternative. Go back over to these folks over here, the hard money lender. Hard money lenders loan short term. They loan on nasty, ugly, rundown, beat up and stinky and non owner occupied. So you borrow money from them. You get the property all fixed up. Now it's all pretty and appraisal. Then you go back over to these folks and say, I have a pretty appraisal property and I'd like to do, I'd like to borrow money on it. And so they will loan you the money and, and you can use that money to flush out the hard money lender. Now you have your rental property, so that's another good choice that you could have there. Typically they're going to charge you somewhere between 5 and 15% interest. Usually simple annualized interest is the case. They also may or may not ask you for points up front. Many of them do. The points that they collect are not for, for the purpose of foreclosing on you, but to amortize some of their costs, possibly if they have to borrow the money from the secondary market or something. Like that they may try to buy the rate down or something like that. But in many cases there are points in those types of loans, as it says here, there will be additional fees. Plus plus plus this is the most expensive loan you can get. Okay? There are often additional fees that are, that are charged to you for this type of loan. You need to be aware of that. Typically they require about a 20% down payment and typically they don't want it to be borrowed. Okay? Now this is a place where the lines between borrowed and not borrowed can blur a little bit. For example, let's say you have a partner that's bringing the 20% down payment, you're bringing in the property and the partnership owns the property when you purchase it. Okay? Technically, that 20% down payment that the partner brought in is not borrowed money. From the purchase perspective of the lender, they will require monthly payments. They always do. That's just how they are. The approval is based on your credit and your income plus the income from the property. Most lenders will loan you about 70% or rather they'll give you credit towards 70% of the income but potential for that property. Now, in some cases you're going to have to document that income. You're going to have to show former leases or rental history or profit and loss statements from the place or whatever. But if you can document income from that property, they usually will give you credit for about 70% of that income toward your qualification for that property. So your income will be supplemented by the potential income from the property in qualifying. So that's good news. Follow their checklists, fill out their forms, jump through the hoops. There will be more hoops, okay? This is the most complicated, expensive kind of loan you can get. There'll be more paperwork. There just will be. Just have to plan on it, okay? Now these folks will insist on a first lien position, period. They will not allow you to have to give them or allow themselves to be in a second, third, fourth lien position. They must be in a first lien position, okay? And then finally, these folks are reluctant to foreclose on you if you don't perform. They will if necessary, but they, but they're typically more flexible. Remember, we've got the hard money lender that's excited to foreclose on you. We've got a private lender like your mother or your dentist who would never foreclose on you. The buy and hold bank lender is somewhere in between the hard money lender and the private lender in terms of their desire to foreclose or their reluctance to foreclose. Okay. That's where they fall. Okay, so that's. That's buy and hold lending for your rental properties. Again, great sources. You can use private lenders for buying for buy and hold also. But often people will use these commercial banks and other commercial lenders for their buy and hold rental properties.