Tim Bell explains seller financing: the seller deeds the house to a buyer who pays in installments, like $2,000 a month for 30 years instead of $300,000 upfront. Sellers benefit from reduced responsibility, favorable tax treatment, and potentially higher total returns.
Chapters
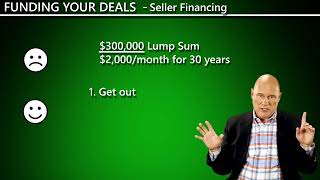
Okay. All right, the next item on here, seller financing. Now, I'm going to show you a diagram in which the discusses how seller financing works, and we'll go through that diagram. Basically, with that diagram, you can see we've got a seller that needs to sell their house, and that seller is then going to deed their house to me. Remember, with. With houses, it's different than cars and other personal property that you have. For example, if you borrow money on a car and you borrow it from a lending institution like a bank or a credit union or whatever, who holds the title to that car during the time that you're making those payments? And the answer is the lending institution does. And then once you pay it off, then they issue you a new title called the lien release title, where it had no longer has a lien on the proper or on the car, and then it becomes your car. You have the title to it. Houses don't work that way. With houses, the title, the ownership of that property can transfer independent of any liens, loans or other encumbrances that are out there on the property. It can transfer. Okay, so step number one, we're going to find a seller that needs to sell their house. Step number two, they're going to deed us their house. In return for deeding us their house, we're going to offer to pay them the money for their house. Let's say, for example, as we can see in our diagram here, that we agree to pay them $300,000 for the house. Okay, so they agree to take 300,000, but we're not going to pay them $300,000 in a lump sum. We're going to pay them $2,000 a month for 30 years instead of 300,000 in lump sum. That is our agreement with them. And those are the terms under which they're going to deduce their house. So we're converting them from being a homeowner to, to being the bank. They're essentially loaning us their equity in the house. Now, here's a question. Why would they do that? Well, number one reason, they really don't want the responsibility for the house anymore. They don't want to take care of it. They've got to move. Maybe they got a job transfer, maybe they get a divorce or whatever they need to get out of that house. That's one reason. Another reason, if I give them the entire $300,000 lump sum, there will be tax consequences for them receiving that $300,000 sum. If I give them what's what the IRS calls installment payments, in other words, $2,000 a month. As you can see on our diagram here, $2,000 a month for 360 months instead of 300,000 a lump sum. They have a favorable tax treatment that that $2,000 a month is treated as an installment sale instead of a lump sum, which means typically they're going to pay less taxes on it. Again, you can talk with your CPA about how that works if you need more details. What's another reason why a seller might consider doing this? Well, if you add it up, 360 payments of $2,000 a month, how much is that? That's about $700,000, $720,000. That's a lot more than 300,000. So you're paying more than twice as much for the house if indeed you pay for it over that 30 year period. Yeah, that's another reason why a seller might be willing to do it. So that's basically how seller financing works. As you can see from our diagram here, the seller decides and agrees to take payments instead of receiving their money in a lump sum. That's the essence of seller financing. Okay. Now there are lots of other convolutions and there are lots of other different combinations and things with seller financing. But that's the basic concept, the basic premise of how seller financing works. We're converting the seller from being the owner of the property and having responsibility for the ownership to being the bank. They're receiving a check from us on a regular basis instead of having to maintain and work with the property too and make those payments. So that can be very helpful. That's seller financing.