Module 10 Note Investment Mentoring [1/10]
Coach G wraps up a course on buying non-performing junior liens, condensing three years of practitioner work. Real deals show the margins: a San Gabriel second lien of $102k bought for $14,267; a Las Vegas second of $33k for under $5,000. The niche is time-limited, Coach G says, worth a few years of focus.
Chapters
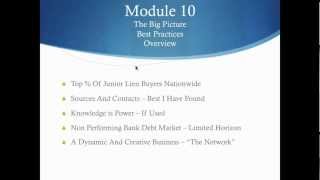
Foreigning everyone, this is Gordon module 10. Let me talk about this for a minute. This course has taken me a culmination of three years. Thousands of hours of hours and dollars over a hundred hours of just invested in this program, distilled down to about 20 hours of the best and current summary of how to make money today in this specific non performing junior lean niche. Not philosophy, not strategy, but a step by step process on how to make money. Now my goal tonight is this. I want to kind of wrap it all together. I want to go through the first nine modules and kind of pick out the best practices, tie it all together and give you a general overview of what's out there. And then at the end we're going to have one of our students, Scott White, talk about three of his deals. So instead of my deals, as we talked about for the last nine weeks, we're going to have Scott, who's been a student for about five months now, talk about his specific opportunities and how he's done. So I think you'll be really impressed with that. With that. Let me go ahead and get started. Go ahead and get started here. Okay. What the people that will finish this course will have, they in my opinion, will be among the top percentage of junior lien buyers nationwide. Don't take it for granted that everybody will know what you know. The top hedge fund managers out there don't know what you know, don't have the perspective that you will have on issues like the workout process. A lot of them don't do it or do it certain ways, things like emotional equity. And we're going to go into that a minute, in a minute. But you, in my opinion, will be at my level, which is a small and elite group of people that do this business. And I just want to, you know, put that out in front here saying don't take this for granted, that you've really got a unique skill here. And what I've done, as I said before, this is not theory, this is not strategy, this is it, this is what I do. And I've been very transparent. I brought on my sources, my contacts, the best that I found in the business over the last three years. And I brought many of them on the calls. So just to kind of give you a summary of it, we've had Dave Van Horn, who's the president of Partners and Payment Relief, a major hedge fund. We've had Bill McCafferty who is a workout specialist, focusing just on junior leans. Michelle Gadotti, who is a bankruptcy attorney, focuses just on that she gave us a specific overview of the junior lean business. Steve Gryglowski, who's a workout pro, he works at a bank on the east coast, he is an expert in forbearance agreements, etc. We had trustee Corps, we had Rand Johnson and Matt Kelly on that gave us a complete overview of the foreclosure process. They are my foreclosure guys. David Phelps, who's a genius in the note business and a great guy, he gave us a perspective on his perspective of this business and creating a more valuable note. We had Melissa Bollings from Advanced Workout Specialist in Seattle. Advanced Concepts, I think it's called Allied, excuse me, Allied Concepts, that's the name of our company. And so just an idea of the people that we've had on this call. These are the top of the top, the best people out there. And you right now, from hearing them, hearing their perspective, you've got knowledge. So as they always say, knowledge is power if you use it. This non performing bank debt market in my opinion is limited. We've got a huge glut of it right now. Will it last forever? No, I think we have a two or three year window. It's starting to come out right now. I heard an interesting statistic the other week. Someone said that of all these bad assets out there, 90% of them are going to come out of the system through a note as opposed to reo, as opposed to other avenues. So this is a skill that's very relevant right now, but it's limited. So I also want to make a point that this is a dynamic and creative business and the network that you'll create in your own business and is a key part of it. I'm going to talk at the end of our presentation tonight. What I plan to do is on the 26th, which is two weeks from tonight, is have a little mock coaching call to kind of talk about the workouts and how to do that. Because that's the real fun and creative part of this business. As I've said before, it's not a cookie cutter. One size fits all. Once you get it figured out now, it's kind of boring. It's not that way at all. It's always something different. It's always. There's so many different dynamic and creative things you can do in this business. It makes it fun. It's frankly the part that I like about this business. So this module 10 tonight, big picture best practices overview. I'm gonna run through the last nine modules at a relatively quick pace. I'M not gonna go into the detail of it. It's more of the what as opposed to the how. The how we've gone into in detail. You know, we've analyzed things like credit reports and every other little detail that we could go through. Tonight's kind of, kind of a big picture strategy. Several of you have come to me and said, you know, I wish you could kind of wrap it all up, put it all together for me. And that's what we're going to do tonight. So here we go. Module one focused on why notes, why now? And I told you my personal story, the path to the non performing junior lean. I'm historically a real estate guy, got into this business three years ago as I've said. Why junior liens, why seconds might come first. As I mentioned in my story about New York, I went there as a first lien buyer and was turned into a second lien buyer. As I'll go through the process of this first nine modules, you'll kind of see my progression. But I talk about things like what if your biggest fear wasn't? And the biggest fears that I focus on. Bankruptcy, foreclosure. We handled those in detail in this program. I had Rand Johnson and Matt Kelly from Trustee Corp. They're my foreclosure guys. They're the best in the business in my opinion. And they gave you keen insight to say, okay, if I knew all these things, it's not that much to fear. Everybody wants a gold plated note, but what if you brought a broken note for a fraction of the price and fixed it, not fearing the foreclosure process, not fearing the bankruptcy process. We had Michelle Goddardi, who's a top attorney in the bankruptcy arena, talking just about the junior lien. So I'll get more into that later. Junior lien is a virtual option. And that's really my push of this is to say make small bets and take an option position. If you can pay a couple three or $4,000 for a position in a deal as opposed to paying, you know, 10 times that amount or 100 times that amount by buying the property or buying the whole note or buying a first. It's why I'm drawn to the junior liens. A market overview. We talked about that. I've got four hedge funds which I'll identify in a minute and kind of this one hedge fund, Keyhole Financial, which I listed earlier in our call in detail, has a great story of four or five different funds that they've done and the return they've got so it's not just me saying, well, here's my notes, but them saying, here's their notes, an analysis of the key players. And then in that module one, we took it down to the basic paperwork level and a collateral file. What should a file look like? What you know is an assignment and a launch, all the different things you should find in your file or not and know they're not there, know what to look for. So we kind of talked about a lot of high level stuff in module one, but also the details. Let's talk about a quick market overview. You know there are $600 billion in second liens and what we're looking for is that 6 billion that are of a certain criteria in default behind a current performing first lien. This is our target market and we think we've got a couple years of this. This will not last. You know, they'll always be junior liens. Whenever somebody's got the house and bought a pool and got a loan to do it secured by their home. That's happened since the beginning of time. But the glut right now of these loans is what makes this market condition what it is right now. It's why you can buy these loans so cheap and where the opportunity is. I don't see it lasting more than a couple of years. I could be wrong sometimes I am your biggest fear in this business. And I think what keeps most people away are foreclosure, bankruptcy, taking a property from second position. Now you own that property, subject to the first lien. Scary stuff. But once again, the power of specialized knowledge. I tell a story about a friend of mine who became an expert in judgments. And by doing that, he knew more than anybody else and he would get into deals without putting any money in himself. Just because he could go to somebody with a judgment that wasn't performing and say, hey, I'll take half the deal if I can get you that money for your judgment. Being an expert in judgments, put him into big deals like that with no downside, with no money himself. So specialized knowledge, which is what you've got here on junior liens and related things, that in my opinion is how to be successful in any market. Avoid the herd, learn something specialized, master it. Let's talk about four players in the non performing junior lean national marketplace. Dream Builders out of New York, 30 Wall Street. Peter Andrews started that company, I think about 10 years ago and they have been one of the forefathers of this whole business lately. And they're a big firm. A lot of the people That I know started with Peter Andrews, started as a passive investor, learned the business from him. He did a training class in 0405-0607 and Peter is kind of one of the main guys that got this whole non performing junior league kicked off the ground lately. Partners in payment relief. My friends in Pennsylvania, we had Dave Van Horn, the president come in and talk about it. He gave an amazing perspective about his evolution from buying only equity deals to non equity deals and actually finding that those ones were more profitable. That's a key point in this whole business. And you need to. It's one of the reasons I built this course was people that want to buy notes and they're saying why would I ever buy a note that was underwater? Well guess what if we could show you statistics that show that most of those perform because of emotional equity. That is an epiphany for most people. And it took me a while and Dave a while frankly to get there. Keystone Financial they, you should Google them. Keystone Financial and I went through it in detail, showed you their five or six funds over the last three or four years and the results that they got. They've got a very transparent website and we went through it in detail just to kind of give you a picture of the market. Coast Capital is a local California company that's focused just on the seconds. I work with them a lot. The basic paperwork I touched on that about how to do the process. A non compete, non disclosure ncnd, a purchase and sale agreement, a RESPA letter, Real Estate Settlement Procedures Act Attila letter, that's a federal letter. All these things you need to be aware of, you need to know. I didn't really understand these things. I had had real estate for 25 years but never really done the note business. You need to become competent in this. And we went through it in detail in the files. And a launch, which is basically an endorsement, an assignment which is how you take ownership. A mortgage or a deed of trust. You know the country is cut up basically into 50, 50 between mortgage states and deed of trust states. We talked about that in detail. I prefer if I can deed of trust states because I can foreclose immediately in a mortgage state. I have to go ask a judge for permission. So I'll buy anywhere but just you need to know the difference. And the note itself. Credit reports. We went through credit reports in detail and on a junior lien. You really need to understand that and how unique that is. We base a lot on the credit report on the borrower. We make a bet based on his credit report. We study it in a lot of different ways. We went through that forbearance agreements. Once you've got the borrower working with you, how does the agreement look? You want to be able to foreclose if things don't go well in the future. We had Steve Greglowski come on and talk about forbearance agreements in detail. It's something that's part of this business and you need to understand it. So we talked about the basic paperwork that was kind of module one, two real deals. Every module we went through two real deals and this first one and I'll just kind of skim over these because what we did was as you know, we went through kind of the banter back and forth between myself and the borrower how I work this out. But in San Gabriel, California it was a payment plan which is how most of these work out. The fair market value is the first figure, 384,000. The first lien 313,000 and the second non performing second for 102,000, which is what I bought. I paid $14,267 for that non performing junior lien. It was on a quality single family house. Owner occupied. The wake up in the workout. A notice of default was filed. Customer contacted. The result, $1,000 a month for I think it was 30 years. So that's a good one. We also got $3,000 up front from the borrower for the arrears. I'm just going to skim through these because we've gone through this but I just wanted to kind of give you an overview. Another one, a trustee sale purchase in Las Vegas, Nevada. The fair market value $95,000. The first 82,000. The non performing junior lien which I bought $33,000. I bought it for just under $5,000. It was a single family house. It was tenant occupied. The owner, the borrower would not respond. So we actually foreclosed on the property at the trustee sale. Someone bought this note for $43,000 payoff at the sale. So that was a good one. We made almost 10 times the amount of our investment there. A unique situation.