Module 10 Note Investment Mentoring [2/10]
Coach G walks through how he built a note-investing business by developing relationships with mortgage bankers and servicers, then analyzing borrower credit and property value. He shows two deals: a Sacramento junior lien he restructured to $398/month, and a Las Vegas note he bought for $3,300 and sold for $20,000.
Questions this video answers
$398.07 per month for 33 years.
Fair market value $428,000; first lien $218,000; purchased non-performing junior lien $105,000.
Fair market value $220,000; first lien $170,000; junior lien $22,000; purchased for just under $3,300; later collected just under $20,000.
Chapters
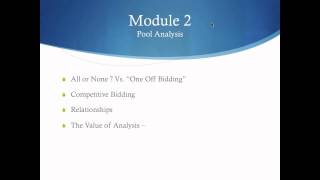
Module 2, finding and analyzing the notes. This was a new thing for me and you know, buying a note was a new proposition for me. I bought real estate where you had an escrow, things like that. Notes weren't like that. Notes were a deal where I would give them my money on a purchase and sale agreement and wait and wait. And I said, you know, I'm going to need a pretty good relationship with these people because I really don't like the way this deal works. So I better know them and trust them and know where to find them if things don't go so well. But I traveled all over the country going to mortgage banker meetings, servicer meetings, distressed debt meetings to find the people in this specific niche. We talked about analyzing the notes, note analysis and it's really frankly about the borrower. I always say that, you know, with real estate it's location, location, location. With first trust deeds, it's collateral, collateral, collateral because for the most part you'll be foreclosing on that collateral with a second. It's about the borrower. It's borrower, borrower, borrower. And you need to, you know, understand that process and understand how to analyze a credit report, which we went through in detail. Emotional equity. We need to keep this in mind. What we're focusing on here is single family houses mostly, but owner occupied people's homes, they have an emotional attachment to their home. So you would think that somebody with an upside down deal where they've got no equity in their property, their house is underwater, why would they pay you? Why would you buy that note? Why would you take a chance? Well, we went through that in detail and we had several experts come on and talk about it and confirm the fact that I've got confirmed also that people want to stay in their home. It's not an investment for them, it's their home. They have an emotional attachment. And, and you need to understand that concept to really understand this business pool analysis. You'll buy one note, you'll buy two notes or you'll buy a small pool or a larger pool. You need to say, okay, is it all, all or none? How are they doing that? You know, how are they going to sell that to me? And we went through pools of how to analyze a pool of notes. So finding the notes, everyone thinks that, well, I'll just go to the banks directly and buy notes from them. We've had no success with that and we know very, very few people that are successful that way. We're buying from hedge funds, we're buying from Some note brokers. But as I went through in detail, there's a lot of these, as they call joker brokers out there that really, that's not where you want to go. We've had very good success with these hedge funds. When they go direct to the bank, they buy a lot of notes, they sell a few to us at a higher price. But there's still a big enough spread for us loan servicers. We delineated very clearly about loan servicing versus the workout. Loan servicing just in general, once again, is the monthly statements. Getting those to the borrower. You paid us this much last month, you owe us this much the next month. Here's your 1098 for the year. Here's all the compliance things. The loan servicers out there are not going to fix your broken notes for you. I had hoped they were. They're not. It's about working it out yourself, learning how to do it as we learned in this course, or hiring the right person. And we had Bill McCafferty come on talking about that. He can help with that type of thing. That's what he does. But my own personal story, relationship building and finding these notes. I developed strong relationships with many of these key players out there and built my note business that way. So borrower analysis, hedging your small bet, Sherlock Holmes style. It's about understanding credit reports, analyzing them, and making a bet based on that. Is he making his car payment? Does he have other credit lines open? Is he employed? What's the family profile? How long has he been in the house? These are the things you're going to learn about as you, as we have in this, in this course about making a bet and finding the story behind the bet. What's the real story? Does this guy have a chance of coming back and paying you on time in a note that you'd be happy to have and be profitable with note analysis. Now we're buying a junior lien. You've got a senior lien in front of you. Traditionally, we bought ones with just current notes, just current status on the first lien. But I've also bought ones that aren't current. I have foreclosed. So there's all these different strategies around that. But senior lien status is a key fundamental part of the note analysis. Once again, occupancy and length of ownership, the note value and proportion analysis. You could have a tiny little first and a big second or different variables therein. We went through all that. Bankruptcy status. Traditionally, I have not bought anything where the borrower was in bankruptcy. Or had a history of it. So. And we went all through that in our bankruptcy piece, which I'll talk about later. Junior liens behind you, things like that. We all need to be competent in this field and it's not that hard to do. There are so many, as we call them, AVMs out there, ePrazal, Google Maps, Trulia title company data where you should be able to look at a property address and zoom in on it. And within 10 minutes I'm going to have a general value of what that house is worth, what your collateral is worth, geography type. As I've mentioned, I tend to focus on the higher end properties. I like that type of borrower. And I can buy a junior lien on a nicer property with a guy that marched into Wells Fargo four or five years ago, got a big loan with a big job. He might have lost his job, but I bet he has a good chance of getting it again. And he has a pride of ownership house, which I like. Pool analysis. Buying pools of junior liens, mini pools, bigger pools, they'll come to you different ways. Some will say you got to buy all these. Or you can pick and choose competitive bidding. You can, you know, you can bid all you want to, but if you're, if you're not in the loop, if you don't have a relationship, you might not ever get a pool of notes. So keep that in mind. Let me talk a bit about the value of analysis. This is a key skill which can be valuable in many aspects. I know people that take other banks notes that they usually have some clerk working on that has not done a great job in building a complete spreadsheet of all the different data fields. They'll take that and say, hey, our goal is to work with you now and in the future let us analyze your pool of notes. They'll go back and do bankruptcy studies, title studies, tax studies, all these different things. Give it back to the bank wrapped in a bow and say, you know, we can't buy these notes, but I think we just changed the value of your pool from this to this because now you've got the right data. So becoming an analyst on these notes has a lot of value in a lot of different ways. I have always encouraged you to become very good at analyzing pools of notes. Emotional equity. We had Dave Van Horn, come on. President of Partners of Payment Relief, talk about this concept. You have to understand this concept because the realities of buying non performing junior liens, I'll tell you the way that I started just to encapsulate it real quick. I said, you know, I'm a real estate guy and I would like to have notes in my own backyard. So just give me Southern California, nice properties, that's all I want. And they said, no Gordon, we have to buy nationally and you're not going to be buying any notes if that's your criteria. And I said, oh, okay. So it kind of, it made me broaden my scope and learning the fact that you know what, I'm not going to be a landlord. I'm not going to have the tenants and toilets and other issues and hassles of a landlord. I'm the lender, I own the note, not the property. So it expanded my horizon once I learned that, okay, yes, there's mortgage states, there's trustee states, there's different rules, but guess what, it's usually okay. So the reality of buying non performing junior liens is you need to kind of broaden your horizon. If you're a real estate guy like I was, understand emotional equity, that that's a key part of this whole equation. We went through it in detail. Let's talk about a couple more real deals here in Sacramento, California. A payment plan and as I've said over and again, it's usually a payment plan. It used to be refinance, where somebody could refinance their whole thing. The way the banks are right now, this current market doesn't exist that way. So you're usually getting a note and turning it into a monthly payment plan that the borrower can afford. The profile, $428,000 first 218,000. Excuse me. 428 for the fair market value. 218 was the first. We bought the non performing $105,000 junior lien second on a quality single family house. Owner occupied, we door knocked it, we filed a notice of default, the customer contacted us and it turned into a $398.07 per month payment for 33 years. Let's go through another one in Las Vegas, Nevada. A short sale. And we've gone through every flavor of how the exit strategies work. This short sale we had a deceased borrower that was always on time, always paid his bills. But when he didn't pay anymore because he was deceased, the bank took exception to that and sold it to us. He had a nice house there. A $220,000 fair market value of the house. A first for 170. We bought the non performing junior lien, the $22,000 lien for just over, just under $3,300 is what we paid for that. A short sale company called us within 90 days and said they wanted to make us an offer for that. And we ended up making just shy of $20,000 in 90 days. So it was a payoff. It wasn't a short sale because it really wasn't short. As you can see, the first is worth 170. The house is worth 220. So they tried to come to us and say, well, we'll give you $2,000 for that note. We said, no, we'll take 20 and got it.