Coach G and Michelle Goddardi walk through bankruptcy strategies for note investors, covering PACER research, Chapters 7, 11, and 13, lien stripping, and cram downs. Real case examples show how bankruptcy creates investment opportunities when you understand the mechanics.
Chapters
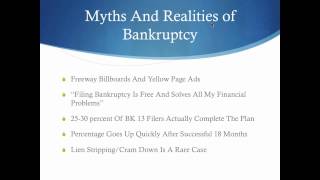
Okay. In module six, we had an expert in bankruptcy. Come on. Because this is one of the fears of the whole process here. Bankruptcy and foreclosure. We talked about foreclosure a little bit. We'll talk about it more. But bankruptcy, Michelle Goddardi is an expert here in Southern California with bankruptcy. And we talked about the context, strategies and history. We went through the PACER system, which everybody should have access to. We talked about it in detail. And you can track your federal bankruptcies in pacer. It's public information, it's cheap. Everybody should have that. We talked about Chapter 7, 11 and 13, basic terminology. And the big thing that, that talks, that people talk about when talking about junior liens is lien stripping and cram downs. We talked about that. You'll be considered a saint when you extend the credit, a devil when you try to collect it. And that specialized knowledge once again on bankruptcy, if you knew bankruptcy, you wouldn't fear it. I know people, and I'm becoming one myself that actually like bankruptcy. I'll buy your bankrupt notes. I won't pay much, but the specialized knowledge will put you in a new position. Frankly, my bankruptcy deals have been better than the rest of my deals. Takes a little more time. Sometimes you have to have patience in this business, as we've talked about, but capitalizing on the current market, Bankruptcy is a huge part of the current market. If you have the information, if you have the PACER information, if you know all the ins and outs of bankruptcy, you can make more informed business decisions with these borrowers. The freeway billboards and the yellow page ads, they say it's free, it's not, and it solves all your problems. I said 25% of the BK13 filers actually complete the plan. Michelle said it's closer to 10%. So when you hear this, oh my God, they're doing a BK13 that could take up to five years. Well, guess what? 10 to 25% of them actually finish the plan. When they don't finish the plan now, they're yours again. You can foreclose immediately. So and lien stripping, this lien stripping, cram down, which basically means that a judge can come in and say, guess what? Your lien is underwater and we're going to strip your lien away. Which sounds like a disaster. But when only 10% of the people actually finish their plan, it's not really a disaster. When you understand that it makes you powerful. Here's pacer, which is the public access to the court electronic records. We talked about that. Chapter seven which is called a straight bankruptcy. And this is one where they're basically it's a four to six month process. An 11 is more of a business oriented bankruptcy. We talked a lot about that. The 13 is a common one and it's called a wage earner or workout bankruptcy. And Michelle did a great job in going through all the detail of this. But it's a plan under which the debtor will use virtue earnings to pay back accreditors rather than liquidating the estate. It's a 36 to 60 month consumer debt restructuring. And the cram down, the process where the debtor claims secured property is actually worth less than the debt. We gave examples and the recent article regarding southern South Carolina court case appraisals for cram downs which kind of showed that the judges are getting it now and, and they're not using all of these reo distress properties as comps because if they can comp your property that shows you have no equity. You're eligible for a cram down bankruptcy. Basic terminology, automatic stay, proof of claim, secured creditor pro se. And here's a couple more deals. These are bankruptcy deals. The profile. $330,000 fair market value. $307,000 first $103,000 non performing junior lien. And we paid 13,000. A little over 13,000 for that non performing junior lien. The wake up and the workout. They filed the BK13. It appraised at 300k. So as you can see they're saying that it's less than the first. So they lienstripped us but we were in a position where we'd never been notified. So we returned that note to our seller and and traded it for another one. So all the legal actions were taken prior and it's a good example of knowing your seller and having a relationship with them. Another one, $245,000 value $210,000. First loan on the property. $60,000 non performing junior lien on a quality single family house. A BK7 was filed by the borrower. The result $600 per month which is pending right now. And they're going to pay all the fees and costs. The first was modified. We looked at this $210,000 first. We could see from their PACER information that it was modified to a 40 year loan. 480 months at 884 per month and he has no other debt. The 7 wiped out all his other junior debt. So here's a guy with under $900 a month and the Pacers show that he made $3,000 a month in his pension. So with a 9, no other debt and an under $900 first, he had plenty of money and has plenty of money to pay us the second. So these disasters called bankruptcy, once you learn about them, don't have to be disaster.