Module 10 Note Investment Mentoring [8/10]
Coach G walks through advanced note investing with real deals: short-selling underwater first liens, buying junior liens, and using Notesmith software to service yourself. He explains why present value matters for reperforming notes, covers investment structures like self-directed IRAs and hedge fund partnerships, and warns that notes are wasting assets that need hedging with real estate.
Chapters
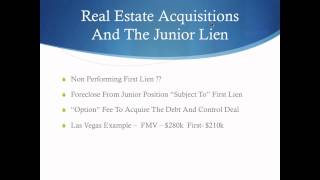
In this bank paperwork, that's the way it's set up. So here's a couple examples. House fair market value of 245. The first lien, $261,000. This is underwater. The first lien is larger than the property. The value, 245 for the property value 261 for the first. The second, which we purchased, $129,000 junior lien we bought for just under $17,000. It was a quality single family house, but it was tenant occupied. And we went through the whole process of our negotiations with the tenant to get the rents coming to us. But we filed a notice of default. The owner short saled it. The result was almost a $23,000 payoff. Now, once again, we only made about $5,000 on that deal. But we rarely lose money on these short sales. Even if it's underwater, you would think, why would they pay you when it's already underwater? They do, as long as you get in the deal and work it. House value on this one, $285,000. $341,000 first. This one's way underwater. An $89,000 Junior Lien. Single family house owner occupied. Once again, a short sale. First lien holder offered us $18,500. You say, how does that happen? Well, it's negotiations. You get some from the realtor, you get some from everybody and you let them know. You say, you know, we're here just to be reasonable. The realtor is going to make 20 grand on this deal and you're going to pay us $3,000. Nope, not going to happen. And your sales? Not going to happen. So it's not being a rogue, but it is being showing these people the light and the fact that they can't close the deal without you. So did we make a lot on that deal? No. How much did we pay for that note? We paid a little over $13,000 for that note. So we didn't make much money, but we got out of it, reinvest the money to get our payment plans, which is our goal. In module nine. We talked about loan servicing and advanced Concepts and we had Melissa Balling from Allied Servicing talked about other servicers out there and the workout people versus collections versus servicing. And I talked about that earlier, but you need to differentiate that that a servicer is not going to be the same person as a workout collections. I talked about some premier loan servicers out there, bsi, fci, and we interviewed Allied Servicing Corporation. I think they're a great one out there. But you need to be suspect of the high touch servicers that these services that these servicers are supposed to give you on these seconds. A lot of them don't understand the seconds business. So we had an interview with Melissa. She was fantastic. I highly recommend her. I self service some of my notes. I use a program called notesmith and here's the website for it. For somebody with 100 notes or less that wants to do it himself and my father helps me. We send the letters out, we do all the RESPA, we do the 1098s, everything like that. Notesmith is a great program I recommend and I went through it in detail of what that program is. Advanced Concepts. We closed last week with Advanced Concepts. And this is really the fun part. We had David Phelps come on, talk about creating a valuable note. And he's got decades of experience with this business and he did a great job. Couple concepts that I threw out here, Present value and the time value of money. This is something that we need to understand and the public does not. You know, it's the present discounted value, the time value of money. For example, when you're negotiating with the irs, they don't understand the time value of money. If they came to you and said, you owe us $50,000, you'd say, okay, well, but I can't pay you today, but I could pay you over 10 years. The fact is, $50,000 over 10 years is not worth $50,000 today. They don't understand that. Insurance companies don't understand that. Lottery companies, excuse me, they do understand that and they prey on the public, in my opinion, because what I call the big lie, the public doesn't understand the present value and the time value of money. For example, an insurance company will say, pay us every month for the next 30 years, we'll give you a million dollars at the end. They don't tell you that in 30 years a million dollars isn't worth a million dollars. Lottery winning, same thing. They give you a million dollars, they don't give you a million dollars. They give you $50,000 a year for 20 years. Structured settlement, same thing. The time value of money is a key concept that we need to understand in creating these reperformers. I talked about my structure for my self directed ira. I have set up an LLC with checkbook control that lets my company make deals quickly. If you came to me and said, I have a deal for you today, I would say, great, I can write you a check today as opposed to going to my IRA custodian and Trying to get, you know, take a week to get that done. A lot of these notes do go bad sometimes. And I had my current hedge funds right now to talk about unsecured loans, which effectively is a junior lien that's been wiped out. The first has foreclosed, it's now an unsecured debt, but. But they still owe you that money. And judgments can sometimes be more powerful than a lien. You can file a judgment, for example in California against a borrower for 10 years and then 10 more. An unsecured purchase. If you could purchase unsecured notes, unsecured loans at a penny as opposed to paying 20 cents for a secured non performing junior lien. Risk management. Something you need to look at. We talked about partials. A note can be partialized. And for example, if you bought a $10,000 broken note and fixed it and seasoned it to where now it's worth $50,000, you could sell maybe the first 10 years of that a partial for 25,000, retain the tail in your IRA. I call it the Roth tail, another advanced concept. But $100 option can explode your IRA and it's completely illegal. Excuse me, it's completely legal, ethical and moral. There's nothing wrong with this program at all. But, but a partial tail can explode your ira and it's a win, win, win solution for good tax free income. We talked about acquisition and the junior lien. I now buy non performing first liens. I buy the junior lien behind a first lien and I foreclose. So you're foreclosing, you're taking it subject to the first. But I talk about this option fee. A gentleman last night called it optionality. And I like that terminology because you're getting in these notes for a little bit, you're spreading your risk so you get to control the deal with a little bit of money. And let me show you this next example of a deal, but also the concept of trading, trading back to the bank. You can take your notes, that they're fixed and trade them back to the bank. You're going to pay the bank $10,000 for some more notes. Well trade them for some paper instead that you've got re performing. And this present value theory, once you understand that. For example, I talked about the IRS example, here's another one. What if you found a million dollar property that you could buy with 10% down, $100,000. But there's only one problem. You don't have $100,000. But say if you had $100,000 note a re performer that you have fixed $100,000 re performer that you only paid $10,000 for, you could trade that note with somebody for that 10% down payment. That's something we're getting into joint venture possibilities. Maybe some people on this call or different people aren't saying, you know what, I like the theory, I like the returns, but I'm really not that guy. I'm really not the guy that can spend the time and the energy to do this. I see how complicated it is. But a potential passive investor opportunity. Our company just did this last week where we basically went in a joint venture with a hedge fund. We bought the notes at the hedge fund price. So Instead of paying 10 cents, we paid say 5 cents and we're looking at a 12 to 18 month capital recoup to get our money back. And once our money's back, then it's a 50, 50 post investment recapture going forward. And they charge a 20% workout and management expense. So just a thought around how to look at this business and quality re performers. A 15% return for a passive investor is very doable and it's what I see out there in the marketplace. If you took a note, fixed it and gave an investor a 15% return, a passive investor that understood this process, that's the strategy out there. PPR Partners of payment relief. If you go to their website, they sell those every day and they're flying off their website. So you also, if you do buy one of those, well, what could happen? Well, if you understand the business a little bit, you understand that it could be an early payoff or you could stop paying, you could do a short sale. So reperformers. I closed it last week with a thought that notes are a wasting asset. And what does that mean? You know, I think it's the best time in history for this business. But inflation and time will eventually erode your Note investment to zero. That's why I've named my company realestateandnoteinvesting.com, my website because my goal is to create perpetual inflation hedged passive income. And I'm developing another course because we're. I'm also a real estate person. But you want to hedge what you're doing with real estate that grows and the rents go up and it taxes benefits you as opposed to the note income. The note income is great. I love this business, don't get me wrong. But you need to do both in my opinion because notes are a wasting asset.