Coach G explains why non-performing mortgage notes are worth buying right now. Prices dropped after the 2005-2010 lending boom, creating a two- to three-year window to buy discounted debt. You need foreclosure knowledge and a deal structure where you win whether the borrower pays or defaults.
Chapters
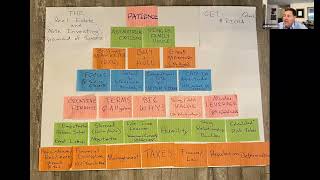
Now I'm performing notes. This one. I'm in this full time right now, as are some people in the room, a lot of my friends out there. What I've done is I'm focusing on this today. I wanted to add those first too, but once again, Quixote Ventures, name of my company, I call it a unique approach to the perfect financial score. And I've already kind of given you my background in philosophy, talked about the 2020 vision. Why non performing notes, why now? There is a glut out there of this non performing debt. The things we're buying now were originated in 0506 07. Anybody could have got a loan and they did. 08, 09 10, not really go to the bank now to get a second on your house. Not gonna happen. So my point is with that is that it's a unique window right now where they made too many loans three, four, five years ago that they're selling now at a steep discount and it might not last that long. I don't see this as a 20 year plan, 10 year plan. It's kind of a niche. So, you know, the whole other part of the landscape. Why notes, why now? With prices relatively low, you know, some somewhere like last days, you know, 60% drop in values, interest rates at all time lows, it's just a great time to get into the note business, in my opinion and figure it out. So that's why notes, why now? As I mentioned, I think we got a two year window, maybe three year window. Not saying they'll go away, but there's so much of it right now that gives you as the buyer a better, you know, chance to buy a better note at a better price. Once it's, you know, the market tightens up, prices go up, quality gets worse, etc. So this next point, I call it, what if your biggest fear wasn't. What is the biggest fear in buying a note value? Well, after you buy, you've already said, okay, the value is this bankruptcy, foreclosure, you're saying, hey, this guy might not pay me, this guy might go away, this guy might file bankruptcy, I'm going to have to foreclose. What if you bought the note at the kind of price where it didn't matter where it was a happy, happy note, you're happy if they paid or happy if they didn't. So that, you know, I look at the note market and you got a lot of these gentlemen that have been around for a long time, but they mainly focus on the seller finance part of the world. The gold plated first trust deeds that pay every month. And that's the way they evaluated them. They're not really in this space, in this non performing note space. And if you like, people in this room have spent the time to get an education in foreclosure bankruptcy. Well, that doesn't really bother you. You know the rules now. They are being changed by the legislators every five minutes in the newspaper. But you kind of roll with them and you understand the risk. So, so that's kind of my, my point about what if your biggest fear was.