How to get an 800 credit score in 27 days and use it to buy houses. With Charles Noonan & Brendan B
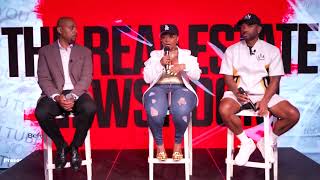
This is a recorded live session (YouTube) where Tamara Glover Sims (Credit "Doc Tam") gives practical, audience-focused guidance on personal and business credit and how to leverage credit for real estate funding. Key points: payment history comprises ~35% of score; keep credit utilization at ~9% or lower; maintain a credit mix and an average personal credit age ~3 years (business ~5 years); limit inquiries to two within 6–12 months; authorized-user trade lines can be used (including installment AUs via Navy Federal); business profiles should have ~10 positive accounts with two primary cards totaling $15,000+ in limits; Dover Federal Credit Union offers soft pre-qualification up to $50k at ~11.74% (personal). Tamara reports helping nearly 1,000 people, raising scores up to ~840, and funding up to ~$1M for a client (combined personal, business, mortgage).
Questions this video answers
Approximately 35%.
About 9% or lower.
Two inquiries (max).
About 3 years (average account age).
About 5 years (average account age).
Chapters
I've been going, going, going, going, going, going Crazy. No, you can't blame me.
You have a hustle crazy.
I've been going, going, going, going.
Credit and funding specialist. All right? The reason she's in the. In the community because she has been one of the most proven and successful credit repair specialists, and she is killer with the funding. Like, we had people ask about funding, and we don't really use too many banks for, like, 20, 30, 40, $50,000 because she. She got them, like, on speed dial, right? Like, I called the bank the other day. We were on the phone, we wanted to get a sponsor. Then I'm like, nah, let's just use TAM for this one, right? So she. It's better to work with a funding specialist or somebody that does funding because they have relationships with multiple banks, as opposed to me just sending you to one. We have somebody that has multiple. All right? She flew in from Atlanta to support anybody here whose real estate endeavors may need assistance with credit or funding. All right? So her name is Tamara. She is my funding and credit specialist. And now I'm gonna hand it over to Brendan.
So what I heard was that she's been funding over millions of dollars, like, literally helping people get over millions of dollars of funding. And she's helped repair and restore almost a thousand people's credit. Which. Which is. Which is amazing, right? Yes. This amazing person right here. So she has a lot of information that you guys definitely need to lock into by show of hands. Does anyone feel like they need to repair their credit fix, maybe, you know, do anything to their credit? Anyone? A couple people.
It's the same space. Y' all can raise your hands louder.
I mean, I'm gonna tell y' all my credit was busted for a couple years. Why is your, like, 10 years, 15 years?
Well, ask him why his hands up.
He's contributing. No.
What's your credit score? Say it. He got, like, a 780 credit score.
He wants to eight, bro.
Oh, you raise your hand because you want the 800. All right. That's Kaden back there. That's my son, by the way. He said, do who need help with credit, and his hand is up. I'm like, what? I know his credit score. I built it. But TAM helps me to tell him what to do to build his credit score. So his credit score is a 780. He trying to get to the eight hundreds. So if she asks any Q and A, I want to hear you ask her, how do I get into the 800 Club? All right, anybody in the 800 Club. Aside from me.
Oh.
Shout out to Dove. One, two. Dana don't need credit. She could just buy whatever the hell she wants. All right, cool. 700 Club. It's a safe space, guys. It's okay. 600 Club. Show of hands. 500 Club. We got one back there. The VP of enrollment. He don't pay his bills. You just gave me a crate.
You just gave me an idea, bro.
What you got?
I feel like everyone in your community should be a standard. Everybody gotta be over seven. And then everyone in my community gotta be a standard. You gotta be over seven. Not that you can't make moves without it, but I think you in the room. Yeah, you got it. Like, you might as well listen 100%. So we gotta talk about that, but I think that would be. That's like, a prerequisite. Yeah, he's like, you can't be my friend if you ain't got a 700.
I almost don't even want you around me if you if.
Because.
Yeah.
She said, stop the nonsense. Why is that nonsense? I pay my bills. You pay your bills. We're making money. Pay your bills, too.
So the people that's going to be in the room with you are people that's trying to get to where you're at. So stop saying no.
Well, that's not what I'm saying. You could be around if. If you have the mindset to become the person that God designed you to become at the highest level. But if you don't. If you don't desire to do that, that's different. If you got a five or a six and you want a seven and an eight, and you want to, you know, hang out with Dana and acquire properties. Hang out with Charles and acquire properties. I'm cool with that. You're only going to need six months. 12 months. 18 months. Your life is going to change. Read some books. Be in these type of rooms. I'm cool with that.
We got three books left, by the way. All right. No, I'm saying you're going to read something you might as well read, since you're talking about books. All right, But I think what he's saying, Samantha, is like, we're not going to tolerate you sitting around with a 600 and a 500. And we got the resources right there. 100 in the community. Yeah, you in the school community. You can just shoot her message, hey, get this off my report, please. And she'll handle that.
So we got to install that. But without further ado, we're going to Bring out someone who flew all the way from Atlanta to give you guys as much value as possible. And take the sevens to the eights. Take the six to the sevens and you know, and allow you to not only leverage OPM to acquire more real estate, more assets that are going to be cash flowing. So without further ado, Tamara Glover Sims, come on out.
Teach us, Tim.
Teach us, Tim. Teach us, Tim. Teach us, Tim. Teach us, Tim. Teach us, Tim. Teach us, Tim. Teach us, Tim. Teach us, Tim.
Hey, hey, hey. Welcome, welcome.
I don't know if that one turned on or not.
Okay. Can you guys hear me?
Oh, you good?
Hey, guys.
I need a hug too.
I'm a shorty.
Thank you.
Spread the love. Spread the love. Okay, let me get up here.
So when we talk about environment that doesn't stand for height, I could not help you grow if you just gonna be around me.
Big things come in small packages.
That's right. That's. Yes, yes, Big Tam, not the little one.
That's right, that's right. Hey, guys. I'm so happy and excited to be here, guys. Thank you guys for having me. Look at me on this awesome panel between these two handsome guys here. But anyway, guys, my name is Tamara. I'm known as Credit Doctam in the the funding and credit world. I help people restore and get back what was not really technically messed up. When people say fix your credit, your credit really is not broken. Credit is. We're actually the first creditors. People don't know that. So you extend credit to other people. But that's a whole another conversation for another day. I only got a few minutes up here, so I have helped over almost a thousand people to restore their credit, to build back, to get the lives of their dreams, to help with their children, their families, their future, to help mentally. Because you know when your credit ain't right and you can't get nothing, you all, you know, misconbabulate. Everything's messed up. It can ruin family's homes and sometimes people's lives. But that's what I'm here for. That's what God blessed me with. But I didn't always have great credit as well. That's kind of like how I got in this space married, went through a divorce and my ex husband had some things on my credit I didn't know about. And I was trying to rebuild and just rock bottom and started studying and getting into groups, into rooms and around people. Like you said, when you get around certain people, certain things are going to automatically happen. So it caused me to Grow and to learn and more and. And I just stuck my head down and started getting into places and learning and learning and learning and learning, like whoa, whoa, whoa. And so I've been blessed to help other people to do the same and to get funding of millions of dollars and whatever their heart's desires are. So I hear there's some questions for me.
I got one, but you almost answered it, right? That was a lot. And I appreciate it because I wanted to know, like, what got you into learning about credit?
So I came from a household of. My parents were young when they had me, and so my mother was mostly the one who raised me. And from an early age on, my mother always talked about, you got to own real estate, you got to own real estate. And so she was in her 20s when she first bought her first two unit property. And that was just the one thing. She was the first person in our family to do that. And she always talked about the importance of credit. But she also had 45 million, 000 credit cards too. And I saw her run them up and then she'd be, you know, all miscombobulated about or whatever and then she get out and all these things. Then she filed bankruptcy. And I'm just like this, the credit thing, it looks like free money. It looks good. But got married, bought a lot of properties with my husband. Fixed, flipped and all that. The crash came in 2007, eight or whatever. Everything went down and then kind of built back up. And then he was doing things using my credit that I didn't know about. And then we went through the divorce. I tried to go get something on my own and I'm like, what is that? I didn't do that. What is this? Oh my God. No, no, no, no, no, no. So anyway, that's how I got into that. Someone told me, okay, there was a book some time ago where it was like the credit secrets Bible or something, whatever it was. But anyway, I got this book, started sending letters out, then I was getting pushed against the wall, then I started digging deeper, going in a hole and being around people, going to groups. And then that's how this whole thing started from my credit being at a 400 and something.
400 and something?
400? Yes, you can go to a 350, but I was almost there.
Oh, so I skipped the whole club. We had somebody back there in the 400 Club. We got 500, 600, 700, 800 Club in the room. So you can help those people in the 300.
I've been there life Lifes, you know, but the thing is, it's really not broken. We're the first creditors. There's so many laws that Congress put into place for us as consumers. We're consumers. We're the first creditors. And credit to the creditors, technically they're using your own money. So you should never have bad credit. Bad credit is not a thing. But we'll play their game. You know, we play the game and so we can get what we want right now.
But you know, all right, let's, let's. Because you talking a little heavy. She talking a little heavy, right? What's the highest increase you've gotten somebody in credit so far that you've worked with?
When you say highest increase or a.
Score, meaning score, like score increase.
I've gotten someone as close as to 840 something. But here's a, here's a kicker. If you got a 750, you're gonna get the same thing as a person has a 800 and 850. 800 is great for bragging rights. But guess what? If I got a 750 and you got 850, we're gonna get the same thing. If we have the same, you know, built out profile. It's about the profile, the scoring always what gets you. You can have a 750 credit score and get turned down and denied for everything under the sign because there are certain factors. There's like 10, well, five different things that make up your score. But there are certain things that lenders and credit card companies look for. And if you don't have those other things but you got the score, you still won't get it. So I can go over those things with you guys a little bit.
Yeah, that's actually what I was about to ask you. You kind of touched on a little bit because you can have the nice scores, but it's really about the profile.
The profile that's the most important thing. The, that's the bare bones of it. What's inside of there.
So can we talk about what that mix looks like? Like what do they need to have what makes a strong, tight profile?
Sure. So for the personal side, it looks different for personal and it looks.
Let me interrupt you real quick. Notebook. Notebook. If there was ever a notebook. Time, this is it. Notebook. Go ahead.
So personal funding and credit can look different than what you need to have for the business side when you're personally using your personal credit. So if you're just kind of, you know, starting out, you want to get, you know, some credit cards or Whatever, right? There's a few things that they want to see. The first thing that makes up your credit, there's five areas. First of all, to make up your credit score and profile your payment history. How do you pay your bills? How have you been paying your bills? That's 35 of your score itself. So meaning if you got a late payment, a charge off, a collection, a repossession, a bankruptcy, a foreclosure, there could be a tax lien, there could be child support on there, they could be all those things like that. Those are derogatories, those will drop you minimum like 100 points. So you want to be a hundred percent with none of those things on your credit profile. Now there is a little exception to it. If you do have a late payment and it's like 36 months old, it can kind of wash itself out in your score. Some lenders will be okay with it, right? Some lenders are like, no, it's a no, no brain, no, no deal, no. But that's the first part of it. The second part is your credit card utilization. This is where your balance is in reference to the limit. A good place to be is at 9% or lower. So for every hundred dollar limit, you don't want to owe more than $9. So if you got a hundred dollar credit card, don't owe more than $9 or lower, if it's $1,000, $90, credit card utilization is very, very, very, very important. You can have a 750. And again, if that utilization ain't right, you're getting denied. The next part is they like to see a mix of credit, meaning having installment and revolving. Installment is like a loan, revolving is like credit cards. And then also charge cards which are like American Express and then mortgages. These, they like to see multiples. You don't want to just see all loans, student loans. They don't want to see all, you know, credit cards. They like to see a mixture. They want to know that you can manage different types of credit. So you want to have both kinds. And then your age, your credit age is very, very important. You can have 10 brand new student loans and then you can have maybe five old accounts because those student loans are newer. And they take, what they do is they add up all the years of all the accounts, including the months. They add them all up and then they count how many accounts you have. And then they take that number of accounts and divide it into whatever the years added up to and that's your average age. They go by your average Age, not that you got your first, you know, car back in 1996. That doesn't count. It's the average age. So your average age for personal credit minimum, you want to be about looking like you're three years old. Now if you don't look like you're three, there are ways to boost your age up. You can always buy what's called authorized user trade lot and add it to your credit profile. And you want to get something that's got a lot of years on it that's going to boost you up. But be careful, because when you get that authorized user trade line, you're taking on that person's history. So if they've ever been late, guess what? Now you got a late. If they keep a high credit card utilization, guess what? Your credit card utilization is now high. So you got to pay attention to all of those factors and all those things.
Hold on one second. Did y' all get that? Everybody understood that. I never thought about that. So I know you can add people onto your credit card and, and they can add you onto theirs, but nobody ever says, wait, just check, let me check your stuff before you add me on. Because if you paying late and I'm paying late, you're not helping me. Did y' all think of that or would some y' all just be like, oh, put me on your credit card? Is that how it works?
Is there past payment history a factor, or it's just like from the day you. It's from the day that they open up their account to the current day. So their entire payment history on that particular credit card. And they can have other credit cards that might have been late, but the one that they're adding you to cannot have any derogatory late payments on it because now you going to have it.
Now we got one more question. Then we have two more interview questions.
Adding the one to the authorized user. So say you're a child, for example. How long would you have them as an authorized user? They're paying the bill on time, they're doing what they're supposed to. They started. So you're saying that you have a your child and you're adding them onto your credit card to build up their credit history. I would keep them on there only if I'm keeping my credit card utilization low. And then they're about to go get new credit because it looks good because the account is still showing open. Now once they get their credit card or whatever they're trying to get, then you can take them off your card and then it's going to still stay on their credit report, but it's just going to show as a positive closed account. Because whenever you close accounts, your score takes a little bit of dip. It'll level back out, but it's going to take a dip whenever an account closes.
So get your kids off the credit cards. No, I'm just kidding.
My Christian is very simple. I'm thinking it would be for if you get a trade like company that you pay because I know there's a company out there you can, you can get a trade guy from there.
Yes.
It would be hard for them to give you some, some name with the negative.
Well, you know, two companies that I go through, I've never seen it before, but I have seen it where people buy trade lines from other people. They bought a Discover card that they thought was good and then when it hit, it hit with a late payment. So make sure it's from a great source if you're going through a company.
All right, we got two more interview.
Oh, I just want to say to that, that part about the credit profile. The last part is inquiries. They don't like to see more than like two in like the last six to 12 months. After that they kind of don't count. Some lenders want, you want it to be 12 months, but some will be, you know, okay with six months. But two inquiries is your max. After that you're looking like you're desperate and you're, you know, reaching for too much credit. You high risk then. And then another thing too you want to pay attention to is names. Get all misspelled names off your credit profile. Get all old addresses off your credit profile and get all old employers off because these are called data points and they pay attention to that too. And then here's another little kicker for you guys. Get you a good zip code because you may not know it. You were talking about redlining with, with purchasing real estate. You can get redline with your zip code. They look at how other people in that zip code pay their bills and how much their income is and they'll kind of box you into it.
Crazy.
If these mics weren't expensive, I would say drop the mic. These are the Sure 1000. You can't drop them. But that's a mic drop note.
Even with your business. Put your business zip code in a high income zip code there. I promise you you'll get higher limits and stuff like that. Zip codes make a difference.
Show of hands. If you just learned something. I didn't know that.
Yeah, she going crazy.
I. I got one question. You got one question. She's not leaving. She'll be over there. The whole. She'll be over. She'll be over there. My other question is from a funding perspective, because I hear you out here killing it. What's the highest amount of money you've ever gotten? Someone funded?
Talking about one person, one person collectively. A million. Yeah, million. Yeah, but that's with personal credit, business credit, and including a mortgage.
You doing mortgages out here?
Well, I can kind of, you know, help some people to, to qualify for certain people's criteria.
Oh, my goodness.
You know, I've been buying. I've been getting mortgages since 2003. 4. And I was actually. You don't know this, but I was actually a mortgage broker back in 97, 98. I was a real estate agent. So I know a few little, you know, little things and stuff.
You told me.
Okay, I got a follow up question on that. So if someone acquires the funding, right, like that million dollars, what should they invest in? Or what are some things they can invest in to create some cash flow once they get access to funding?
The number one thing that everyone should. Should. It's like it stands the test of time. Like you talking about, people always need somewhere to live. You got to get some real estate, even if you don't want to take care of it yourself. You get a property manager. You don't want the headache. Pay the 3,4%, write it off on your taxes, but do some. Get some kind of real estate. That's all I'm going to say. Even whatever it is, just get. Real estate is number one. That is number one. Number one. Number one. Number one. And then from there, you know, you can, you know, if you want to learn stocks, learn stocks. If you want to learn crypto, learn crypto. But the number one thing, people need somewhere to live.
So you're saying they can leverage funding to then acquire real estate?
Oh, absolutely. They can leverage their fund, their credit to get real estate. There's real estate where you can get no money down or buy some for 150 bucks.
Teach us, Tim.
Teach us, Tim.
Teach us, Tam.
Teach us, Tim. Teach us, Tim.
I mean, people go out to dinner for the cost of some land.
Hello.
They got it. So.
Yeah, in New York, too. Every time I come over here, I'm spending a bag.
Yeah, all right.
I ain't lying, y'.
All.
You just ate a lot.
So, guys, we're gonna ask Tam, right? It's gonna be her turn to teach Us, whatever she wants to teach us, we're gonna ask her to give us one more gem and then we gotta get her off the stage because she came in from Atlanta. But Brendan also wants to teach us some six figure strategies as well. So, Tam, you got one more question?
B. I got a lot of questions, but I think the profile, I like the profile question. We, we touched on that because I feel like that's something that people, you know, they, they want the score, but it's really the profile. I think this is a good question, though. What do you think? Is it? Well, you would know this. What. What's the number one thing that, that maybe holds someone back psychologically from fixing their credit score or, or fixing their credit in general? Because a lot of people, they, they may have bad credit too far.
They think that they're not fixable. They think they're way out there. They're way too far out. Nobody can help me. This cannot be done. I promise you. You probably haven't don't have the worst that I've ever seen. I've seen people like a hundred collections. I mean, any and everything on your credit report, I'll just say this. Anybody out here, just raise the hands. Has TransUnion, Equifax, or Experian ever contact you to say, hey, can I report this? Capital One, can I report this collection? Can I report this inquiry? Can I report your name, your address or employer, Anybody? Okay, well, guess what they did to you. If, if any of those things are on your consumer credit report. They committed fraud and identity theft to you. Because Congress put laws into place that says that as a consumer, before anyone can put anything on your consumer credit report, they have to get prior consent and permission. So when they did not, they committed identity theft and fraud to you. So every single thing on your credit report is fraud. And you can get anything you want removed.
Notebook, notebook, notebook, notebook.
So if you're, you're not too far out there, and it's not that, oh, it can't happen, or you may have been attacking you, like, they won't remove it. It keeps coming back verified. It keeps coming back verified. I'll tell you why it's coming back verified. And then after this, I know you guys will probably want me to stop, but the reason why they do this is because you are a cash cow. TransUnion, Equifax, Experian, they get paid every single month from those people who are reporting those things about you. Whether it's good or bad. They get a check every month for you. So your cash cow. These are shareholders that built. These are billion dollar companies. This is how they make money. They don't want to remove the stuff if they don't have to. And some people are satisfied. Oh, they took one thing off. They deleted it. Oh, thank God. But now you got 11 more.
They.
Okay, they take one more thing off. They're doing this because they keep making money every single month. And this is. Don't put this on out there. But what I'm about to say, all three of them are owned by a company in Ireland. Experian is the mother of all them. They're Their mother company is over in Ireland. They're all owned by the same company. They all have the same securities q sip number and there's like 400 other secondary credit bureau agencies, and they're all owned by the same people. So you got other people housing stuff about you without your permission too. So they're just feeding off each other, that's all.
Teach us, Tim. Teach us, Tim.
Teach us that she's smoking us. Mic drop moment. I don't know how to close this session, bro.
I mean, are you gonna give her opportunity to. To. To give, to get some more game?
I say I'm going give you one more opportunity. Three bombs right now. Give us one more and then we going to teach us. Tam us out of here.
Okay, well, before you give. Before you give one more. Does anyone feel like they need to connect with her? Like, as soon as you get off, raise your hand if you feel like you need to connect with, with, with, with, with. Tam.
Raise.
Keep your hand up. Okay, cool. Well, we can do a Q A.
Sure.
Or you want to just do that? Like two questions. One take two.
Yes. Yes, yes, yes, yes.
All right, well, hold on. Let her go in the back. Because I know she had a hand up for something. A previous question. Yeah, I'll come. Yeah, I'll come. It's cool.
We're giving you a mic.
I want you to put this on a plate. Cause I know you can serve it up.
Okay. All right. All right.
Spicy.
Okay. Okay.
Wait. Before you do that, can I have your permission to use that?
Yes.
I love it. Right? Yeah.
I had to ask. I had to ask.
Thank you. Can I get permission, too? Cause I'm gonna start saying I'm about to serve it up.
You gotta ask me.
I gotta ask you.
Okay, go ahead.
But let me give you a qualifier.
My name is pull.
My name is Pete Chadduck, and I'm in the real estate business since 1992. Both mortgages and real estate. And a paralegal with a heavy duty New York City law firm where I led 82 paralegals. So what she's saying in regards to credit is she's a queen. This is the first time I ever heard you or met come into your eyesight or heard your name, but you are straight up straight. But here's where you could serve it up. Please share about credit for a business, business credit and business credit. Stacking.
Boom. Okay, stacking. So what I shared initially was for personal credit. So now if you want to get business credit, you have to personally guarantee it, meaning you got to use your personal credit. So this is how your profile should look for the business side. You're going to need minimum, whatever credit bureau that they're going to be pulling from or using. You're gonna. This is notebook, too.
Yeah, Notebook for real notebook.
Note takers are money makers. Okay. I always keep a note. But you see, I got the pen in my hand, but I left the notebook because I was like, I might have to write some down, but left the notebook. But anyway, you're going to need a minimum of 10 accounts, 10 positive accounts, no derogatories. 10 positive accounts on your personal profile, whether it's TransUnion, they're going to be pulling from Equifax or Experian. And out of those 10 positive accounts, eight of them have to be primary, meaning yours. Two of them can be authorized user accounts. Now, I'll give you guys a company that a lot of people don't know that you can become an authorized user on an installment loan. And that's not really popular or known, But Navy Federal, if someone has a Navy Federal loan, you can actually be put on as an authorized user on their loan. Most people only know about authorized user trade lines for credit cards, but Navy Federal will allow people to be authorized users on installment loans.
But that's not bomb drop. So this ain't the authorized user on a credit card.
No.
So what's an installment loan alone?
A personal loan, an auto loan, a secured loan with them. It's called a shared pledge loan.
So I could put a boat loan. I could put my son on my auto loan.
Yes.
And now he has auto loan history.
Primary. I mean, I'm sorry. Authorized user installment history. Yes.
I'm not doing it. Because he's going to go get a Ferrari. I am not doing it. Sorry. I'm not doing it. Thank you, though.
You're welcome. So, yeah, so eight primary accounts. And out of those eight primary accounts, you Want them to be a mix. You want to have installment, which is loans, and you want to have revolving, which is credit cards. Now the requirements for the credit cards, this is where you want to get the big money. You don't want the little peanuts, right? You don't want those little 500, 5,000, whatever you want big money. Two of those credit cards that are primaries, they have to equal the limits of $15,000. So one of them could be a $10,000 card and the other one of five, or you can have 27500, but long as the two of them equal $15,000 in limits. Now, with those $15,000 limits, remember, do it. Does anyone remember what I say? The utilization number has to be percentage. Exactly. Or lower. Right? Okay. That's the sweet spot. Okay. Then you want to have no more than two inquiries. So try to keep it at zero if you can, but two or less inquiries. And what else? Age. Okay, with the business side, minimum, you want your average age to be five years, not three, like personal. So they're looking for you to be five years average age. And if you don't have the age, what can you do? There you go. But you're gonna do what with the au? First make sure that they are AU is authorized user, authorized user, trade line. And you're going to make sure that their utilization is not high. And you're going to make sure they don't have any late payments in their history. And you got to make sure their age is there. Because just because you add an AU on your account doesn't mean that you're going to get the age. You got to actually see how old it is, put it in your calculation and then see, okay, if I add this, how old will I be now? Because just adding one you don't want to do. You want to add 15 AUs, because you can get in trouble for that too. They'll deny you for having too many AUs. So two AUs I say is kind of max, no more than two, because now you can look like you, you really, you know, fishing and high risk again. So keep your AUS at about 2. And then the thing with AUS are don't add them until you're ready to bust a move because most AUs only keep you on for 28 to 30 days. After that it's gone and it's a waste of money if you weren't ready. Let me see. I think that might be it for the. Oh, and then. So certain credit card companies have more than one credit card and sometimes there's like Credit card plays and stacks where you can get more than one credit card in one day. When you're applying, if you kind of have multiple windows open, playing with the algorithms and all that. And then with business credit cards, you always want to go for the ones that have zero interest first.
Can you give us a company we can go to to get one at 0% interest? I mean, you given us everything else.
Wells Fargo is one. Chase is one. Yep, those are two.
Thank you. I just figured I ask for anybody that wants one. Yeah.
Who? She had her hand up first in the back, and then you.
Y' all do know Brendan's gonna teach a six figure Strat media strategy, right?
Go for it.
Oh, I wanted to ask you, how do you look up your business credit without paying the fee for report? Like Dun and Bradstreet? I used to pay like 2. 2500, like back.
No, no, it's not 2500. No, no, you can get. It's called credit alert Monitor.
Used to be. Until they got sued and then they lower the price.
It's, it's. I, I've been checking my business credit for now for probably about four or five years, and I've only paid the max, I think is maybe $49 or something like that.
With D and Brad street, that's after they got to.
Okay, yeah, before I. Before that it was more. Okay, yeah. So you can check it for like $40 something dollars or you can go on nav.
Yeah, I'm on Nav. But I can. I can't see the whole report because I'm not paying that amount.
Which part of the report are you trying to see? Because when you go on Dun and Bradstreet, they don't give you company names, they just give you the, the categories. Like it'll say like office supplies or whatever. They never give you the name for.
Me before because the vendors that I was using, they don't report. So I had to report it to Dun and Bradstreet to put in my report. So now experience in Equifax is on navigation and not really done in Bradstreet, but you can't really see the whole information.
So when you say the whole information, are you meaning like the, the SEC code and AC codes and stuff like that? So that for those, you have to go over to Dun and Bradstreet and pay for their credit monitoring service and then you can actually do corrections and update the stuff over the phone with their customer service. It's faster that way.
Okay.
And then when you do do it over the phone, they're going to send you an email to verify. If you don't respond to the email that they send to verify, they won't do the updates.
And you do you do negotiable instrument also?
No, I don't.
Okay. All right.
Thank you.
You're welcome.
I mean, we got one more, two more.
We're done, bro.
It's a wrap. All right, so y' all gonna have to check Tam out on this side.
Yes.
Yeah.
Come on, B, come on stage.
You want to ask a what?
We're not getting kicked out this week. I got kicked out last time.
For those of those who want to see if they pre qualify, there is a lender.
Yeah, she going to give some free money. Some. Oh yeah. Let's go. All right, let's get our phones out.
Yeah, somebody get some money for me cuz my phone in the back.
There is a credit union that does a pre qualification. They pull from experience. It's a soft pull. And you want to do their pre qualing, not just a regular one. So the name of the credit union is called Dover Federal Credit Union notebook. And make sure you google for the pre qualification pre approval, not the regular one. Because you want to do the soft and it's going to be through Experian, real simple. You know instantly if you qualify.
Dover Credit Union. Dover Credit Union.
Dover Federal Credit Union.
Dover Federal Credit Union.
Who's heard of that before? Oh, we got some people that wanted to get some money. But you, you got money from there? Samantha. You got some money from Samantha, From Tamara. Why do they whisper their results?
How much?
Oh no, she said she mentioned it before. Oh, somebody mumbling. They got 32 properties. I'm like, why are we. So you gotta create a.
We gotta cultivate a. A different environment. It's not of people just being more confident in their accomplishment. So other people can also be more confident to take those, take those moves.
Dover will give you up to 50k. And the interest rate is 11.74%. That's personal.
That's personal for sure.
Yeah. Yes, Dover Federal Credit Union. But make sure again, do the pre approval, pre qualification, don't do the regular one because they have two. Make sure you do that one. It's a soft pull on experience.
Find out how much you can get. All right, guys, heavy claps. Heavy claps with Tam and we're going to get her out of here. Teach us, Tam.
Teach us, Tim. Teach us Tim. Teach us, Tim.
All right, you guys keep me posted. Let me know who gets what yeah, she'll be open.
She can be over on the left side.
Yes.
Oh, give.
Give your social. They want your. Oh, wait, wait, wait.
Hold on, hold on, hold on. Can. Can y' all take your phones out really quick? Let's get. Let's get Tam's Instagram. Let's get a quick little video, a picture of her. Make sure you follow her as well, and then tag her. If you tag Charles and I as well in the same, then we can reshare it. But definitely want her to have this moment for sure.
Credit Doc Tam C R E D I T D, O C. And then Tam T A M. Credit Tam on Instagram.
Doc, doc, doc.
Yeah. It was a pleasure, guys.
Thank you. Thank you.
Thank you, guys as well.
More from Charles


She Made $65,000 Selling LAND… Not Houses! | Nicole Taliafero’s Real Estate Strategy
How to Scale Your Business with Funnels, Live Events & Paid Ads | Featuring Milly "The Funnel Kween"
The Biggest Real Estate Expo Ever. Learn how to pick, purchase and profit from your 1st property.
CBS News Birmingham Is BOOMING! How Developers Are Turning Vacant Land Into Wealth LIVE Sept 18-19
NYC Realtor Has 6 Streams of Income and will be a Millionaire. Nicole Taliafero and Charles Noonan
This Land Flipping Software changed my Real Estate Business, and you get it free.