Stablecon 2025 - Fireblocks Stage: A Fireside Chat with Jason Yanowitz & Simon Taylor
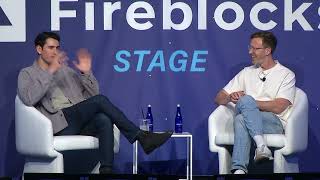
Simon Taylor argues stablecoin transaction volume is tiny compared to traditional systems, but the payments segment grows 4x year-on-year. He projects stablecoins could capture 5-10% of SWIFT's $5.5 trillion daily volume within a decade, and supply could hit $2-3 trillion by 2028-2030. About 60% of Tether settles on Tron, not Ethereum.
Chapters
Please welcome to the stage our next session's moderator, Jason Yanowitz, founder of Blockworks and Digital Asset Summit, joined by Simon Taylor, founder of fintech Brainfood.
Hello everybody, how we doing?
Hello, how are we?
Nice. This is great.
Taking a photo, I'll take that.
Great. Um, Simon, I thought we could— so, so I actually just arrived, but I was chatting with people out there and palpable excitement over stablecoins. Obviously, it's a whole event around stablecoins. I'm curious maybe to get the other side of that take, though, which is what is the most potentially overhyped aspect of stablecoins right now?
The data and the volumes. I think people are talking about trillions when they should be talking about billions. Billions is not nothing, but it's a tiny, tiny fraction of what Citibank would do in a day. I mean, it's a tiny fraction of Wise. Take a local remittance company and they'll be doing a lot more than everything that's happening in stablecoins right now. So the important thing to pay attention to is not the misleading headline figures on the data. The important thing to pay attention to is the growth rate. So the guys from Artemis, You know those guys? They just released a report with Castle Island looking at like a bottoms-up analysis of what the use cases are and where it's all going. And they reckon that like less than 1% of the transactions happening with stablecoins are anything to do with payments. But, and this is the kicker, it's by far the fastest growing segment and the growth rate is underhyped because it's growing like 4x year on year and accelerating month on month as well. So, If that trend continues, it's going to be fascinating.
All right. So basically, if we're looking at like the evolution of stables, we have Tether kicks it off trading, trading on centralized exchanges. USDC comes along, right? Does like shoves stables into DeFi. And now the narrative is like some cross-section of cross-border payments, actual, like, you know, B2C payments. Maybe FX comes in a couple of years. What is the If we fast forward a couple of years, 'cause the title of this is what does the next decade hold for stablecoins? If 99% of the volume of stables is really just traders, right?
Yeah.
It's the pair for the asset. 5, 10 years from now, how much of the volume is coming from payments, FX, cross-border payments, and cross-border payments versus trading, whether that's on-chain or with the SECSs?
That's a difficult one, right? Because you've gotta define volume in a really fascinating way. Everybody does the comparison with Visa, but the real comparison for stablecoin volume is probably the notional kind of transactions across the DTCC on an annual basis, which is $1.6 quadrillion. Like, if you want to get into like an apples-to-apples comparison, so the apples-to-apples comparison for stablecoins is probably SWIFT. And I think they're doing about $5.5 trillion a day. And stablecoins today, you know, if you take 1% of the daily flow, what's that of the annual flow? It's $200 and it's $22.4 billion per day. Got a long way to go. But if it continues at this growth rate, you could say comfortably that it would be 5 to 10% of the overall SWIFT volumes in 10 years' time.
Mm.
If it continues at this growth rate, the growth is currently accelerating. We're leaning into— and that's pre having regulatory clarity. You could make a meaningful argument that 5 to 10% worth of SWIFT volumes is getting moved across to something like the SWIFT for everybody else. I honestly think that that as an instant 24/7 cross-border dollar rail has real meaningful shot at happening.
Yeah. You spend many years on the kind of banking as a service side, also fintechs, also deeply into crypto. Who is the, uh, the group of companies or organizations that you think will get disrupted the most? Right? Because there's an argument to be made that it's the banks and dollar deposits. There's an argument to be made that it's the payment companies. There's an argument to be made that it's maybe this wave of stablecoin companies like the Circles of the world won't make it through and it's the next one. Who's going to get disrupted the most over the next 5 years?
All of them for different reasons. I actually think that the, the banks are looking at this as another payment rail, which is a mistake. It's another payments infrastructure. And I think that's an important point.
What's the difference between rail and infrastructure?
I wouldn't, as a, so it was actually Mike Hudak that said this. As a bank, there's so much I have to build to just track deposits and to move money. And then I have an entirely different system for my payments to my ledgering to my dealing with securities. And so, like, they have all of these different systems that sit side by side. Stablecoins is like this one cash layer that becomes like a foundational layer for everything. And then I can build on that treasury products, and I can build on that yield-bearing products, and I can build stocks. And this kind of infrastructure is just a different way of thinking about what it's really for. So who does that disrupt? Well, in the short term, nobody. But in the long term, I think the people with the biggest opportunity are the buy-side firms. There's a reason to my mind that BlackRock, that Franklin Templeton, that VanEck, that Fidelity are leaning so aggressively into the stablecoin space, into tokenizing real-world assets, which is they see a giant opportunity for narrow banks, shadow banks, to displace the banks themselves. And since Dodd-Frank The banks have been arguing about the lack of a level playing field. Narrow banking has already started.
Ah, okay, interesting. Is there a comparison to the euro-dollar system in this sense?
Yeah, massively. So the euro-dollar, if you're not familiar with it, was offshore dollars that appeared after World War II in foreign banks because you would be trying to rebuild Europe. You would take lots of dollars to be able to pay for things under the Marshall Plan, and they were just sort of sloshing around Europe at the time. And then in the, I think it was 1962, the Midland Bank in the United Kingdom figured out an interest rate arbitrage, 'cause the US had capped the interest rate on deposits, but the Bank of England had not. So you could hold your dollars in London, but make 4% instead of 2%. And that arbitrage was not initially liked by the US, but also it was sort of tolerated. And if you look at what happened with Tether initially, it's like, we really don't like this, we'll try and kill it, we'll try and deal with it. But now it's increasingly being sort of tolerated. So where we're heading to is this parallel universe in which there is this global clearing infrastructure, this dollar for everybody else. But the difference with the euro-dollar is I had to use SWIFT and I had to use a bank. Now I don't need a bank anymore. Now I don't need SWIFT anymore. I can clear dollars 24/7 as a payments company, as a wallet, as, as something else. So my right to win as a bank has definitely been eroded. My distribution has not. I think the forward-leaning banks from the banking as a service world might be able to do quite well.
Yeah, what does this mean for the fintechs, right? Anyone from, I guess you could bucket it as the neobanks, like the Revolutes on this side, and then maybe the more user-friendly brokerages like the Robinhood on this side.
Yeah.
What's the impact on that? And in light of how you're thinking about like banking getting disrupted as well.
So they've disrupted distribution in the UI, but the back office, they still rely on banks and incumbents for. But most of you might have seen the news that Ramp is offering stablecoin-linked cards in 101 countries. So Ramp, the spend management card, you know, the replacement to doing your expenses with Amex or whatever.
Yeah, we use Ramp. All of Blockworks runs on Ramp. Yeah.
Fantastic product.
Yeah.
Unless you live outside of a G20 country. Right. So the primary use case for businesses to have a product like that is if I live in the Global South, I can't get access to Netflix, ChatGPT, Amazon Web Services, because I don't have a credit card. I have no way of paying for those services. Stripe making stablecoins available means that I can accept your stablecoins, and you see some adoption for that acceptance. Ramp making stablecoin-linked cards available means you can pay for anything anywhere that a credit card is accepted. So now, Ramp has gone from being live domestically in the United States and supporting a few G20 markets through, through Passporting, to live in 101 markets. And that is a dramatic, dramatic shift through the partnership with Bridge. So, for fintech companies, it's almost like instant global expansion. On this entirely new set of rails. The reformed banker in me sort of winces at the, like, anti-money laundering might be an issue. Like, that's kind of scary to me. But we've also seen that from banking as a service. So I think the fintech companies like that just have this giant opportunity to go grab space. And Robinhood I mean, look, they're getting into tokenizing securities, they're doing stablecoin settlement at a weekend. They're really leaning hard. They have a credit card. Of all of the consumer brands in the United States, I would say that Robinhood is possibly best positioned to meaningfully threaten the consumer banks for consumer deposits and being that, that front page of my financial life.
Yeah, I tend to agree with that. Where, um, you talk about rails, what chain is, where is all of this settling?
Yeah.
Is this, uh, is this Ethereum? The L1's gonna win this game? Is this Solana? Is this, I think something like 60% of Tether is settling on Tron right now.
Yeah.
You've seen a bunch of fundraisers for new, new stablecoin chains essentially. Uh, Circle's got their, uh, CPM thing. CVM, yeah, exactly.
It's so early to say, isn't it? It's just so early to say. I think that's the big myth, is everybody thinks this is happening on Ethereum, and you're right, like 60% of it is happening on Tron, and it's global south to global south. The vast majority of, the number one corridor is Singapore to China, and then after that, it's US to various LATAM countries, and Europe to African markets. Those are the 3 big kind of corridors, and Tron is really big in all of those. Like, it's not just like something that's only popular in Asia or only popular in Global South to Global South. Like, it's actually that G20 to Global South. So that's the biggest surprise. Who's gonna win? Oh, people will shift. It's so early because people are shifting on price at the moment, but as more liquidity comes into it, price will become less and less the dynamic and risk will become more and more the dynamic. Because at the moment, it's very hard for a single B2B customer to move more than $1 million a day in and out of Mexican peso. And you think about the cross-border flow between the United States and Mexico on a daily basis at just one mid-sized regional bank. I mean, you'd break that in seconds. So there's just so much opportunity for all of that to completely shift. The honest answer is I have no clue. The honest, honest answer, which is what makes this conference super exciting is because the answer's probably walking around in here somewhere. You know, I'm a fan of the Avalanche model and what they're trying to do with like lots of different—
Proliferated L1s and—
Yeah, like a network of L1s. That could be interesting. The best thing about doing what you and I do is being a commentator is we get to say things like, I don't know. And all I do is look at this market and I have no clue.
Yeah, maybe if another question where the answer might be I don't know is, what's the circulating supply of stables right now? Something like 300 billion, 250, 300 billion? Yeah, 260, 270. OK, so let's call it 270. The Treasury put out the report saying that we'd be at 2 billion. Excuse me, $2 trillion. So we're growing 9x by 2028, right? So we're growing stablecoin supply. This is not from some pontificators like you and me. This is from the Treasury saying we're growing to $2 trillion in stablecoin supply by 2028.
Do you know their source for that? Because I looked into it.
Yeah, no, what—
they cited two sources. There's a report by Standard Chartered and by Citibank. And both of them are on the research side. And I understood the methodology behind both. Interestingly, Standard Chartered said that stablecoin supply will hit $2.1 trillion by 2028.
Yeah.
And the Citi folks, they had a high point of $3.2, but their midpoint case was $1.6 trillion by 2030. The difference between those two banks is Standard Chartered is the most active bank in the world by a meaningful distance when it comes to being the fiat leg of stablecoin transactions. So that was their source for that. So sorry, I—
No, that's interesting. I didn't know that. Who— so one thesis would say Circle and Tether are going to grow by 10x, right? If stablecoin supply grows 10x, they're both going to grow 10x. There's another thesis that says, look, folks like Agora are coming to the market, Athena, Sky, which is the new DAI. Bank of America gets into the game, like, you know, these banks get into the game, and actually Circle and Tether start to, over the years, lose market share and other people gain it. Do you have a thesis on how this plays out?
Yeah, so the technology of the issuer and the brand of the issuer are decoupling. So, like, I don't think about what flavor of dollar I'm going to send you if I'm giving you a $10 bill. 'cause we have this beautiful thing called the singleness of money. Even though the credit risk of a dollar is very different depending on which bank is holding it and what it's backed by, the letter T and the letter C and the letter E represents different credit risk of the issuer. Like, for this to take off, I don't wanna— most, the vast majority of people don't want a different letter of the alphabet to send somebody a dollar and then have to convert that. Like, I know a lot of the intermediaries, like, you know, your BVNKs and your Circles and your bridges kind of take care of that and they make it disappear. But not all stablecoins are created equal. And so, like, Athena is maintaining its peg through a delta-neutral hedge. That is not, in the genius act, a PPSI, a payment-linked stablecoin because it's doing something different. So, when you come to like what's gonna happen, are the banks gonna come in and do it, is anybody else gonna do it, I actually think what we see is the act of providing a technology platform to be able to issue and link things, decouple from being the underlying issuer themselves because the issuer will bifurcate to the asset managers like they're going to want to be the money market funds sitting behind it. And the issuer will bifurcate then also to tokenize deposits. There will be deposits that back it. And then what you see is that there will be so many of these. Yeah, there will be so many of them. Like there are so many banks and like there are so many ways to store your money today.
Yeah. Maybe we can talk FX markets, which is— it feels like the part of stablecoins that is like we're maybe a couple of years away from this becoming in the narrative. So right now, if you look at the total supply of stablecoins, it's 99% US dollar-denominated.
Yes.
But if you look at the FX markets, it's 57% US dollar-denominated. So let's say, let's say the, let's say the, let's say stablecoins are going to move. Let's say FX markets will move on-chain. Yeah. And we can kind of maybe agree on that. And the, let's say it doesn't go down to 57% US dollar-denominated, but it goes to 70%. So that's a 29% delta. Who wins the 29% there? Are we going to see some European stablecoin get big? Are we going to see some JPY stablecoin get big? I don't know if you have takes on that.
Yeah, I honestly think— well, you can see it in EuroCB. The fastest growing non-US dollar stablecoin is the euro from Circle. As more sophisticated actors come into stablecoins, the more sophisticated treasury managers are coming into stablecoins, therefore people are trying to diversify their currency risk and you're seeing hedging strategies emerge. There's the OTC desks are emerging, the brokerages, the FX brokerages are emerging. There's a company funded today or yesterday, Velocity, you know, a bunch of folks that have payments and industry background, they're integrating with ERPs to make Fortune 500 companies just have an ability to move money cross-border from any currency instantly. And what's that going to mean? It's going to mean you need to build lots of partnerships with lots of local banks for that FX infrastructure to come. So I do think in 2, 3 years' time, building that last mile out will be hard. Yeah.
Bullish or bearish on Circle as a business right now?
I hate to say it, but bearish. And I think it's because they were bearish as they exist today, but they— goddamn, they are good at reinventing. That is like a cockroach. That thing just won't die. It just keeps reinventing and keeps impressing you. Like, they're really impressive business.
That's a dangerous question to ask at a stablecoin conference because there's like a 10% chance someone from Circle is out here, so yeah, careful what you say. They don't have—
like, mad respect to them, but I think their future, and they know it and you can see it, is CPN, because what everybody's gonna want is risk management, KYC, AML. The what happens when something goes wrong stuff has not been built, and the big liquidity wants the answer to what happens if something goes wrong.
Yeah, we gotta wrap up 'cause we're almost at time. Most outlandish, biggest stablecoin prediction for the next couple of years? Anything come to mind?
Uh, the first bank to issue its own stablecoin will be Bank of America.
Bank of America. Will Facebook launch a stablecoin in the next 12 months?
Not in the next 12 months. Next 2 years? I think they'll support stablecoin settlement within 2 years if they can, if they can get it done. I think that that's absolutely an objective and a goal.
You don't think the regulators will block it?
I think they'll— some will try. Um, Europe will, and then it will become a whole hot potato thing.
Yeah, there you go. Simon Taylor, everybody. Thank you so much for the time.
More from Jason
From Media Company to Crypto's Market Infrastructure: Jason Yanowitz on Blockworks' Transformation
Lessons From Building A Crypto Media Company — Jason Yanowitz | The Danny Miranda Podcast 179